
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AI Code Scanning Might Change The Case For Investing In Trend Micro Stock
- Trend Micro’s TrendAI unit recently expanded TrendAI Vision One’s support for Claude’s Compliance API and introduced a private preview of Autonomous Vulnerability Discovery, an AI-driven service on Amazon Bedrock that flags and verifies fixes for source-code vulnerabilities using Zero Day Initiative research.
- The twin focus on AI agent oversight and automated code security signals a push to make Trend Micro’s enterprise platform more embedded in day to day customer workflows. This can influence how durable its recurring revenue and customer retention prove to be.
- We will examine how Trend Micro's investment narrative is shaped by AI driven Autonomous Vulnerability Discovery in TrendAI Vision One.
Scan beyond Trend Micro and line up other AI security and infrastructure plays that could see similar pressure on customer adoption through our hand picked 90 AI infrastructure stocks today.
Trend Micro Investment Narrative Recap
To own Trend Micro, you need to trust that its pivot toward AI driven security, anchored in Vision One and TrendAI, keeps enterprise contracts sticky while it works through weaker areas like consumer and perpetual licenses. The short term swing factor is whether this AI stack turns existing demand into higher quality recurring revenue rather than one off projects.
The biggest near term risk is simple. Heavy AI and consumer transformation spend could weigh on margins if take up is slower than hoped, while issues in online settlements or renewals outside Japan would add pressure. This week’s announcements help the product story but do not by themselves remove those execution risks.
The most relevant update is Autonomous Vulnerability Discovery inside TrendAI Vision One. It pushes Trend Micro deeper into customers’ development workflows by scanning existing Git repositories on Amazon Bedrock, then pairing model findings with Zero Day Initiative experts who validate severity, write ups and patch verification.
That kind of embedded service can support the analyst narrative around higher quality ARR and use of AI to improve efficiency. It also raises a new execution bar. Management needs to prove the AESIR engine scales across large codebases with low false positives, that customers accept scoped, supervised scans, and that pricing tied to scan scope turns into repeatable, margin friendly business.
What The Trend Micro Consensus Is Pricing In
Trend Micro's analyst story is built around a clear set of numbers. The current consensus assumes revenue grows by 6.1% a year, with earnings today at ¥37.4 billion and forecast consensus earnings of ¥47.9 billion by 2029. That implies an earnings increase of about ¥10.5 billion from current levels.
Trend Micro's narrative projects ¥337.3 billion revenue and ¥47.9 billion earnings by 2029. This requires 6.1% yearly revenue growth and an earnings increase of about ¥10.5 billion from ¥37.4 billion today.
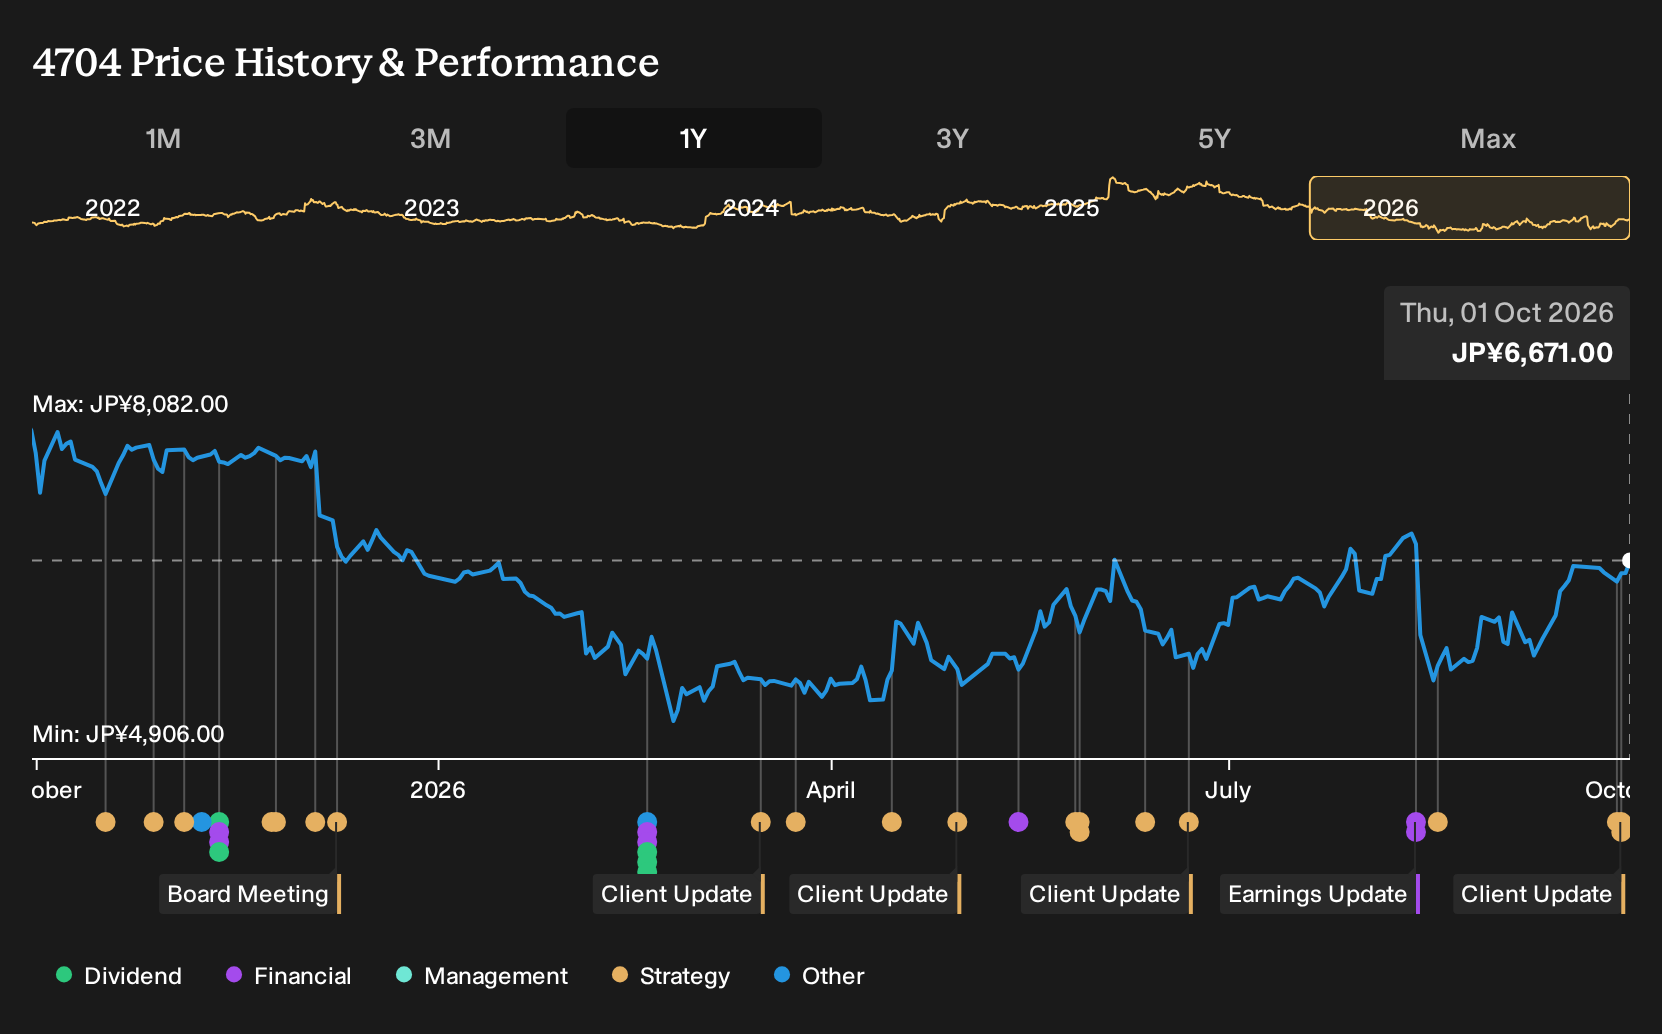
Uncover why Trend Micro's fair value indicates a valuation gap that aligns with its current price.
Exploring Other Perspectives
One alternate view treats Trend Micro’s AI push as a real earnings catalyst. The most optimistic analysts were already penciling in revenue of ¥359.4 billion and earnings of ¥52.7 billion by 2029, compared with ¥337.3 billion and ¥47.9 billion in the baseline set, before any of this Claude and AESIR news landed. You can treat today’s updates as a prompt to compare those extremes and decide which storyline feels closer to your own expectations.
Explore 2 other Trend Micro fair value estimates, including one that suggests as much as 41% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own research and judgment.
- A great starting point for your Trend Micro research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Trend Micro. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trend Micro's overall financial health at a glance.
Looking For More Investment Ideas Beyond Trend Micro?
Trend Micro may fit your thesis, but you do not need to stop your research there. The Simply Wall St Screener lets you quickly scan for other companies that line up with your risk tolerance, income needs, or focus on quality.
- If resilience matters most to you, start with a shortlist of 21 resilient stocks with low risk scores that rate well on stability and downside protection.
- If you prefer to back underappreciated quality, focus on businesses in our 76 high quality undiscovered gems that pair solid fundamentals with limited current attention from the market.
- If balance sheet strength is non negotiable in your process, filter for companies in the list of solid balance sheet and fundamentals (23 results) to keep financial risk in check while you hunt for opportunities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com