
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
HF Sinclair Stock And Two Oil Names With Diesel Market Exposure
Energy markets have turned into a pressure cooker, with diesel supplies squeezed by export bans, war in Iran and talk of emergency stockpile releases reshaping trade flows almost overnight. That kind of stress can punish some companies while opening the door for others that are better positioned on crude production or refining. This article looks at 3 stocks from our Integrated Oil & Gas Producers and Refiners screener that appear most exposed to these shocks.
The three stocks highlighted below are just a sample, with our full Integrated Oil & Gas Producers and Refiners screen surfacing 21 more companies with equally compelling narratives that are not covered here. If you want to go straight to the source and identify, compare, and analyze potential high-conviction ideas, head into the Integrated Oil & Gas Producers and Refiners screener.
HF Sinclair (DINO)
HF Sinclair is one of the clearest refiners in this screener for getting direct exposure to tight diesel and gasoline markets, with its network of US plants and fuel brands closely tied to how wide those cracks stay in a supply constrained world.
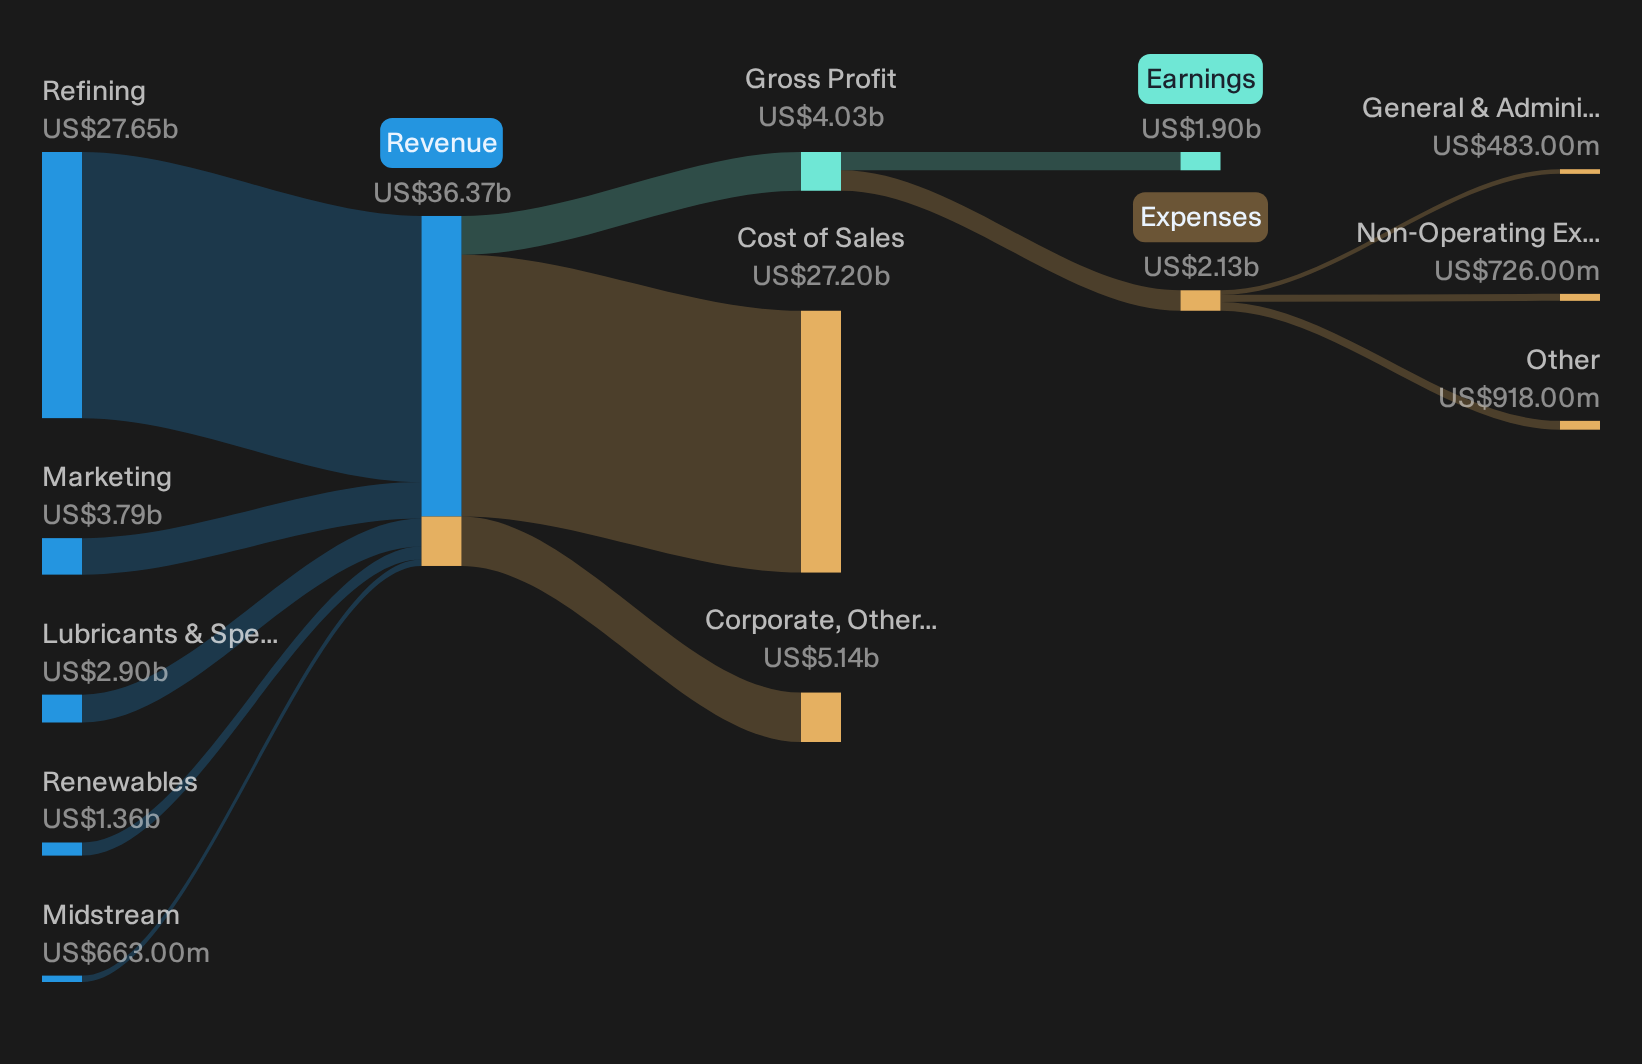
HF Sinclair runs a broad energy platform anchored in US refining, which generated about US$27.7b of its revenue, with smaller contributions from Marketing at roughly US$3.8b, Lubricants & Specialties near US$2.9b, Renewables at about US$1.4b and Midstream around US$663m, giving the company a US$18.8b market cap.
"Sustained global demand for transportation fuels, particularly strong diesel consumption in the West and developing economies, combined with limited new refinery capacity, positions HF Sinclair to benefit from high utilization and favorable crack spreads, positively impacting future revenues and gross margins.
What really moves the needle next is how one still developing pressure on diesel pricing filters through those refining margins investors care about most.
As those diesel margins keep shifting, the full narrative for HF Sinclair maps how HF Sinclair could respond, including where refining strength might be masking emerging risks for investors.
Eni (BIT:ENI)
Eni fits neatly into this Integrated Oil & Gas Producers and Refiners theme, combining large upstream production, European refining and newer low carbon activities that can all be influenced very directly when crude and diesel markets tighten.
Eni is a global integrated energy group, producing oil and gas and running refineries as well as fuel and power marketing, which ties directly into the screener’s focus on producers with refining exposure. Most revenue comes from Exploration & Production at about €55.7b, with Enilive at roughly €21.3b, Refining and Chemicals near €19.3b and Global Gas & LNG Portfolio and Power around €17.5b, against a market value close to €70b.
"Eni's strategic expansion in LNG, highlighted by leading floating LNG investments in Africa, the Eastern Mediterranean, and new ventures in Argentina and Southeast Asia, positions the company to capture rising global demand for diverse and secure natural gas supplies."
What really matters for investors now is how one unresolved pressure on future margins and cash generation ultimately feeds through that integrated Eni model.
That unresolved pressure is exactly why reading the full narrative for Eni can help you see how Eni’s LNG push, refining mix and risk profile could be accelerating.

SunocoCorp (SUNC)
SunocoCorp is an energy infrastructure and fuel distribution player, tying directly into the Integrated Oil & Gas Producers and Refiners theme through its 14,000 mile pipeline network, 160 terminals and refinery segment. Most revenue comes from Fuel Distribution at about US$38.8b, with Terminals at roughly US$1.7b and Pipeline Systems near US$800m, against a market value near US$3.8b.
SunocoCorp provides exposure to refined product pricing through a mix of pipelines, terminals, fuel distribution and a smaller refinery. It generates throughput-driven revenue of US$38.8b in Fuel Distribution alone and offers a high dividend yield. A key issue is how pressure on funding costs and payout coverage ultimately shapes the fuel margins that investors focus on most.
Those pressure points on funding and payouts make it worth running through the SunocoCorp financial health report before fuel margins move in a direction you did not expect.

Seeking Fresh Alternatives Beyond Oil?
New ideas move fast. By the time most investors notice a breakout, momentum has already flown. Scan these curated picks while they are still under the radar for now and consider them early.
- Target steadier compounding by filtering for companies with strong reserves, profits and balance sheets using a curated list of solid balance sheet and fundamentals (25 results) before the crowd catches on.
- Ride structural demand for electricity, AI and EVs by zeroing in on infrastructure players in the 39 power grid technology and infrastructure stocks while valuations still reflect old assumptions.
- Position for long-haul energy demand by tracking grid and reactor suppliers through the curated 19 nuclear energy infrastructure stocks while sentiment is still cautious and opportunities stay mispriced.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com