
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Taiwan Semiconductor Manufacturing (TSM) Could Be 21% Overvalued As Texas Plans Draw Focus
Taiwan Semiconductor Manufacturing (NYSE:TSM) is back in focus after reports it is weighing a fresh chipmaking hub in Texas, in addition to the planned US$265b build out in Arizona.
The Texas headlines arrive after a strong run for Taiwan Semiconductor Manufacturing, with the share price up 42.73% year to date and a 59.43% total shareholder return over 12 months, while a roughly 9.84% 30 day share price gain hints at firming momentum.
Scan for other chipmakers trying to harness similar AI and fabrication momentum as Taiwan Semiconductor Manufacturing with a curated set of 90 AI infrastructure stocks.
After a near 60% total return over 12 months and talk of trillion dollar territory, Taiwan Semiconductor Manufacturing now faces a tougher test. Does the current price still offer sufficient potential to justify the risks?
Most Popular Narrative: 20.6% Overvalued
Taiwan Semiconductor Manufacturing closed at $456.19, while the most followed narrative pegs fair value at $378.29. This implies the stock trades at a premium and reflects a lot of good news already.
TSMC is the rarest of things: a monopoly whose dominance is rooted not in regulatory capture or historical accident, but in genuine technological supremacy. The company has spent decades perfecting the art of manipulating matter at atomic scales, and the cumulative knowledge embedded in its fabrication processes is essentially irreproducible.
See why 117 investors see Taiwan Semiconductor Manufacturing as 21% overvalued.
Result: Fair Value of $378.29 (OVERVALUED)
Still, Taiwan Semiconductor Manufacturing carries two big swing factors that could shake this story: geopolitical shock around Taiwan and any loss of key chip customers.
Find out about the key risks to this Taiwan Semiconductor Manufacturing narrative.
Another View: What Multiples Say About Taiwan Semiconductor Manufacturing
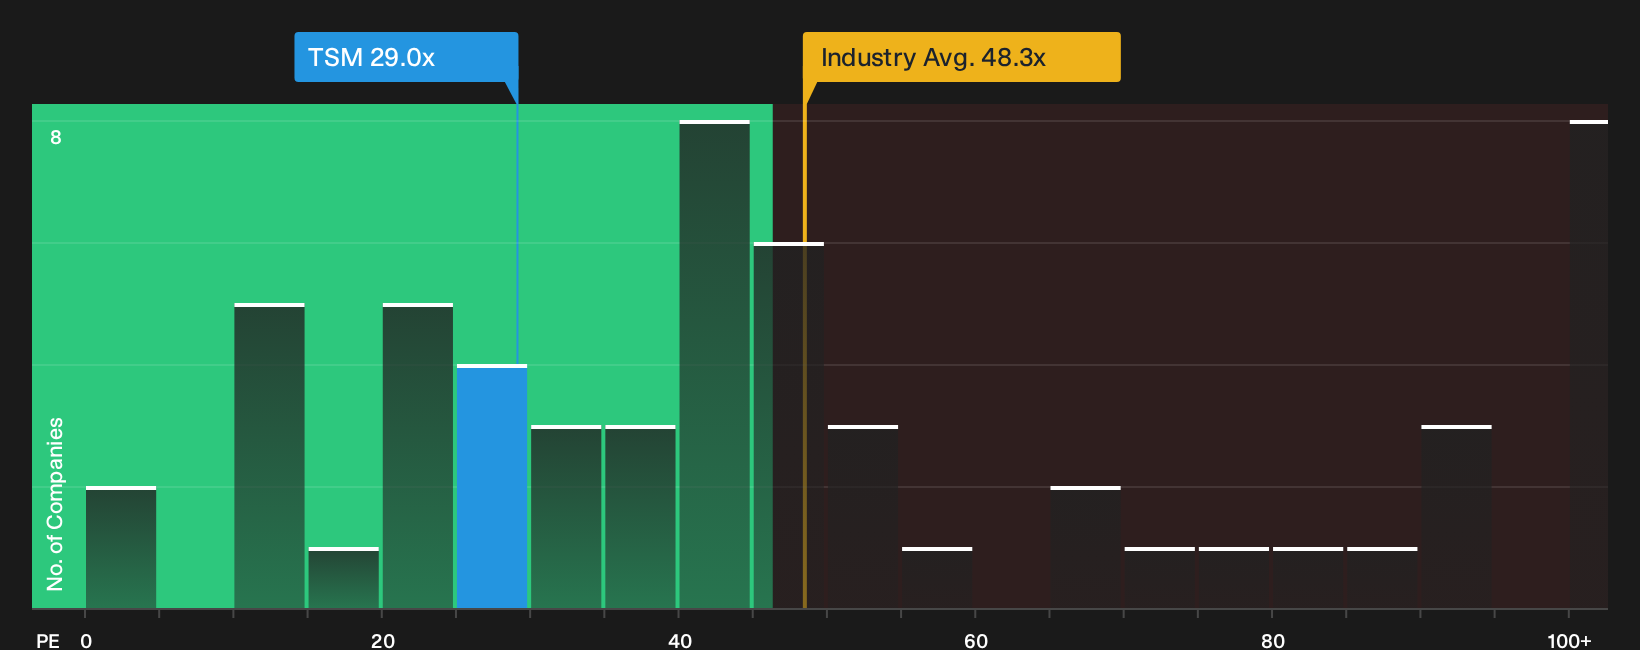
DCF work points to Taiwan Semiconductor Manufacturing trading above an intrinsic value estimate, yet the market is not unanimous. On P/E, the stock changes hands at about 29x, while the US semiconductor group averages 48.3x and close peers sit near 62.7x. The fair ratio sits at 43.3x, which is higher than today and suggests the market could shift closer to that level over time. That gap lowers valuation risk on earnings, even if cash flow models flag less room for error. Which signal do you trust more when the story is this powerful and this crowded?
To see how this earnings-based view stacks up against the price you are paying today, and where that may leave limited room for mistakes, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Strong stories can pull investors in quickly. Taiwan Semiconductor Manufacturing carries both clear risks and meaningful potential rewards. Consider moving quickly, reviewing the underlying data, and weighing the 4 key rewards and 1 important warning sign.
Looking for more ideas beyond Taiwan Semiconductor Manufacturing?
Do not stop with Taiwan Semiconductor Manufacturing. Use fresh screeners to surface stocks that fit your style, then pressure test them before committing real capital.
- Target potential mispricings by scanning for companies that combine strong fundamentals with room for sentiment to catch up through a curated set of 31 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses that pair higher yields with resilience using this group of 7 dividend fortresses.
- Protect your downside first by filtering for robust balance sheets and durable cash generation inside the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com