
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Brown & Brown (BRO) Stock May Be Overvalued On Its 34% Slide
Brown & Brown has seen a sharp reset in its share price over the past year, which puts the spotlight squarely on what investors are paying for its earnings today. With that backdrop, the key issue is whether the current valuation of Brown & Brown is still aligned with the profits the insurance broker is generating.
- The stock has fallen 33.7% over the past year, which raises the question of whether that pullback now better reflects the earnings power of the business.
- The company relies on a commission driven insurance brokerage model, so its earnings profile is closely tied to how efficiently it can convert client relationships and policy volumes into steady, repeatable profit.
- The analysts covering Brown & Brown have run their own numbers. See what analysts think Brown & Brown's shares could be worth.
The stock's next move may depend on whether Brown & Brown's current earnings are strong enough to justify the price investors are paying for the shares.
If you want a broader starting point for your research alongside Brown & Brown's recent pullback, a focused screen of companies with compressed valuations and solid fundamentals can help. You can start with the 31 high quality undervalued stocks.
Is Brown & Brown Getting Expensive on Earnings?
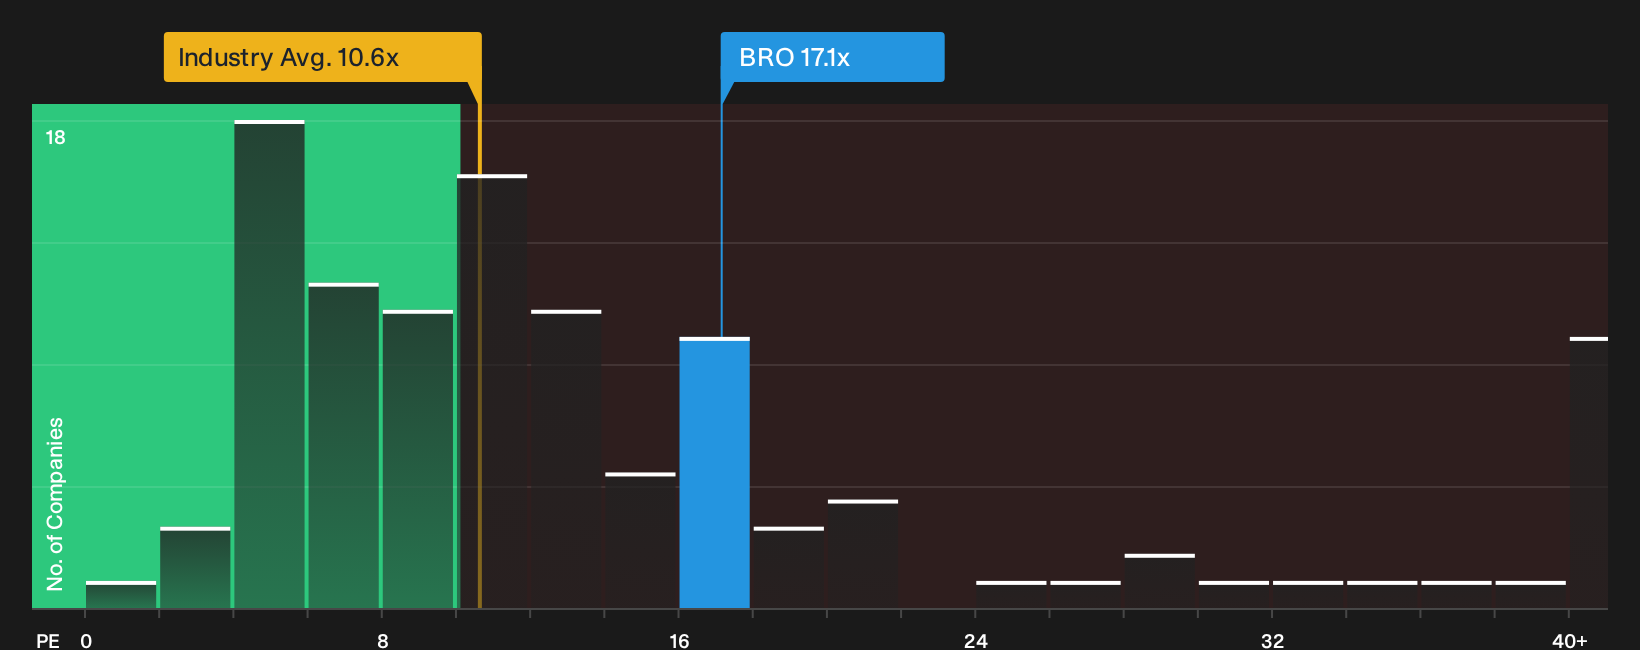
P/E suits Brown & Brown because earnings are a key yardstick for a commission driven broker. On this measure the stock trades on about 17.1x, which is above the Insurance sector average of roughly 10.6x but below the peer group closer to 28.7x. That mix often points to investors giving the business some credit for its profitability profile while still pricing it at a discount to higher rated rivals.
A tailored fair value framework that blends Brown & Brown's growth outlook, margins, risk and size suggests a lower P/E would better line up with its fundamentals, so the current 17.1x screens overvalued against that yardstick. For you as a shareholder or potential buyer, the key question is whether the quality and durability of its earnings stream justify paying a premium to the wider Insurance industry while still accepting a discount to peers. Explore the numbers behind Brown & Brown's P/E valuation.
The Brown & Brown Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Brown & Brown's P/E puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today, and how those paths compare on the Community page. Each scenario links a fair value to a specific mix of possible catalysts and risks so you can later see which storyline is closest to how Brown & Brown's business actually evolves.
One of the top community narratives on Brown & Brown: 20% undervalued
"Brown & Brown is rolling out AI enabled submission, policy checking and billing tools that are already saving tens of thousands of hours a year..."
Discover why this Narrative puts Brown & Brown at 20% undervalued.
One more Brown & Brown factor to check before you make a move
Analyst projections give you another lens on Brown & Brown, letting you compare where specialists think earnings could head over the next few years with where the shares trade today. Explore where analysts expect Brown & Brown to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com