
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Hershey (HSY) Worth Revisiting Following Its International Leadership Change?
New international leadership gives Hershey investors something fresh to assess
Hershey (HSY) just reshaped its global bench, naming Amanda Almond as President, International, to succeed long-time executive Rohit Grover, a move that puts fresh attention on how the business approaches its markets outside the U.S.
Recent price action suggests investors are still cautious. Hershey’s share price is down about 13% year to date and roughly 11% over the past month, while the 1 year total shareholder return has declined about 14%. This points to fading momentum despite marketing pushes and the international leadership change.
Scan beyond Hershey for other consumer stocks that may be setting up for a rebound by using our curated list of 31 high quality undervalued stocks.
Bulls see Hershey’s recent share price slide and international refresh as an entry point. Bears point to pressure on returns. Which side lines up better with the current valuation setup investors face today?
Most Popular Narrative: 99% Overvalued
Hershey last closed at $157.61, while the most followed narrative on the stock, according to Esteban, pegs fair value far lower at $79.25. That gap frames the current debate around whether recent weakness already reflects slower growth and cocoa-related pressure or not.
A fortress brand and scale position in U.S. confectionery (Reese’s, Hershey’s, Kisses) generates ~23% through-cycle ROIC and exceptionally durable free cash flow that fell only ~13% even in the worst input-cost year on record. The 2025 cocoa shock, a ~60% GAAP EPS collapse driven largely by non-cash hedge mark-to-market, obscured an underlying cash engine that remained intact.
See why 6 investors see Hershey as 99% overvalued.
Result: Fair Value of $79.25 (OVERVALUED)
Still, the Hershey story could crack if cocoa costs stay elevated for longer than expected, or if international expansion drags on margins instead of supporting them.
Find out about the key risks to this Hershey narrative.
Another View Of Hershey’s Valuation
The narrative fair value of $79.25 presents Hershey as sharply overvalued, yet our DCF model shows a very different picture. On that measure, HSY at $157.61 is trading 46.8% below an estimated future cash flow value of $296.07, which points to undervaluation instead.
The gap between a user-driven story that cuts expected revenue and an SWS DCF output that leans on high quality earnings and resilient cash flows leaves investors with a simple question: Which set of assumptions feels closer to how Hershey will actually convert chocolate, snacks, and cocoa volatility into cash over the next decade?
Look into how the SWS DCF model arrives at its fair value.
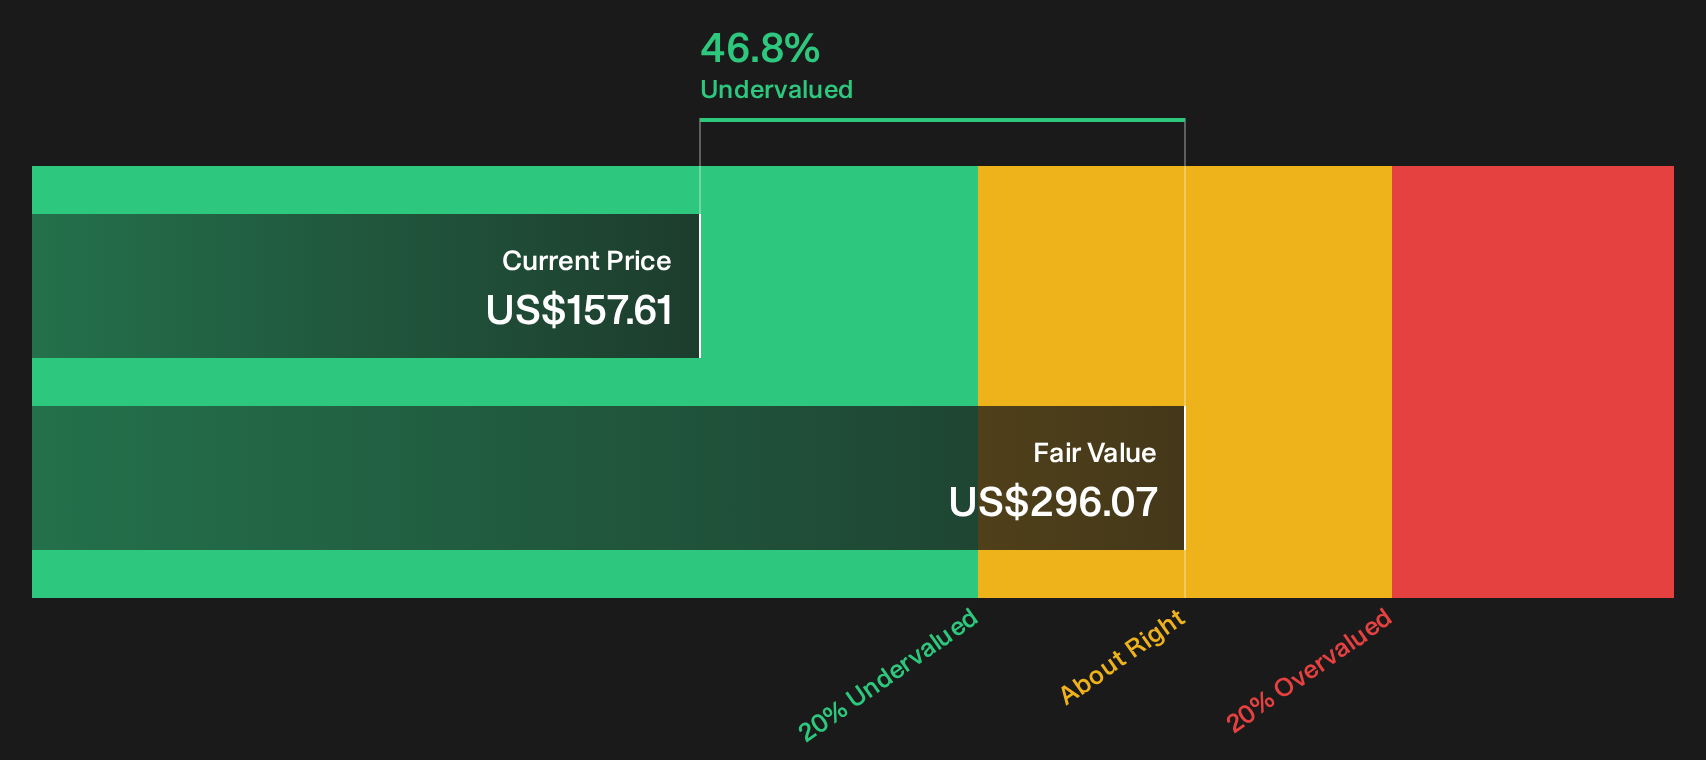
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hershey for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed mood around Hershey leaves you undecided, take a moment to review the same facts and pressure test your own stance with 4 key rewards and 1 important warning sign.
Looking for more Hershey investment ideas?
Still on the fence about Hershey and its valuation debate? Do not stop here. Use the Simply Wall Street screener to spot other opportunities before they move.
- Target resilient compounding by scanning companies with consistent cash strength and low leverage through the list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a discount by filtering for companies that combine strong fundamentals with attractive pricing using the 19 high quality undiscovered gems.
- Dial down volatility in your portfolio by focusing on businesses with steadier risk profiles via the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com