
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AppLovin (APP) Stock May Still Have Upside Despite AI Lawsuit Pressure
AppLovin has been through a sharp reset in 2026, with a steep share price pullback colliding with headline legal disputes. This leaves a clear question for investors about whether the current valuation still lines up with the company’s earnings power. With the stock under pressure after a very large multi year gain, the key issue now is what portion of that earlier optimism its profit profile can realistically support.
- Over the past 3 years the stock has delivered a very large return of about 7x, so a lot of earlier expectations have already been reflected in the price and are now being reassessed against the underlying profit stream.
- Fresh lawsuits over AI disclosures and data use may influence how investors think about future growth, margins and potential legal costs, which can all feed directly into how much they are willing to pay for each dollar of AppLovin’s earnings.
- Your read on AppLovin is one view; the desks covering it have another. See what analysts think AppLovin's shares could be worth.
For investors, the debate is whether AppLovin’s current share price is adequately supported by its earnings when judged against the Fair Ratio benchmark.
If this legal and valuation story around AppLovin has you rethinking how you compare earnings and headline risk, it can help to review a wider set of 31 high quality undervalued stocks.
Is AppLovin Still Cheap on Earnings?
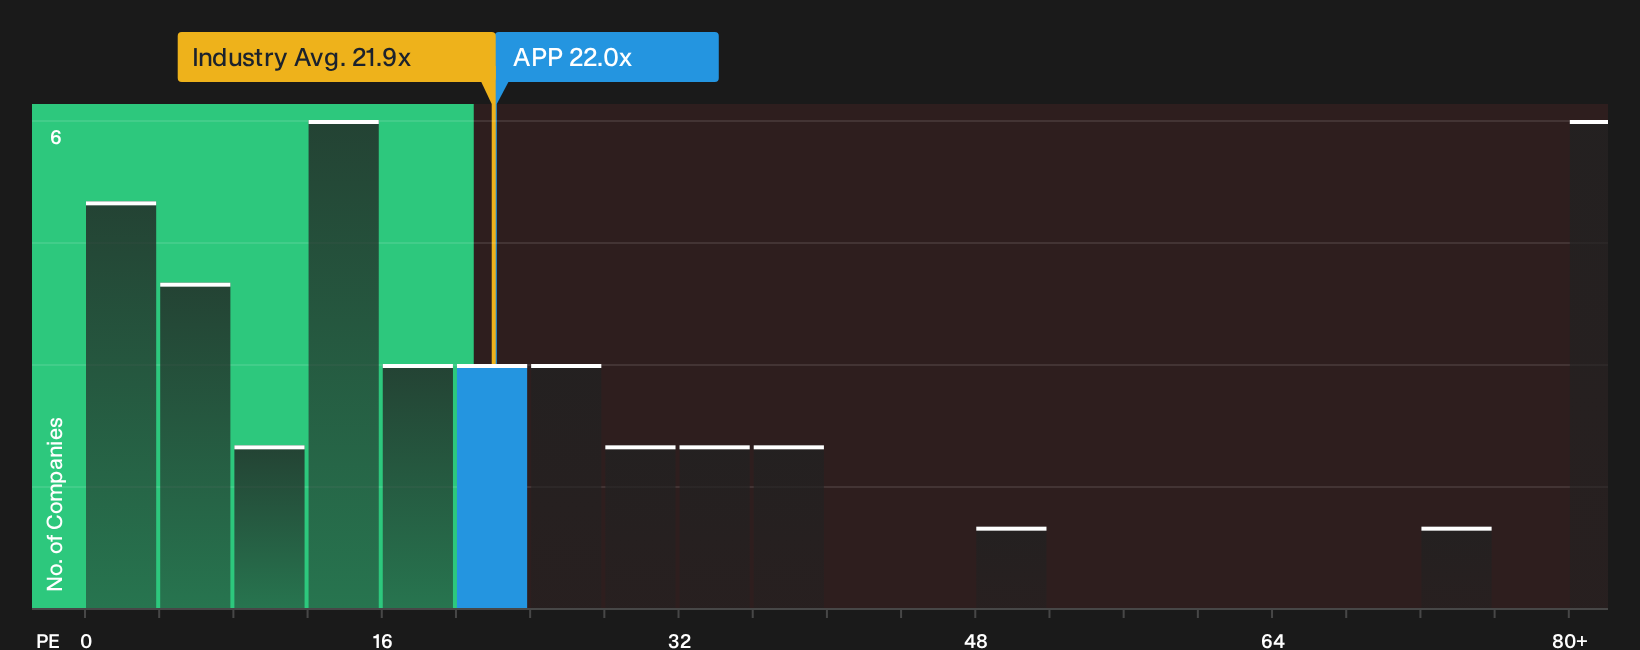
The P/E ratio fits AppLovin because earnings are now a key yardstick for how much investors are paying for its AI and ad tech story. On headline numbers, the stock trades on about 22.0x earnings, which is slightly above the broader media sector on 21.9x but below the peer group closer to 30.8x. That combination means the market is attaching a premium to AppLovin relative to the average media stock, while still pricing it below some more expensive direct competitors.
Because of the recent securities fraud class action focused on AI disclosures, this lower P/E versus peers suggests investors are already factoring in additional legal and execution risk. The Fair Ratio, which reflects what multiple might fit AppLovin’s profile in terms of growth, margins, scale and risk, sits above the current P/E, so the shares trade at a discount to that tailored benchmark. For anyone weighing whether the reset in sentiment has gone too far, the current P/E gap to the Fair Ratio is the primary number to examine next. Explore the numbers behind AppLovin's P/E valuation.
The AppLovin Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the AppLovin valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today’s price. They also tie each storyline to its own view of fair value based on specific catalysts and risks, so you can track over time which version of AppLovin’s future is actually unfolding.
One of the top community narratives on AppLovin: 43% undervalued
"Most ad platforms sell impressions or clicks. AppLovin sells outcomes..."
Discover why this Narrative puts AppLovin at 43% undervalued.
One more AppLovin clue worth checking before you move on
Everything so far has focused on what AppLovin looks like today, yet analyst models for where its earnings and business mix could be in a few years offer a separate benchmark for you to compare against the current share price. Explore where analysts expect AppLovin to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com