
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Yakult HonshaLtd (TSE:2267) Stock Looks About Right As Shares Fell 23%
Yakult HonshaLtd has rewarded patient shareholders over the past year, yet its longer history tells a tougher story. The key question is whether today's share price lines up with the earnings that support it. For anyone tracking the stock, the issue is less about short term swings and more about what the current valuation implies about the business Yakult HonshaLtd needs to be.
- Over the past 3 years the share price has fallen 22.8%, which puts the current valuation debate squarely on whether the underlying earnings profile justifies staying invested.
- The group relies on branded consumer health products and recurring demand, which can support earnings consistency if margins and cost control hold up over time.
- The analysts covering Yakult HonshaLtd have run their own numbers. See what analysts think Yakult HonshaLtd's shares could be worth.
For investors, the debate is whether the earnings that Yakult HonshaLtd currently generates are enough to support the present share price or whether expectations have moved ahead of the underlying business performance.
If you are considering whether Yakult HonshaLtd’s recent 21.6% 1-year gain adequately reflects its earnings profile, a focused stock screen can broaden your options with 17 high quality undervalued stocks.
Is Yakult HonshaLtd Fairly Priced on Earnings?
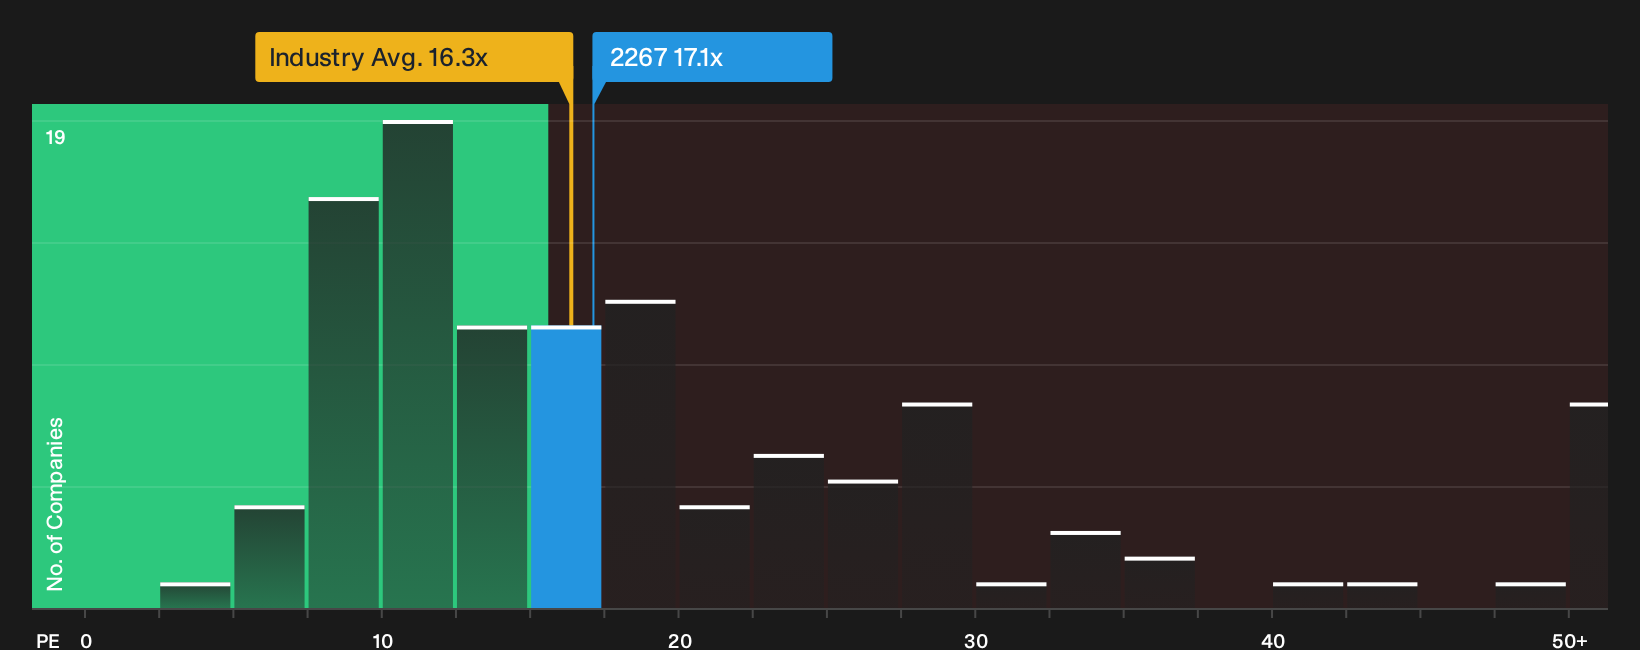
The P/E ratio works well for Yakult HonshaLtd because earnings are a key driver for a branded consumer products group. The stock trades on a P/E of 17.1x, which is slightly above the food industry average of 16.3x and close to the peer group mark of 16.2x. That puts Yakult HonshaLtd on only a modest premium to sector and peer benchmarks rather than at an extreme.
A more tailored yardstick that blends the company’s growth profile, margins, size and risk points to a similar earnings multiple as a reasonable anchor for Yakult HonshaLtd. The current 17.1x sits just above that level, so the market is only asking for a small uplift in valuation versus what that framework suggests. For you, the key question is whether Yakult HonshaLtd’s brand strength and earnings resilience justify paying that slight premium or whether comparable options on lower P/E ratios look more appealing. Explore the numbers behind Yakult HonshaLtd's P/E valuation.
The Yakult HonshaLtd Narrative: What Would Justify Today's Price?
Narratives for Yakult HonshaLtd pick up where the P/E debate leaves off and spell out which paths for future growth, profitability and earnings would need to play out for the stock to be worth materially more or less than it is today on Simply Wall St's Community page. Instead of stopping at a single number from a ratio or model, they describe the future business conditions that figure rests on so you can watch whether those assumptions keep lining up with reality.
Yakult HonshaLtd splits opinion, with one camp seeing buybacks and health trends as underappreciated while the other focuses on structural headwinds and regulatory friction.
Bull case: 17% undervalued
"Further buybacks and shareholder-return initiatives, supported by Yakult's strong balance sheet and steady global cash flows, could materially boost EPS…"
Discover why this Narrative puts Yakult HonshaLtd at 17% undervalued.
Bear case: 37% overvalued
"Heavy reliance on the core Yakult probiotic drink, combined with only limited progress in diversifying the product portfolio, leaves the company uniquely vulnerable…"
Explore why this Narrative puts Yakult HonshaLtd at 37% overvalued.
Before you stop at the Yakult HonshaLtd share price, look at who is steering the ship
The people setting priorities at Yakult HonshaLtd and how their pay packets line up with your interests can matter as much as any P/E comparison. See who runs Yakult HonshaLtd and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com