
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Tsakos Energy Navigation (TEN) Old Tanker Sale
- Tsakos Energy Navigation sold its oldest product tanker to UAE based interests as part of a planned US$3b fleet renewal program, reinforcing its focus on younger, more efficient vessels.
- The disposal of an aging ship frees capital and operating capacity for Tsakos Energy Navigation to allocate toward higher spec tonnage and tighter environmental compliance, which directly affects long term cost discipline.
- This analysis examines how Tsakos Energy Navigation's investment narrative is influenced by the tanker sale within its US$3b fleet renewal plan.
Tsakos Energy Navigation Investment Narrative Recap
To own Tsakos Energy Navigation, you need to be comfortable with a tanker operator that leans hard into fleet renewal and long term contracts while carrying meaningful leverage and exposure to fossil fuel transport. The sale of the oldest product tanker fits that story cleanly. It keeps the focus on younger ships, efficiency and regulatory compliance rather than changing the core thesis.
The key short term swing factor is still how well Tsakos Energy Navigation converts its young fleet and contracted backlog into cash against debt and capex demands. A single ship sale looks modest against a US$3b renewal plan. Balance sheet pressure and any freight rate softness remain the biggest near term risks.
The upcoming Lytham Partners Fall 2026 Investor Conference on 29 September gives you a near term touchpoint to see how management frames this renewal phase. With Mike Kimble presenting, investors get a chance to hear how the tanker disposal sits within Tsakos Energy Navigation’s broader capital allocation and chartering mix.
This event matters most for clarity. You can listen for concrete detail on progress against the US$3b program, how quickly older tonnage is being recycled into eco ships, and what that implies for operating costs, utilization and debt service. Any updated context on earnings volatility, contract coverage and refinancing plans will feed directly into how you weigh catalysts versus balance sheet and demand risks.
Tsakos Energy Navigation's current earnings sit at $132.3 million, with analysts forecasting $73.0 million by 2029. This implies an earnings decline of about $59 million. Consensus estimates also point to revenue falling at about 5.2% per year, leading to projected 2029 revenue of $679.5 million and earnings of $73.0 million.
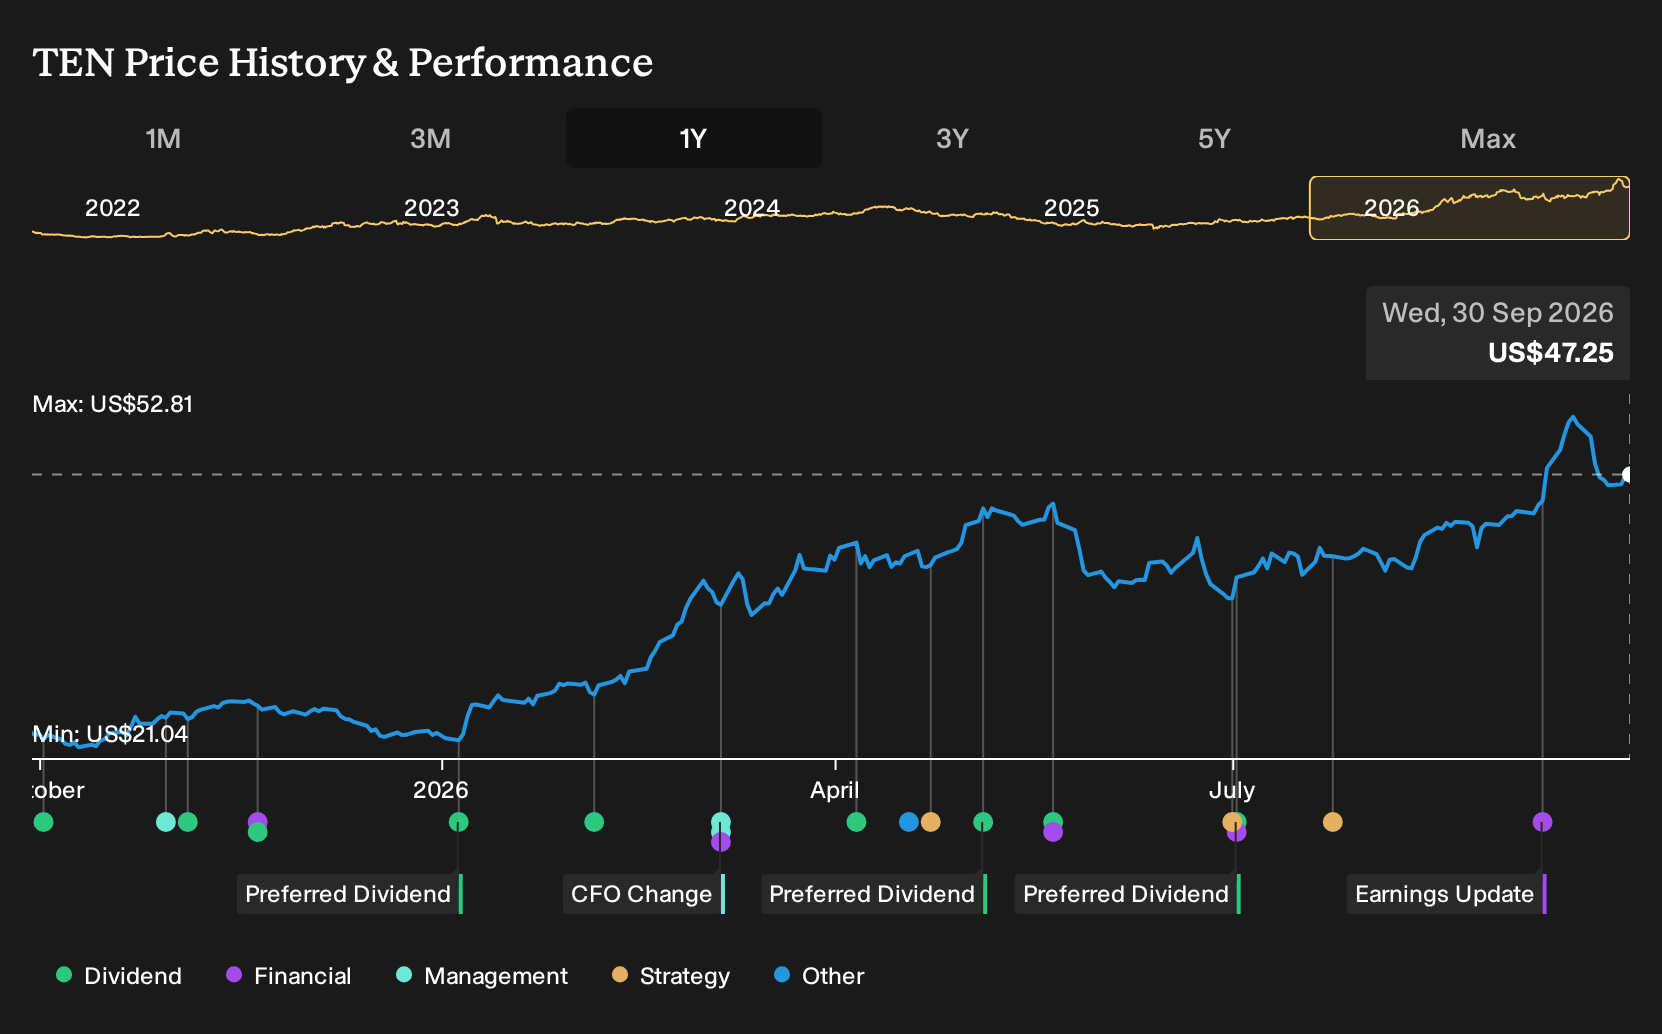
Uncover why Tsakos Energy Navigation's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate angle to watch is the risk that decarbonization hits Tsakos Energy Navigation harder than consensus expects. The most bearish analysts were already modeling revenue of about US$524.0 million and earnings of just US$10.1 million by 2029. That is a far sharper squeeze than the baseline, and the latest tanker sale plus conference commentary could easily shift those views again.
Explore 3 other Tsakos Energy Navigation fair value estimates, including one that suggests as much as 70% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Tsakos Energy Navigation research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Tsakos Energy Navigation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tsakos Energy Navigation's overall financial health at a glance.
Looking for more investment ideas beyond Tsakos Energy Navigation?
If the Tsakos Energy Navigation story has sharpened your view on balance sheets, capital intensity and earnings risk, broaden that lens by scanning for other businesses that match your preferred mix of resilience, value and income using the Simply Wall St Screener.
- For investors who want income that aims to keep pace with payouts elsewhere in the market, review a curated set of high yielding opportunities through 7 dividend fortresses.
- If resilience and downside protection matter most, focus on businesses with steadier risk profiles by starting with 31 resilient stocks with low risk scores.
- When the goal is to find quality at a sensible entry price, cast a wider net across fundamentally strong yet potentially mispriced stocks using 31 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com