
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Furukawa Electric (TSE:5801) Could Be 13% Below Fair Value After Raised Guidance
Furukawa Electric (TSE:5801) moved back into focus after management raised earnings guidance for the six months to September 30, 2026, lifting expected profit attributable to owners and interim profit per share.
That guidance revision lands on a stock that has already seen intense interest. Furukawa Electric’s share price is up 6.1% over the past month and has delivered a year to date share price return of 288.3%, while the 1 year total shareholder return of 369.6% and very large 3 and 5 year total shareholder returns point to momentum that has been building over a much longer stretch.
Scan how Furukawa Electric fits into the broader theme of fast-moving industrials by comparing it with our curated 39 power grid technology and infrastructure stocks.
Furukawa Electric now combines upgraded profit guidance with a share price that has already moved sharply. The business appears stronger on paper, but the key question is whether the current valuation still leaves enough opportunity for new investors.
Preferred P/E Multiple of 32.1x: Is it justified?
Valuation now hinges on whether Furukawa Electric’s current P/E of 32.1x at a share price of ¥4,093 is a fair reflection of expectations or a stretch compared with peers.
The P/E ratio links the price you pay for each share to the earnings that the business generates per share. For a group like Furukawa Electric, operating in optical solutions, power cables and automotive systems, that metric effectively captures how much of the recent earnings growth and forecast profit expansion investors are already pricing in.
Several data points line up in support of a richer multiple. Earnings grew 164.7% over the past year and have risen at an average of 45.8% per year over the past 5 years. Net profit margins are described as improving from 2.8% to 6.5%, and earnings are forecast to grow 19.6% per year, which is faster than the JP market forecast of 9.2% and ahead of the Electrical industry’s 25.2% growth benchmark last year. Furukawa Electric is also characterized as good value against an estimated fair P/E of 38.1x. This suggests the current 32.1x level could be below where the ratio might move if those earnings forecasts play out.
The comparison with peers tells a more demanding story. Management benefits from a high Return on Equity of 20.5% today and forecasts indicate ROE could reach 23.4% in 3 years, yet the stock is described as expensive on a P/E of 32.1x against both the JP Electrical industry average of 13.8x and a peer group average of 25.5x. Those gaps are wide, and they point to a market that is already assigning a premium for forecast growth and profitability that would need to materialize to keep that premium in place.
Explore the SWS fair ratio for Furukawa Electric.
Result: Price-to-Earnings of 32.1x (OVERVALUED)
Still, Furukawa Electric’s premium P/E and reliance on earnings forecasts mean any disappointment on profit delivery or sector sentiment could quickly reset that optimism.
Find out about the key risks to this Furukawa Electric narrative.
Another view on Furukawa Electric’s value
A different lens tells a softer story. Our DCF model points to a fair value of about ¥4,703 per share, which is roughly 13% above Furukawa Electric’s current price of ¥4,093. So while the P/E screens as rich against peers, the cash flow view frames the stock as undervalued.
This clash between an expensive earnings multiple and a discount on DCF keeps the question open. Are investors overpaying for current momentum, or underpaying for long run cash generation potential that the DCF is trying to capture?
Look into how the SWS DCF model arrives at its fair value.
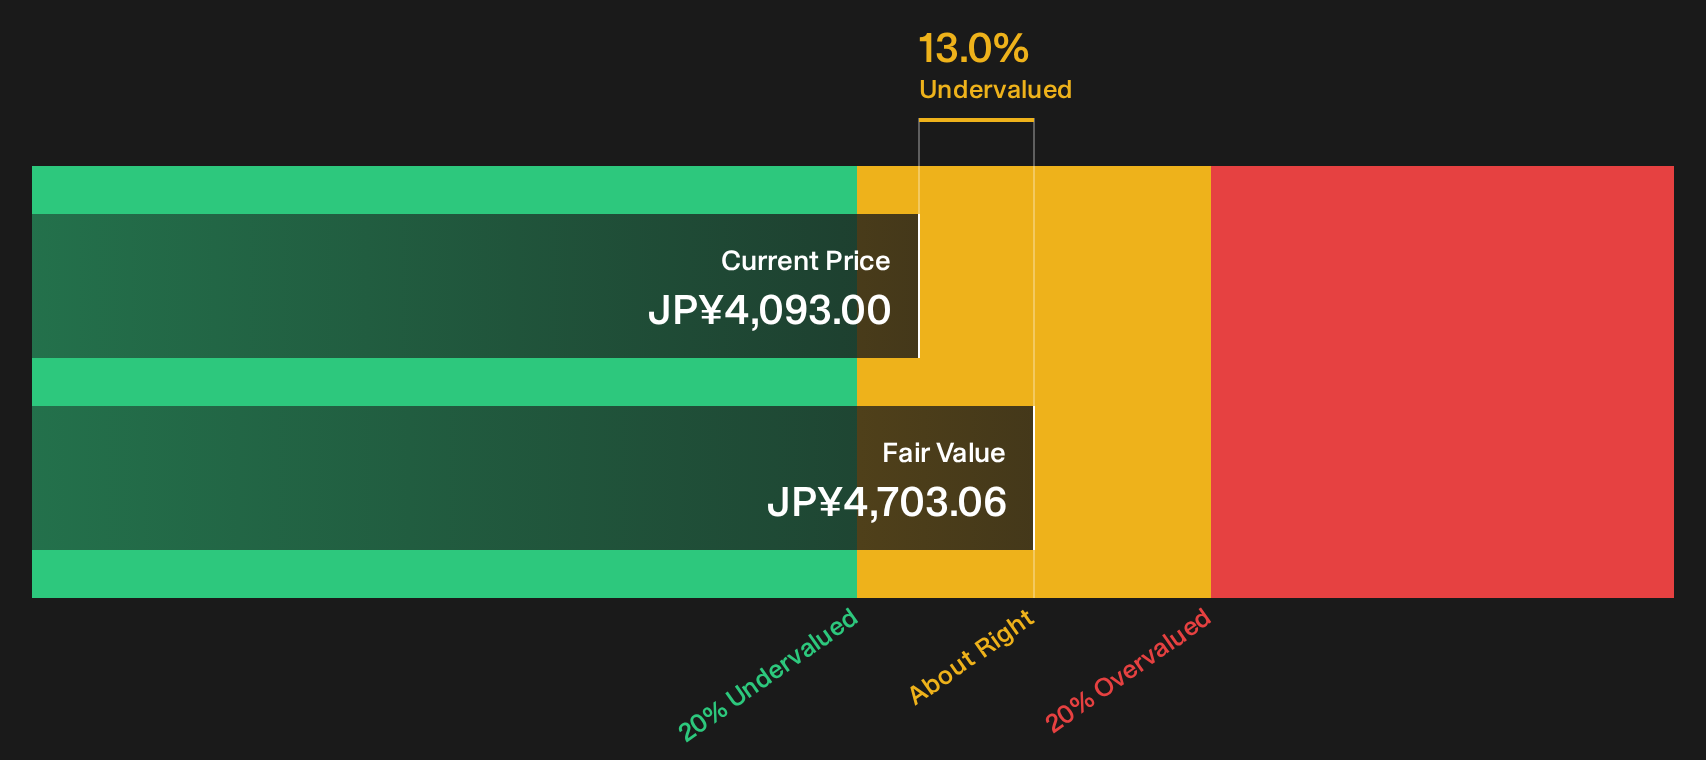
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Furukawa Electric for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With Furukawa Electric pulling in mixed signals on value, hesitation is natural. The data is all there for you to weigh quickly and decide how the risk and reward trade off looks in your own portfolio using the 3 key rewards and 3 important warning signs.
Looking for more Furukawa Electric style ideas?
If Furukawa Electric has sharpened your focus, do not stop here. The next opportunity on your watchlist could already be passing you by.
- Target resilience first by scanning companies with stronger balance sheets and solid fundamentals through our list of solid balance sheet and fundamentals (23 results).
- Spot potential mispricing early and hunt for quality at a discount using the 17 high quality undervalued stocks.
- Secure more dependable income streams by reviewing companies in the 20 dividend fortresses before others turn their attention there.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com