
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 British Undervalued Stocks To Own In October 2026
UK government bond yields recently climbed past 6% on long-term debt, lifting borrowing costs and putting pressure on highly valued shares. Cash rich British businesses with solid inflows but modest share prices suddenly look more interesting. Investors are paying closer attention to what a company earns in actual cash, not just its story. This article highlights three UK listed stocks that screen as underpriced relative to their cash flows.
The three stocks below are only a sample. The broader screen surfaces 9 more companies with similarly appealing cash flow profiles and valuations that are not covered here. If you want to identify and analyze the highest conviction ideas from this cash flow focused universe, head straight to the Undervalued Stocks Based On Cash Flows screener.
LSL Property Services (LSE:LSL)
LSL Property Services runs a capital light, fee driven property services platform in the UK, earning about £110.7 million from Surveying & Valuation, £48.2 million from Financial Services and £26.7 million from Estate Agency, with a market value of roughly £256 million.
LSL Property Services fits this cash flow focused screen because a large slice of its business earns repeat fees from valuation work and related services, which can give investors clearer line of sight on future cash generation.
"Increased lender adoption of data driven valuation and automation is creating a new profit pool for LSL’s automated valuation model. This is expected to add a scalable, high margin revenue line that enhances group operating margin and return on capital employed."
What really matters now is how one less visible pressure shapes the gap between those projected returns and what eventually shows up in cash.
That invisible pressure is exactly what the full narrative for LSL Property Services unpacks, revealing where cash generation could decouple from expectations and where the opportunity might be accelerating the most.

Foresight Group Holdings (LSE:FSG)
Foresight Group Holdings is an asset manager that channels investor money into infrastructure and private equity, with its Real Assets arm generating about £114.8 million of revenue and Private Equity adding £50.1 million, giving the stock a roughly £496 million market value.
For investors hunting businesses where discounted cash flow analysis really matters, Foresight Group Holdings brings a portfolio of renewable energy and infrastructure assets that produce long dated, contract backed income streams, and a management platform built to turn those cash flows into fee revenue.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is expected to contribute to compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
What really shapes the payoff for Foresight Group Holdings investors now is how far one less visible cost and pricing battle squeezes future margins.
That margin squeeze question is exactly what the full narrative for Foresight Group Holdings tackles, mapping where Foresight Group Holdings’ fee engine could quietly accelerate or stall in the future.
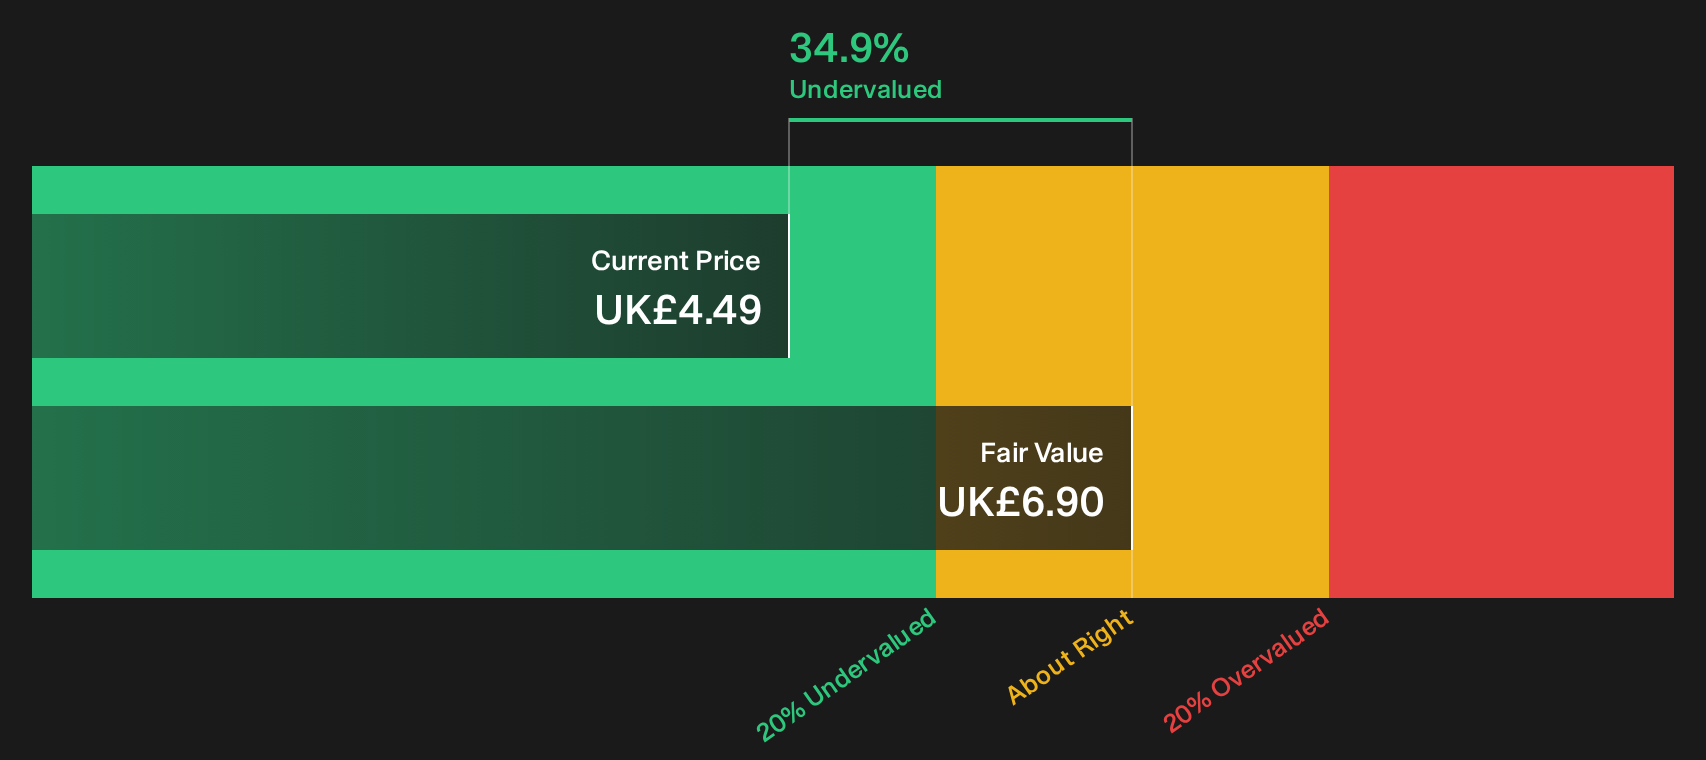
Polar Capital Holdings (AIM:POLR)
Polar Capital Holdings is a London based investment manager that runs equity and balanced funds using fundamental, cash flow focused valuation to hunt for undervalued securities. Its investment management arm generates about £264 million of revenue, and the group carries a market value near £824 million.
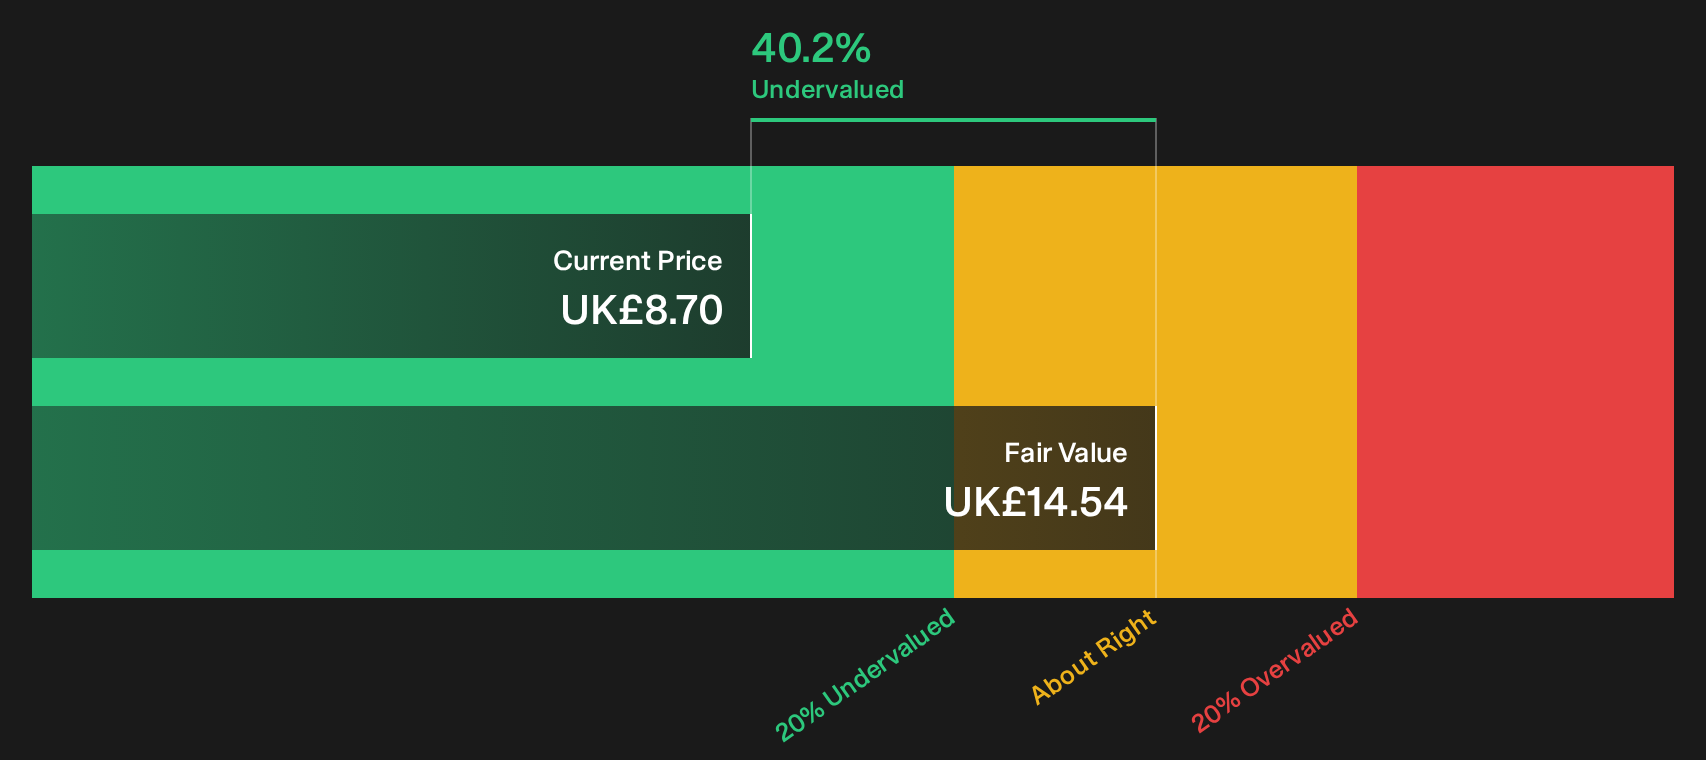
Polar Capital Holdings screens as interesting for cash flow minded investors because earnings grew 66.2% year on year, net margins sit at 22.3% and the shares trade about 40.2% below one fair value estimate, with that gap hinging on how one quiet pressure shapes future fee income and profitability.
That quiet pressure on future fee income is exactly what the analysis report for Polar Capital Holdings unpacks, before earnings quality and valuation potentially decouple in either direction.
Seeking Fresh Alternatives Before Everyone Else
Markets move fast. Breakout ideas can gain momentum while slow research gets caught flat footed, and under the radar for now opportunities start dropping from view. Get in early.
- Spot cash rich businesses that still trade like wallflowers, and scan the curated 5 high quality undiscovered gems before the crowd starts chasing the same tickers.
- Zero in on resilient companies where balance sheets do the heavy lifting, and review the hand picked list of solid balance sheet and fundamentals (9 results) while the data still gives you an edge.
- Ride the infrastructure backbone of the AI boom by checking the focused 90 AI infrastructure stocks while these enablers of computing demand are still under serious price scrutiny.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com