
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
TSX Growth Companies With High Insider Ownership In October 2026
As the Canadian market navigates a landscape marked by resilient equity markets and inflationary pressures, investors are keenly observing how macroeconomic forces like rising interest rates and geopolitical tensions influence market dynamics. In this environment, growth companies with high insider ownership can be particularly appealing, as they often demonstrate strong alignment between management and shareholders, potentially offering stability amidst broader market volatility.
Top 10 Growth Companies With High Insider Ownership In Canada
| Name | Insider Ownership | Earnings Growth |
| ROK Resources (TSXV:ROK) | 16.9% | 130% |
| Propel Holdings (TSX:PRL) | 25.7% | 39.7% |
| Hammond Power Solutions (TSX:HPS.A) | 27.1% | 32% |
| Firan Technology Group (TSX:FTG) | 12.6% | 22% |
| Electrovaya (TSX:ELVA) | 34.9% | 41.2% |
| Cizzle Brands (NEOE:CZZL) | 13.2% | 90.4% |
| CEMATRIX (TSX:CEMX) | 10.7% | 28.9% |
| Cambria Gold Mines (TSXV:CAMB) | 12% | 85.3% |
| Aritzia (TSX:ATZ) | 16.2% | 20.3% |
| Allied Gold (TSX:AAUC) | 15.4% | 39.4% |
Underneath we present a selection of stocks filtered out by our screen.
Electrovaya (TSX:ELVA)
Simply Wall St Growth Rating: ★★★★★★
Overview: Electrovaya Inc. designs, develops, manufactures, and sells lithium-ion batteries and related products for energy storage and clean electric transportation in North America, with a market cap of CA$449.49 million.
Operations: The company generates revenue of $71.82 million from developing, manufacturing, and marketing power technology products, including lithium-ion batteries and battery management systems for energy storage and clean electric transportation in North America.
Insider Ownership: 34.9%
Electrovaya is experiencing significant growth with earnings forecast to rise 41.22% annually, outpacing the Canadian market. Despite recent insider selling, more shares have been bought than sold in the past three months. The company’s revenue growth projection of 29.9% per year surpasses both market averages and high-growth thresholds. Recent developments include its addition to the S&P Global BMI Index and a commercial agreement with Amazon, enhancing its strategic positioning in energy storage solutions.
- Click here to discover the nuances of Electrovaya with our detailed analytical future growth report.
- The valuation report we've compiled suggests that Electrovaya's current price could be inflated.
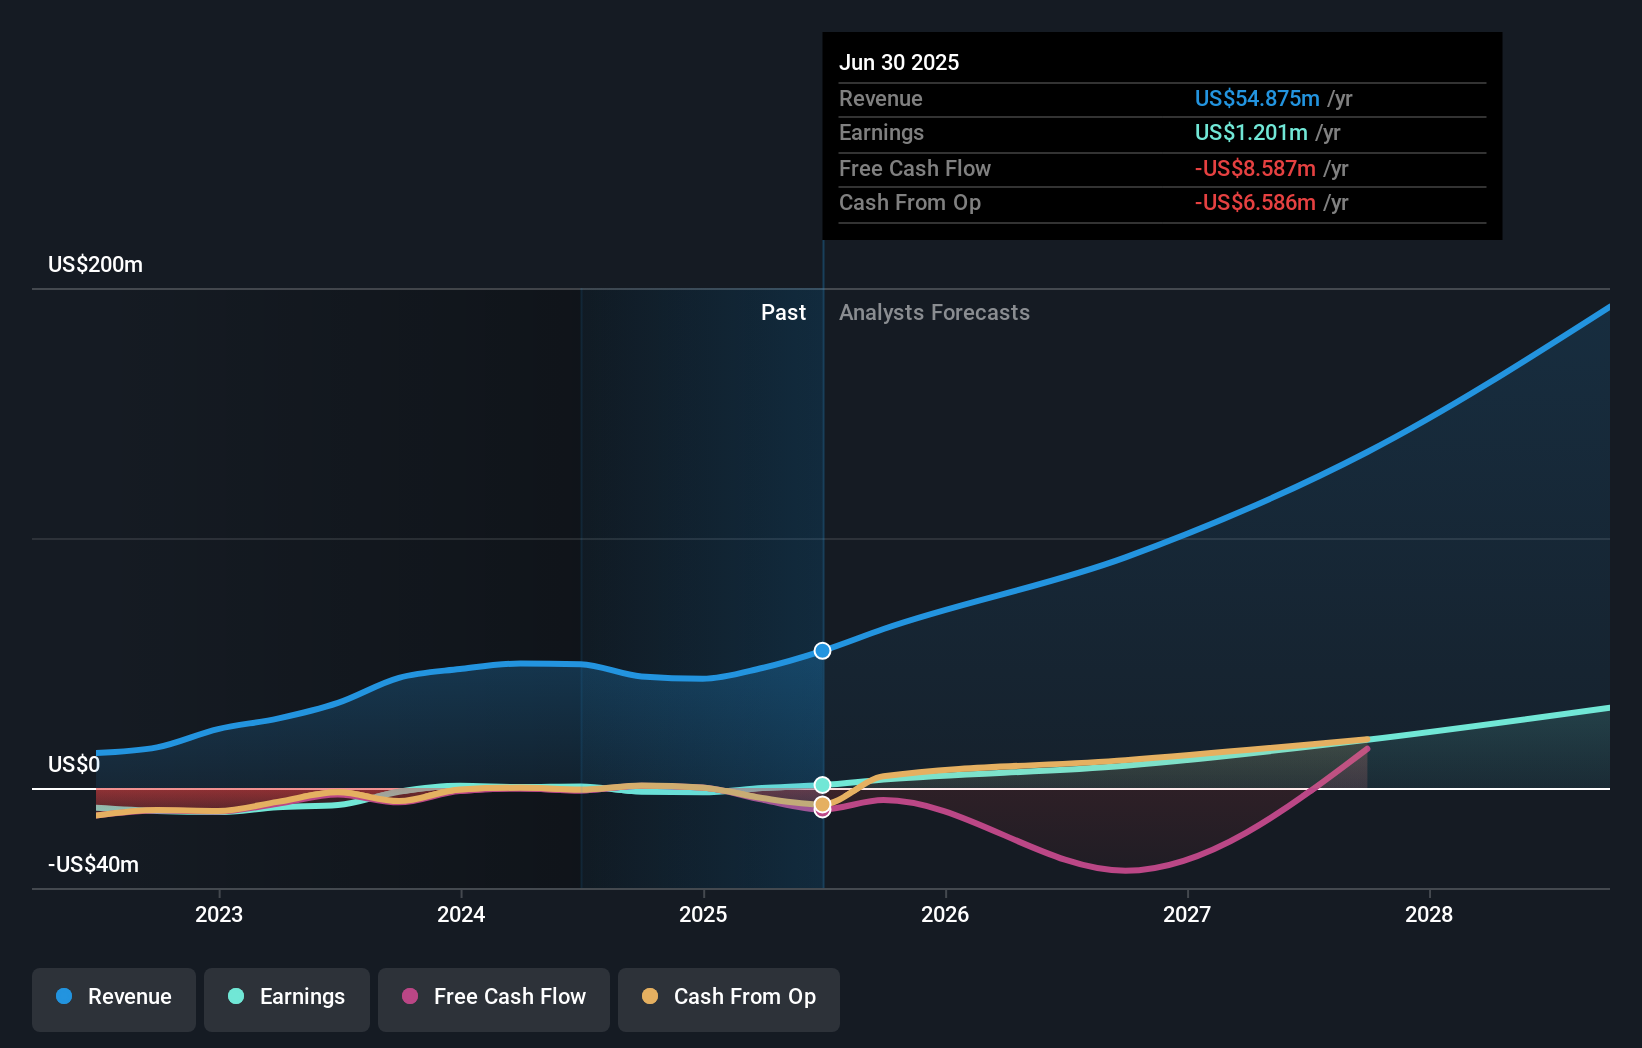
New Found Gold (TSX:NFGC)
Simply Wall St Growth Rating: ★★★★★☆
Overview: New Found Gold Corp. is a mineral exploration company focused on identifying, evaluating, acquiring, and exploring mineral properties in Newfoundland and Labrador, Canada, with a market cap of CA$916.84 million.
Operations: New Found Gold Corp. does not currently have any revenue-generating segments as it is primarily engaged in the exploration and evaluation of mineral properties in Newfoundland and Labrador, Canada.
Insider Ownership: 12.2%
New Found Gold is experiencing robust growth, with revenue projected to increase by 66.1% annually, surpassing market averages. The company recently declared commercial production at its Hammerdown Gold Mine, which could enhance its operational capacity and financial performance. Despite past shareholder dilution, the stock is expected to rise significantly according to analyst consensus. Recent additions to major indices like the S&P/TSX Global Mining Index further underscore its growing industry presence in Canada.
- Dive into the specifics of New Found Gold here with our thorough growth forecast report.
- Our valuation report unveils the possibility New Found Gold's shares may be trading at a premium.
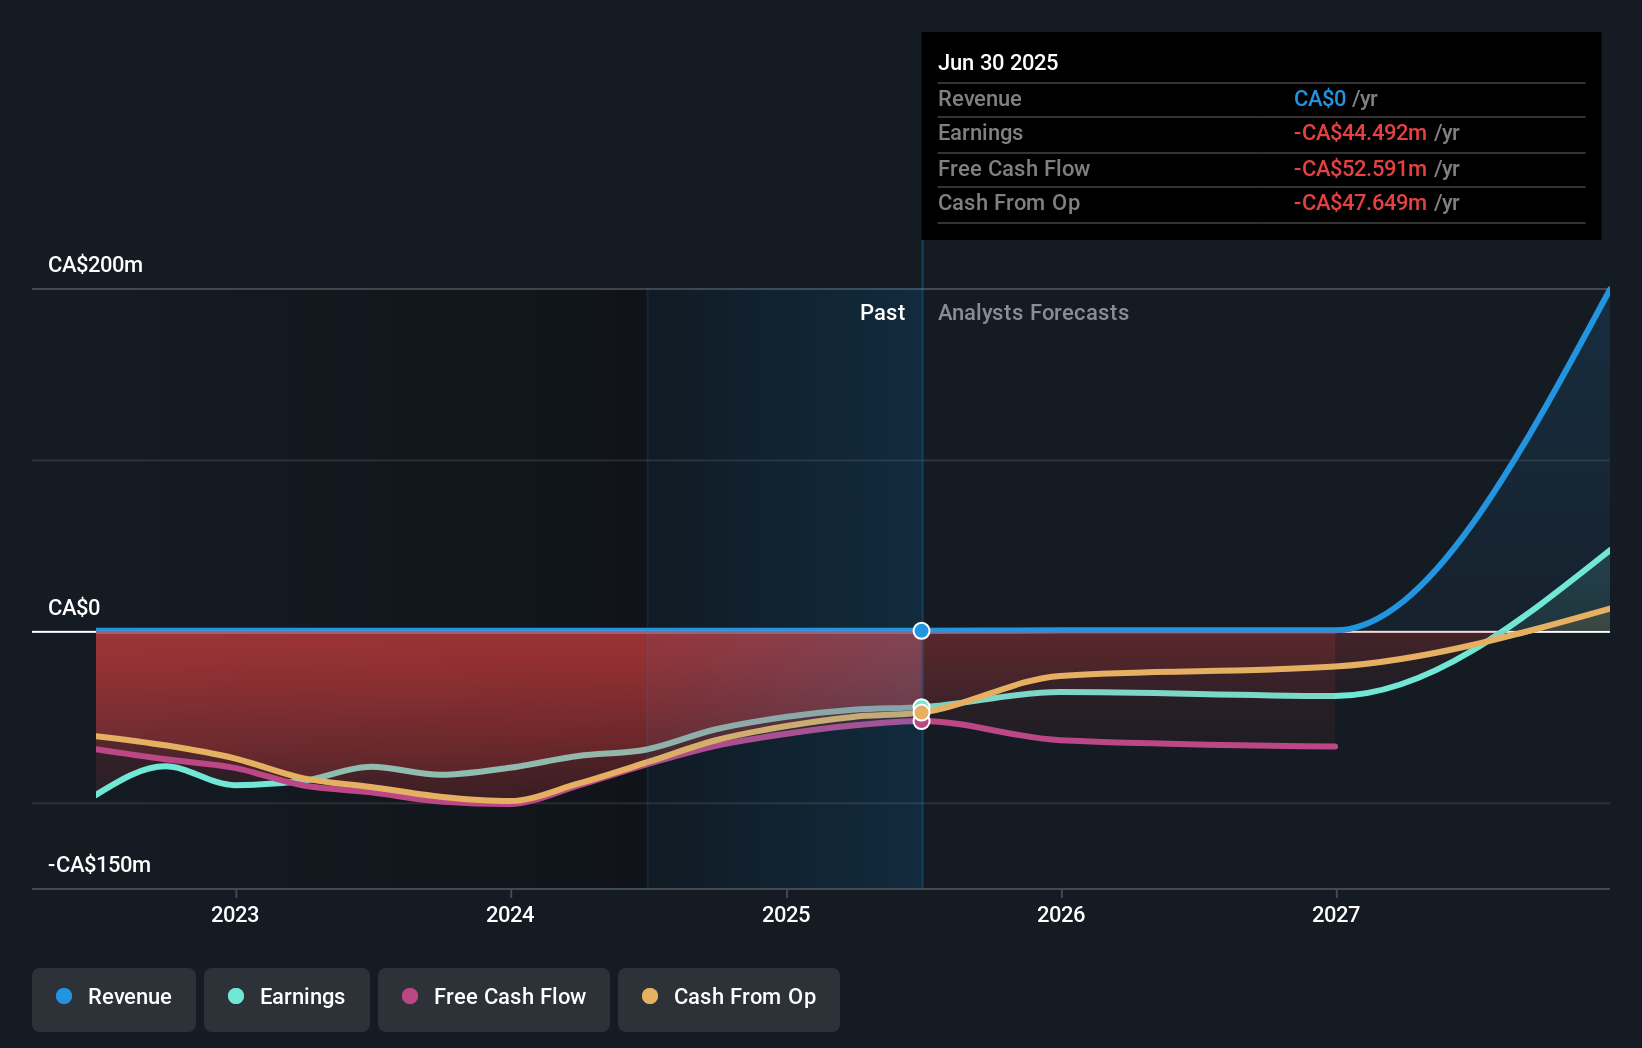
Logan Energy (TSXV:LGN)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Logan Energy Corp. is involved in the exploration, development, and production of crude oil and natural gas properties with a market cap of CA$781.53 million.
Operations: The company generates revenue of CA$212.20 million from its oil and gas exploration and production activities.
Insider Ownership: 15.9%
Logan Energy shows strong growth potential, with revenue projected to rise by 42.2% annually, outpacing the Canadian market. Recent earnings highlight significant improvements, with second-quarter revenue reaching C$76.65 million compared to C$40.51 million a year ago and net income increasing to C$28.36 million from C$17.31 million. Despite past shareholder dilution, analyst consensus suggests a 24.1% stock price increase, supported by robust production forecasts and high insider ownership stability over the last three months.
- Unlock comprehensive insights into our analysis of Logan Energy stock in this growth report.
- The analysis detailed in our Logan Energy valuation report hints at an inflated share price compared to its estimated value.

Taking Advantage
- Discover the full array of 49 Fast Growing TSX Companies With High Insider Ownership right here.
- Ready For A Different Approach? These 26 companies survived and thrived after COVID and have the right ingredients to survive Trump's tariffs. Discover why before your portfolio feels the trade war pinch.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com