
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Itoham Yonekyu Holdings (TSE:2296) Has Investors Asking A Bigger Question
Itoham Yonekyu Holdings (TSE:2296) has been removed from the FTSE All-World Index, shortly after announcing a reshuffle of senior executives, including the resignation of Managing Executive Officer and Chief Marketing Officer Yuko Nakajima.
These index and leadership changes come after a weaker period for Itoham Yonekyu Holdings, with the share price down 14.17% year to date and the 1-year total shareholder return declining 9.40%. However, the 3-year and 5-year total shareholder returns of 40.19% and 65.93% indicate a much stronger longer-term performance.
Compare Itoham Yonekyu Holdings with a hand picked 17 high quality undervalued stocks that may also be reacting to index changes and leadership reshuffles.
After a sharp year to date pullback and a fresh exit from the FTSE All-World Index, the key tension around Itoham Yonekyu Holdings now is simple: Is most of the upside already harvested, or still in front of the stock as valuations reset?
Price-to-Earnings of 13.8x: Is it justified for Itoham Yonekyu Holdings?
At a last close of ¥4,875, Itoham Yonekyu Holdings trades on a P/E of 13.8x, which points to a cheaper entry point compared with its listed peers and the broader Japanese food sector.
The P/E ratio compares what investors pay today for each unit of current earnings and is especially useful for a mature, cash-generative food producer like Itoham Yonekyu Holdings. With earnings described as high quality and a current net profit margin of 1.9% versus 1.6% last year, the current multiple reflects a business that is profitable yet priced with some restraint.
Context comes from the reference points. The stock changes hands at a discount to the JP Food industry average P/E of 16.3x and also sits below the peer group average of 26.2x. The estimated fair P/E of 15.9x is higher than where the shares currently trade.
Explore the SWS fair ratio for Itoham Yonekyu Holdings.
Result: Price-to-Earnings of 13.8x
Still, Itoham Yonekyu Holdings faces real pressure if executive reshuffles disrupt operations or if its modest 2.0% revenue growth and 0.3% net income growth fail to support sentiment.
Find out about the key risks to this Itoham Yonekyu Holdings narrative.
Another View on Itoham Yonekyu Holdings’ Value
While the 13.8x P/E suggests Itoham Yonekyu Holdings is modestly priced, the SWS DCF model presents a slightly different picture. On that basis, the shares at ¥4,875 sit just under an estimated future cash flow value of ¥4,925, which frames the stock as only marginally undervalued. That leaves a key question for you: Is a small discount enough compensation for earnings that are forecast to grow slowly?
Look into how the SWS DCF model arrives at its fair value.
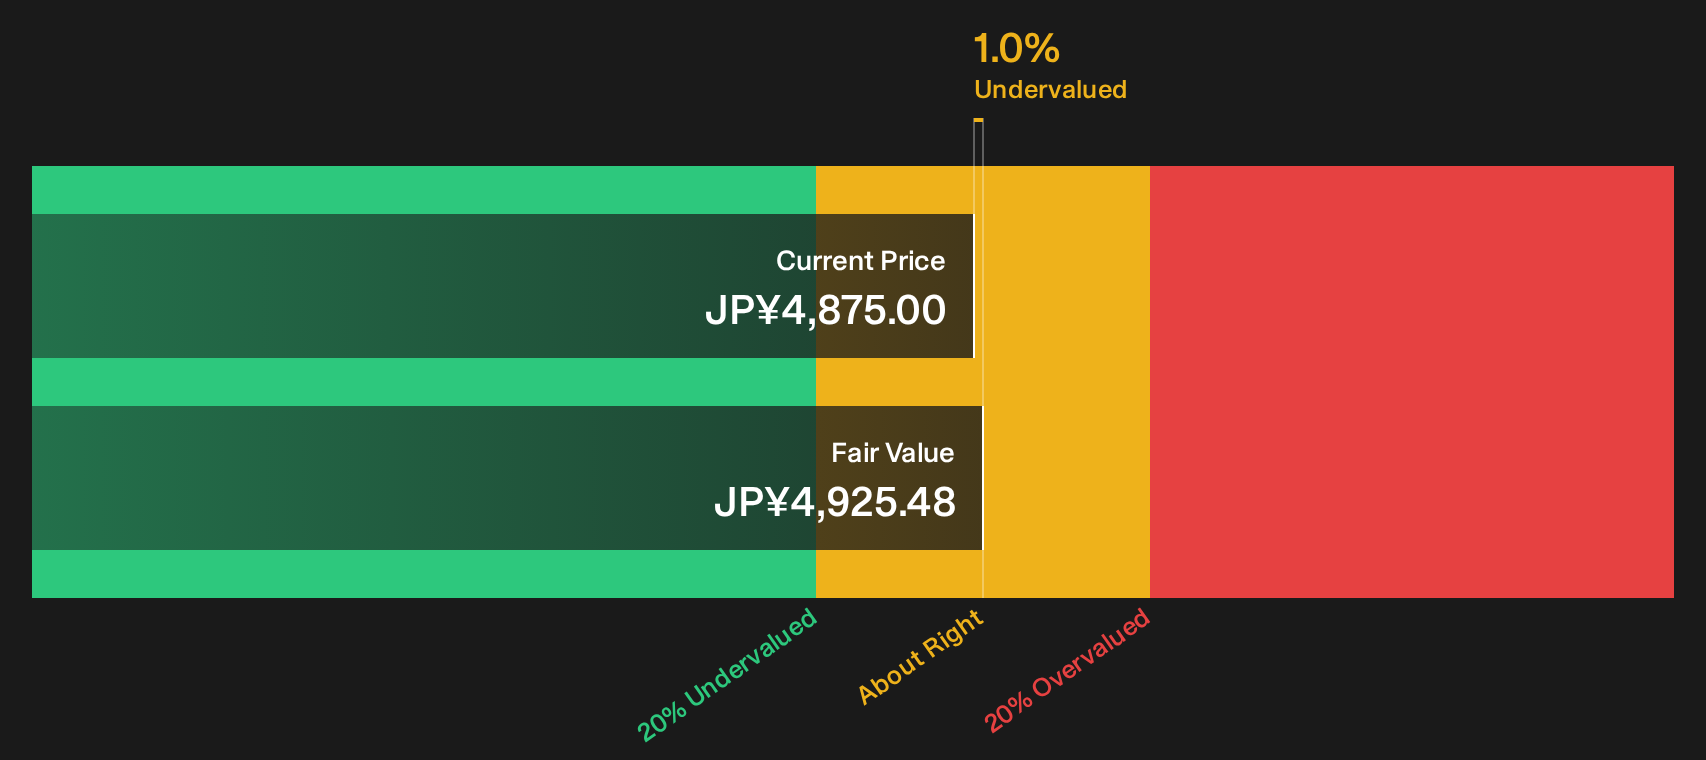
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Itoham Yonekyu Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Itoham Yonekyu Holdings can be confusing, so move fast, review the full data set and decide where you stand. To help weigh both the concerns and the upside case in one place, take a moment to review the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Itoham Yonekyu Holdings?
If you stop with Itoham Yonekyu Holdings, you only see one angle. Cast the net wider with focused screeners and give yourself more options.
- Target potential mispricings by scanning a curated pool of quality candidates through the 17 high quality undervalued stocks.
- Build steadier income potential by zeroing in on companies that feature the 20 dividend fortresses.
- Prioritise resilience by filtering for financially robust businesses using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com