
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Johnson & Johnson (JNJ) Stock Could Be Undervalued On Future Cash Flow
Johnson & Johnson has been on a strong multi‑year run, and that kind of share price climb naturally raises a question about whether the current valuation still lines up with the cash the business can generate. With a full Discounted Cash Flow (DCF) view available, the focus turns to what the company’s cash flows imply about where the stock trades today.
- Over the past 5 years the stock has delivered a total return of about 90.4%, which puts real weight on whether the underlying cash flows support that kind of compounding.
- Recent clinical results for TECVAYLI plus DARZALEX FASPRO and TREMFYA, along with progress in cell therapy and gene therapy, can influence expectations for future cash generation, the timing of those inflows, and the investment needed to support them.
- Prefer to judge Johnson & Johnson on earnings? See why Johnson & Johnson's 30.3x P/E tells a different valuation story.
The issue now is whether Johnson & Johnson’s current share price is well supported by the cash flows implied in its intrinsic value estimate from the Discounted Cash Flow (DCF) model.
If you are curious whether other healthcare stocks line up with the same kind of cash flow test you are applying to Johnson & Johnson, and want a pre-filtered set to review, take a look at 36 healthcare AI stocks.
Is Johnson & Johnson a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) approach here takes Johnson & Johnson’s latest twelve-month free cash flow of about $21.7b and projects it forward in two stages. Analysts and model estimates together point to growing free cash flow over the coming decade, with projected annual figures in the $27b to $43b range in dollar terms before discounting.
The DCF projections put Johnson & Johnson's estimated intrinsic value above the current share price of $264.74. New model-based analysis for TECVAYLI plus DARZALEX FASPRO, which points to stronger treatment outcomes in early-line multiple myeloma, helps explain why the cash flow outlook in the model assumes ongoing growth in the pharmaceutical pipeline. You can see the full set of inputs, assumptions and the resulting value gap in the detailed model view. Find out what Johnson & Johnson could be worth using our Discounted Cash Flow (DCF) estimate.
The Johnson & Johnson Narrative: What Would Justify Today's Price?
Narratives on Johnson & Johnson’s Community page pick up exactly where the DCF puzzle leaves off, by spelling out which paths for growth, margins and earnings would need to play out for the shares to be worth materially more or materially less than today’s price. Each scenario ties a fair value estimate to a specific mix of potential catalysts and risks so you can track over time which version of events seems to be unfolding.
Community views on Johnson & Johnson split between those who see more upside in the pipeline and MedTech buildout and those who think the current price already reflects that strength.
Bull case: roughly fairly valued
"The company's substantial investment of over $55 billion into manufacturing, R&D, and technology in the U.S. over the next four years is projected to expand capacity for advanced medicines and devices..."
Discover why this Narrative puts Johnson & Johnson at roughly fairly valued.
Bear case: 7% overvalued
"At ~22× earnings, JNJ trades near sector averages but commands a modest premium for stability, balance sheet strength, and consistent free cash flow..."
Explore why this Narrative puts Johnson & Johnson at 7% overvalued.
One more Johnson & Johnson signal worth checking before you move on
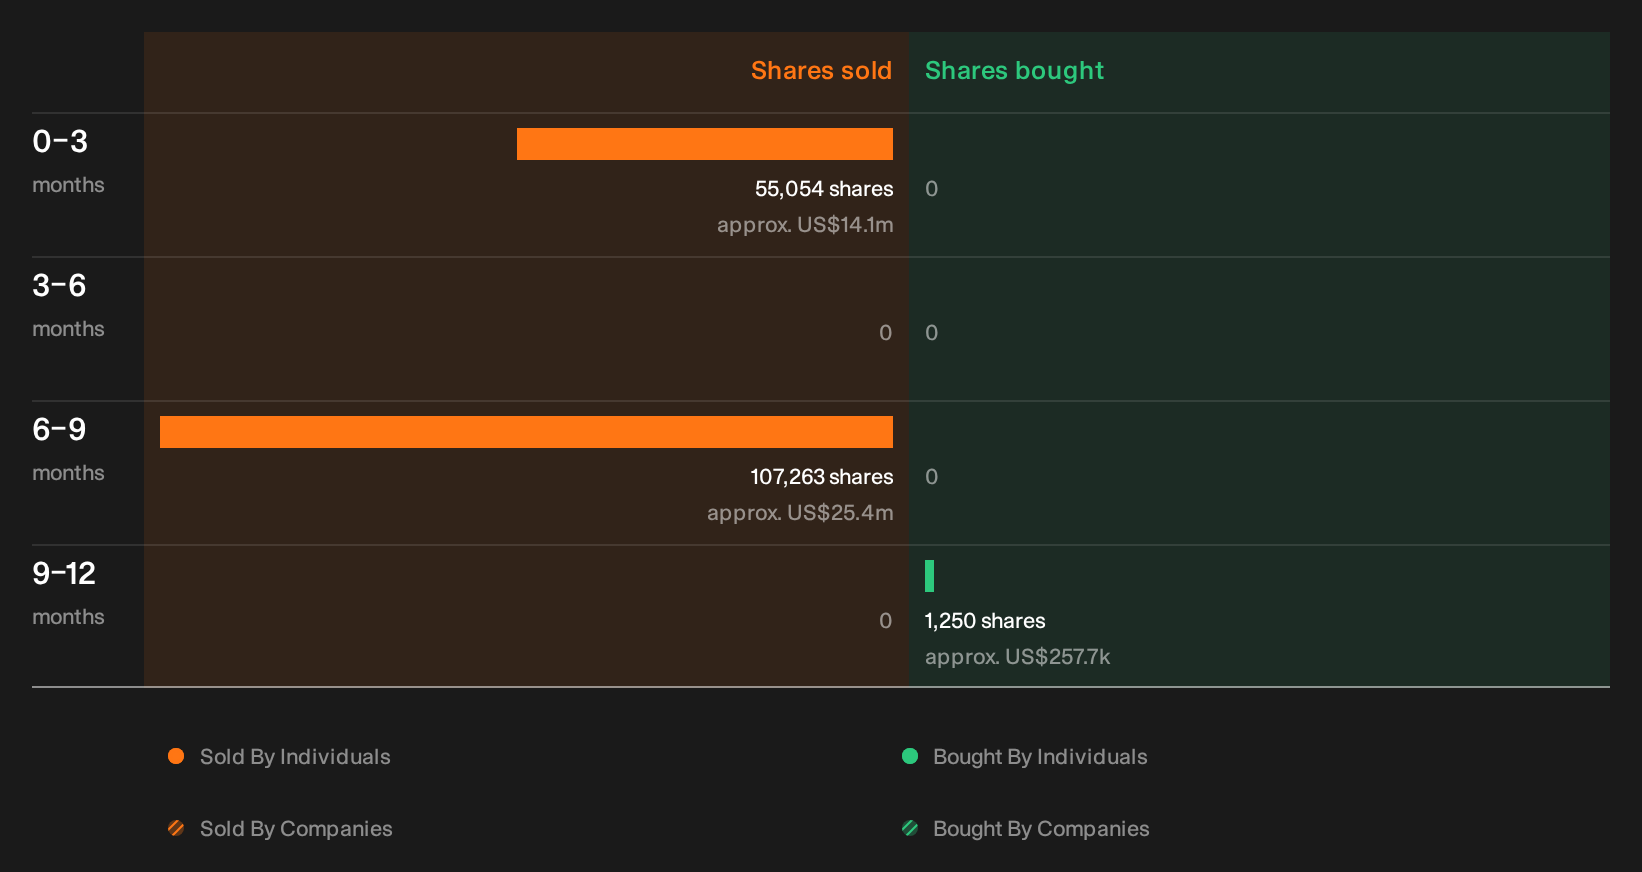
Cash flows tell one story, but recent insider share sales are a separate clue about how people inside Johnson & Johnson are acting, including who sold, how much, and what that might mean for you to interpret. See the recent insider selling flagged for Johnson & Johnson.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com