
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Global Undervalued Small Caps With Insider Buying In October 2026
As global markets navigate a landscape marked by inflation concerns and fluctuating bond yields, small-cap stocks have faced headwinds, with the Russell 2000 Index experiencing a pullback. Despite these challenges, the acceleration in U.S. business activity and positive economic indicators in Europe suggest potential opportunities for investors seeking undervalued assets with growth potential. In this environment, identifying small-cap companies that demonstrate resilience through insider buying can be indicative of strong fundamentals and confidence from those closest to the business operations.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Q Technology (Group) | 3.5x | 0.2x | 43.23% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 7.1x | 0.9x | 37.35% | ★★★★★☆ |
| Transcontinental | 2.5x | 0.2x | -99.17% | ★★★★☆☆ |
| Nexus Industrial REIT | 10.1x | 3.0x | 8.80% | ★★★★☆☆ |
| Franchise Brands | 27.7x | 2.0x | 46.87% | ★★★★☆☆ |
| Yellow Pages | 8.3x | 0.8x | 28.97% | ★★★☆☆☆ |
| Diversified Royalty | 25.4x | 10.1x | 46.30% | ★★★☆☆☆ |
| ATS | 52.9x | 0.9x | 34.11% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -222.10% | ★★★☆☆☆ |
| Coveo Solutions | NA | 1.9x | -23.48% | ★★★☆☆☆ |
Here we highlight a subset of our preferred stocks from the screener.
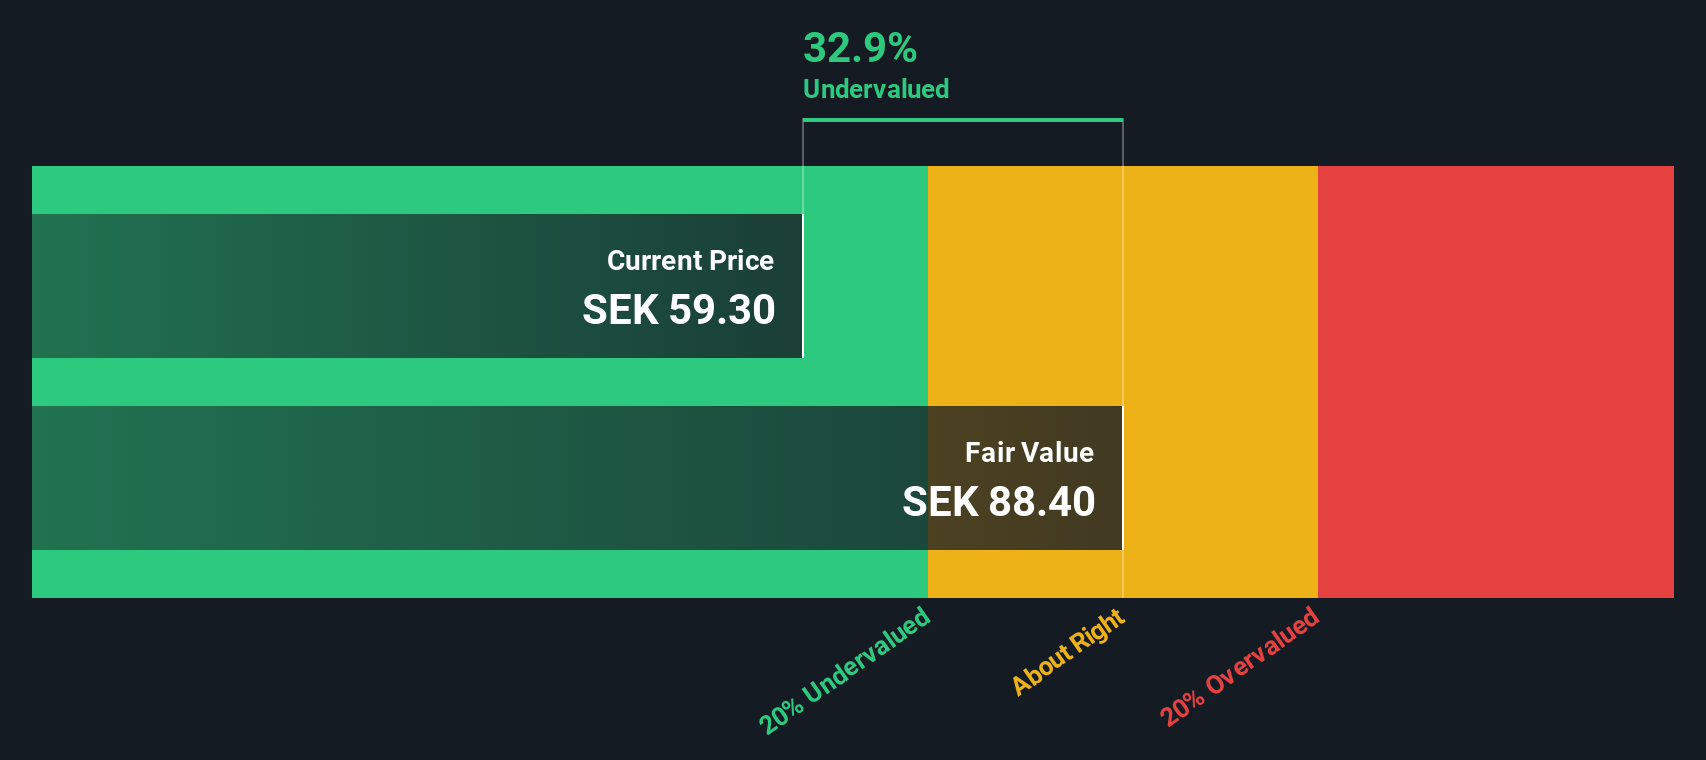
Nolato (OM:NOLA B)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Nolato is a Swedish company specializing in developing and manufacturing polymer product systems for medical, automotive, and consumer electronics industries, with a market cap of approximately SEK 12.34 billion.
Operations: Medical Solutions and Engineered Solutions contribute significantly to revenue, with Medical Solutions generating SEK 5.36 billion and Engineered Solutions SEK 4.09 billion. The company faces substantial costs of goods sold, impacting its net income margin, which was recorded at 8.24% in the most recent quarter. Gross profit margin has shown an upward trend, reaching 18.08% in the latest period from a lower point of 13.25% earlier on.
PE: 20.5x
Nolato, a smaller company in its sector, recently reported second-quarter sales of SEK 2.45 billion, slightly up from last year. However, net income dipped to SEK 169 million from SEK 212 million previously. Despite this, insider confidence is evident with recent share purchases. The company relies entirely on external borrowing for funding but anticipates earnings growth of 15% annually. This mix of challenges and potential makes it an intriguing prospect for those eyeing smaller companies with growth potential.
- Click here to discover the nuances of Nolato with our detailed analytical valuation report.
Examine Nolato's past performance report to understand how it has performed in the past.
Sagicor Financial (TSX:SFC)
Simply Wall St Value Rating: ★★★★☆☆
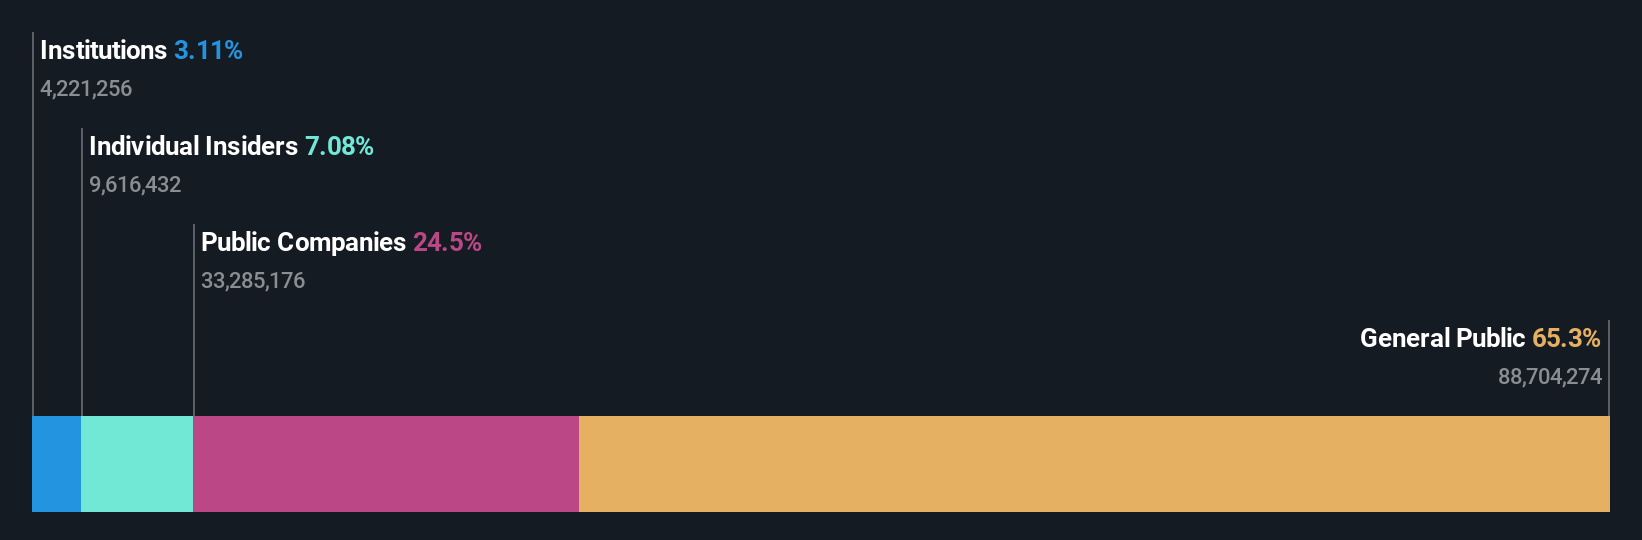
Overview: Sagicor Financial is a financial services company operating in life insurance, banking, and investment sectors across various regions including Canada, the USA, and Jamaica with a market capitalization of $1.16 billion.
Operations: Sagicor Financial generates revenue primarily from its operations in Canada, Jamaica, and the USA. The company has seen fluctuations in its gross profit margin, with recent figures reaching 70.33% as of June 2025. Operating expenses and non-operating expenses significantly impact net income results across periods.
PE: 6.7x
Sagicor Financial's recent CAD 350 million debt financing, with BBB ratings from major agencies, underscores its strategic focus on managing external borrowing. Despite lacking customer deposits and relying on riskier funding sources, the company reported a significant net income turnaround in Q2 2026 to US$86.65 million from a loss last year. Insider confidence is evident as they increased their holdings earlier this year. With earnings projected to grow annually by 11.21%, Sagicor presents intriguing growth potential amidst its financial restructuring efforts.
- Navigate through the intricacies of Sagicor Financial with our comprehensive valuation report here.
Assess Sagicor Financial's past performance with our detailed historical performance reports.
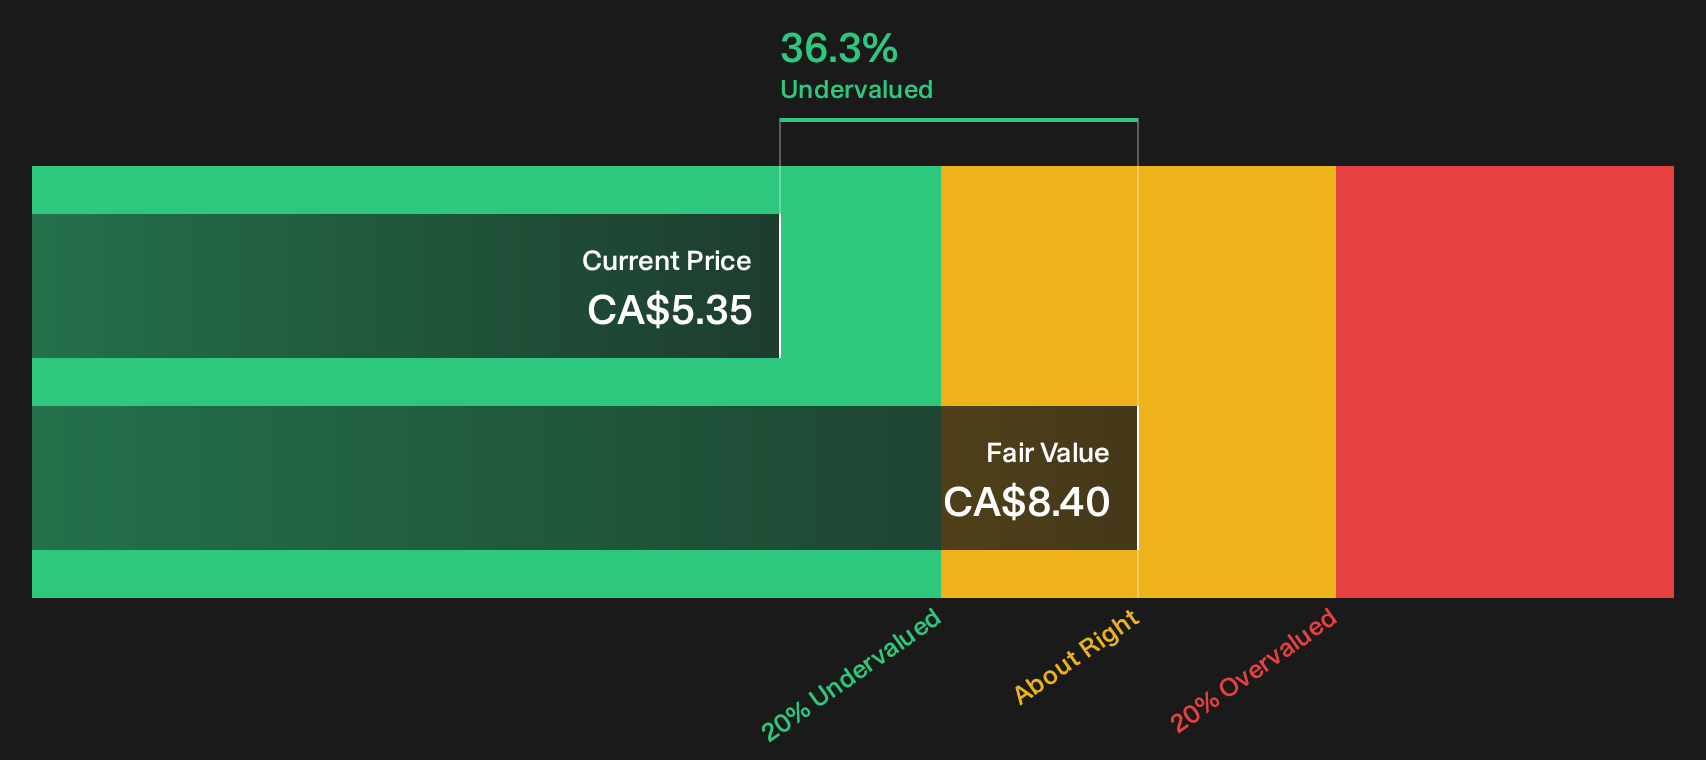
Timbercreek Financial (TSX:TF)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Timbercreek Financial is a Canadian company specializing in providing mortgage investment solutions, with a focus on financial services related to mortgages, and it has a market cap of approximately CA$ 0.74 billion.
Operations: The company primarily generates revenue through its financial services, specifically in the mortgage sector. Over recent periods, the gross profit margin has shown a declining trend, dropping to 90.65% by September 2025 from earlier higher levels. Operating expenses have consistently been a significant part of costs, with general and administrative expenses being notable contributors.
PE: 17.1x
Timbercreek Financial, a smaller company in the financial sector, is currently facing challenges with its net income declining to CAD 7.81 million in Q2 2026 from CAD 12.37 million the previous year. Despite this, earnings are projected to grow at nearly 39% annually. The company maintains a steady monthly dividend of CAD 0.0575 per share, underscoring its commitment to shareholder returns amidst financial turbulence and reliance on external borrowing for funding without customer deposits as a buffer.
Taking Advantage
- Get an in-depth perspective on all 114 Undervalued Global Small Caps With Insider Buying by using our screener here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Interested In Other Possibilities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com