
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Exploring 3 Undiscovered Gems in Global Markets
In recent weeks, global markets have been navigating a complex landscape of inflation concerns and fluctuating interest rates, with the S&P 500 showing resilience amid these challenges while small-cap indices like the Russell 2000 experienced some pullback. As investors seek opportunities in this dynamic environment, identifying stocks that demonstrate strong fundamentals and growth potential can be particularly rewarding.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| C-Rad | NA | 13.57% | 13.83% | ★★★★★★ |
| Fourth Milling | NA | 12.93% | 16.76% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Aqualis | 33.30% | 22.28% | -18.13% | ★★★☆☆☆ |
Underneath we present a selection of stocks filtered out by our screen.
SeAH Holdings (KOSE:A058650)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: SeAH Holdings Corporation, with a market cap of ₩542.58 billion, operates in the steel materials industry both domestically in South Korea and internationally through its subsidiaries.
Operations: SeAH Holdings generates revenue primarily from its subsidiaries operating in the steel materials sector across domestic and international markets. The company's financial performance is influenced by its cost structure, which includes raw material expenses and operational costs. Notably, it reported a net profit margin of 3.5% in the latest financial period, reflecting its profitability after accounting for all expenses.
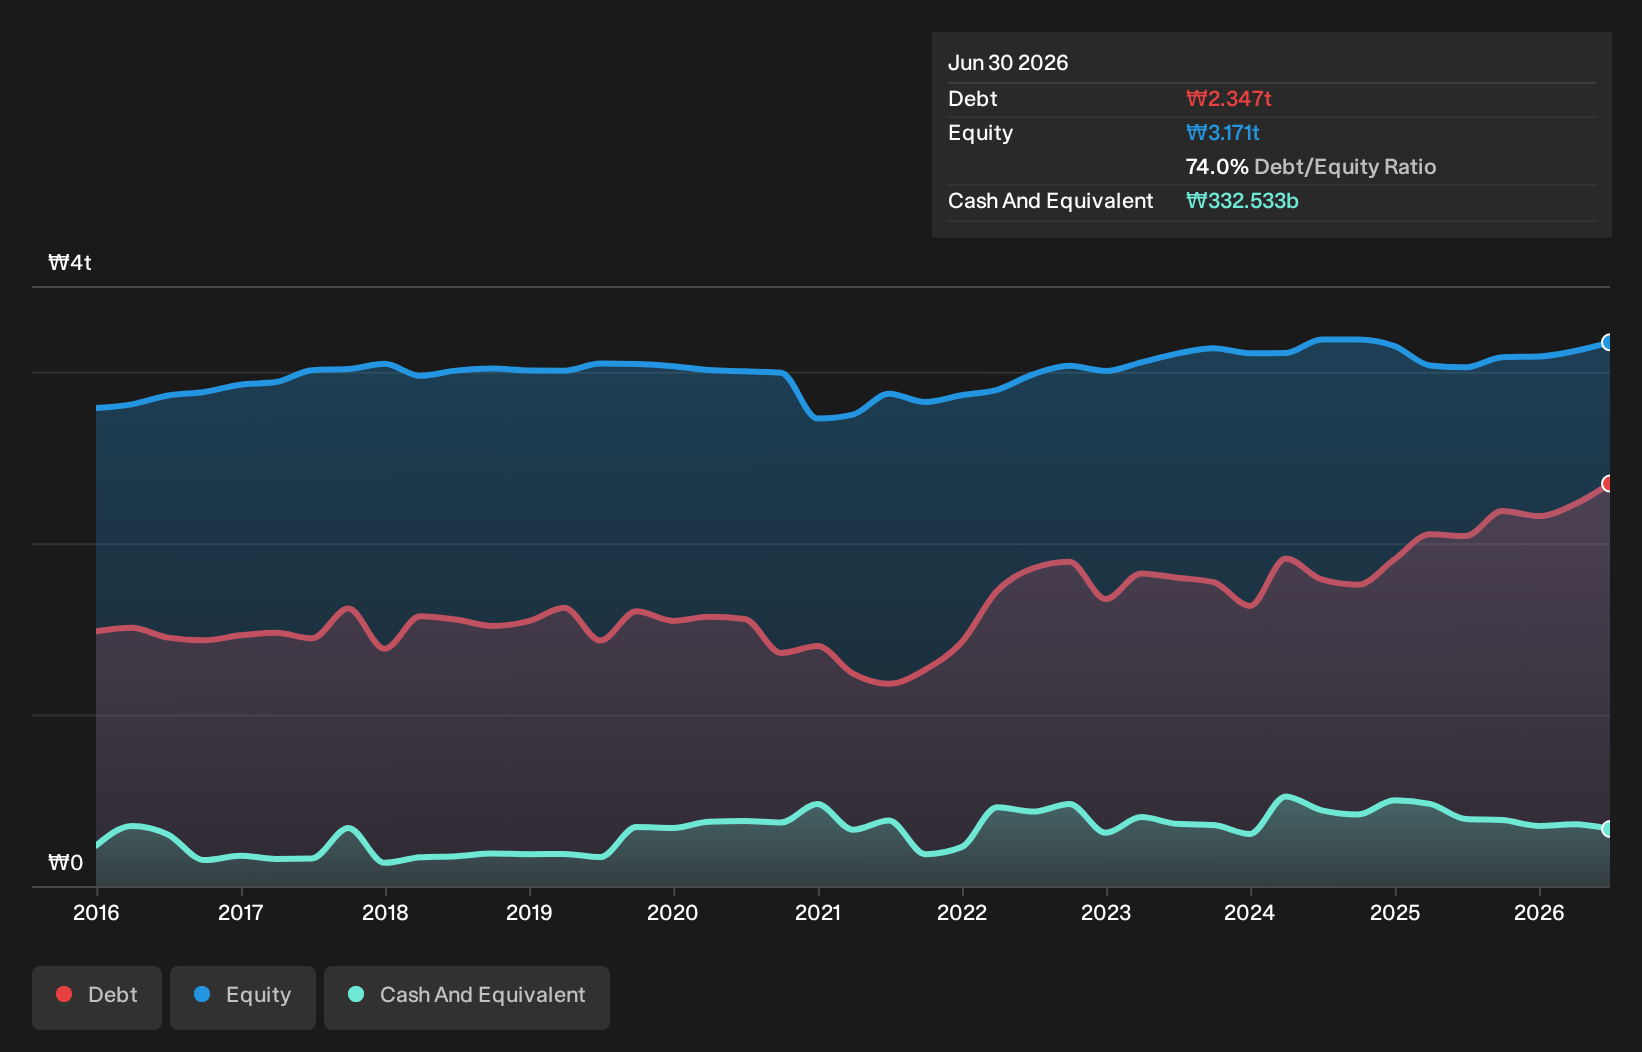
SeAH Holdings, a small-cap entity, shows promise with its earnings skyrocketing by 578.3% over the past year, outpacing the Metals and Mining industry's 18.5%. Its net income for Q2 2026 was KRW 51.72 billion compared to KRW 19.13 billion a year prior, signaling robust growth despite a high debt-to-equity ratio of 74%. Trading at about 69% below estimated fair value indicates potential undervaluation. The recent Airbus deal by SeAH Aerospace & Defense highlights strategic expansion in aerospace materials, positioning it as a key supplier in Asia-Pacific's aviation sector while maintaining high-quality earnings standards.
Zhongjin GoldLtd (SHSE:600489)
Simply Wall St Value Rating: ★★★★★★
Overview: Zhongjin Gold Corp., Ltd, along with its subsidiaries, is involved in the exploration, mining, beneficiation, and smelting of gold and other non-ferrous metals in China and has a market capitalization of approximately CN¥106.16 billion.
Operations: Zhongjin Gold generates revenue primarily through the exploration, mining, beneficiation, and smelting of gold and other non-ferrous metals. The company reported a net profit margin of 5.8% in its latest financial period.
Zhongjin Gold Ltd. has shown impressive financial performance, with earnings growing by 52% over the past year and net income reaching CNY 4.36 billion for the first half of 2026, compared to CNY 2.69 billion a year ago. The company's debt to equity ratio has improved from 60.1% to a satisfactory level of 53.4% over five years, indicating prudent financial management. Trading at a significant discount of approximately 66% below its fair value estimate, Zhongjin Gold appears undervalued relative to peers in the industry, suggesting potential for future appreciation as earnings are forecasted to grow annually by nearly 24%.
- Dive into the specifics of Zhongjin GoldLtd here with our thorough health report.
Examine Zhongjin GoldLtd's past performance report to understand how it has performed in the past.

Nan Pao Resins Chemical (TWSE:4766)
Simply Wall St Value Rating: ★★★★★☆
Overview: Nan Pao Resins Chemical Co., Ltd. is involved in the manufacturing, wholesale, and retail sale of synthetic resins and plastics, adhesives, resin coatings, dyes, and pigments across various global markets with a market capitalization of NT$41.05 billion.
Operations: Nan Pao generates revenue primarily from Taiwan (NT$9.18 billion), Mainland China (NT$7.46 billion), and Vietnam (NT$7.33 billion). The company also sees significant sales in Australia, contributing NT$3.78 billion to its revenue stream.
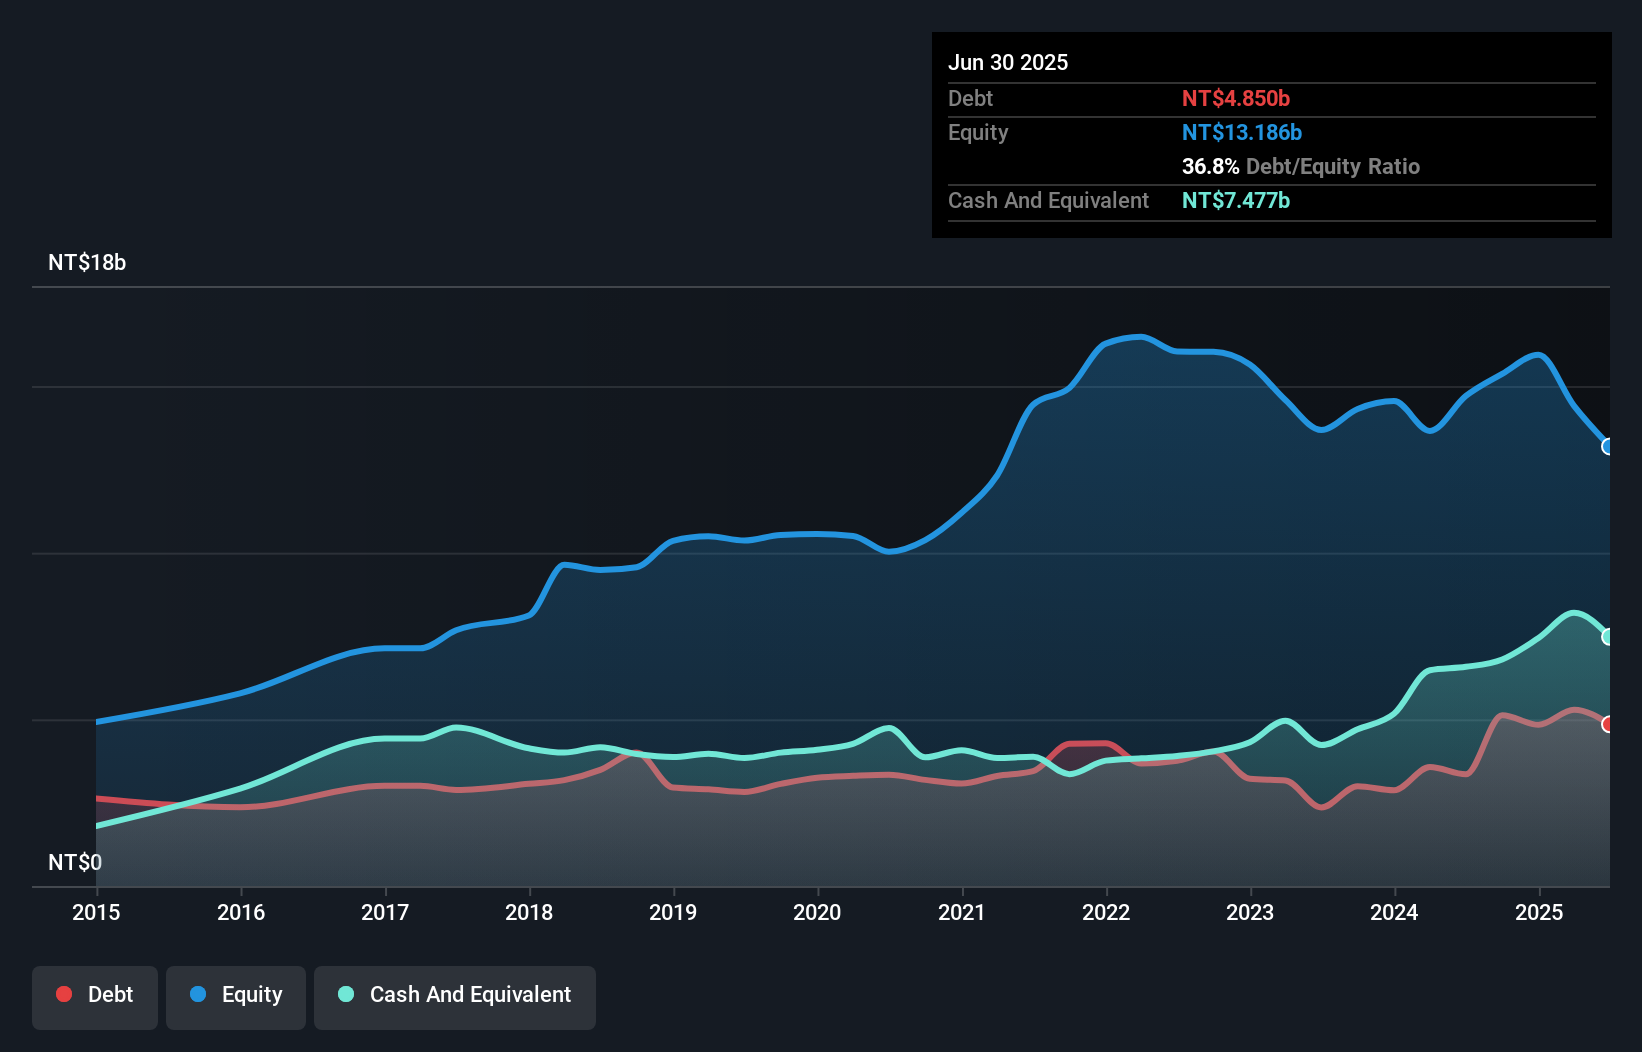
Nan Pao Resins Chemical, a promising player in the chemicals sector, has shown robust financial performance with earnings growing 17.6% annually over the past five years. Despite trading at 48% below its estimated fair value, it boasts high-quality earnings and is free cash flow positive. However, its debt to equity ratio has increased from 23.9% to 37.2%, which might raise some eyebrows regarding financial leverage management. Recent results highlight impressive growth; second-quarter sales reached TWD 6.58 billion compared to TWD 5.81 billion last year, while net income jumped from TWD 553 million to TWD 877 million within the same period.
- Navigate through the intricacies of Nan Pao Resins Chemical with our comprehensive health report here.
Evaluate Nan Pao Resins Chemical's historical performance by accessing our past performance report.
Where To Now?
- Click through to start exploring the rest of the 158 Global Undiscovered Gems With Strong Fundamentals now.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com