
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why BWP Trust (ASX:BWP) Is Getting Attention Today
The Reserve Bank of Australia’s cash rate move to 4.6%, alongside talk of further tightening, has pushed income-focused investors to reassess BWP Trust (ASX:BWP) and its rental-backed distribution profile.
BWP Trust’s recent share price has been under pressure, with the stock down 7.35% on a 90 day share price return basis and 10.63% year to date. However, the 3 year total shareholder return of 23% and 5 year total shareholder return of 11.33% point to steadier longer run compounding behind the current loss of momentum.
Compare how BWP Trust stacks up against other income-focused property opportunities by scanning our hand-picked 3 dividend fortresses for alternative yield ideas as rates reset higher.
For BWP Trust, the bullish story leans on rental-backed distributions and long run total returns. The bear case points to rising rates and softer recent performance. Which side do the current valuation markers actually support?
Price-to-Earnings of 6.9x: Is it justified?
BWP Trust currently trades on a P/E of 6.9x, which puts the A$3.53 unit price in territory that suggests the market is pricing its earnings stream cautiously compared with similar retail property vehicles.
The P/E ratio compares what investors pay per unit with the earnings generated per unit, so for a real estate investment trust like BWP Trust it reflects how investors value its rental income and related profits. For income-focused owners, this yardstick matters because it anchors expectations for how much they are paying for each dollar of current profit in a sector where earnings can be sensitive to interest costs and property valuations.
BWP Trust screens as good value on this measure compared with peers. The P/E of 6.9x sits below both the Global Retail REITs average of 12.4x and the peer average of 8x. This indicates the stock is being valued at a lower earnings multiple than similar listed property businesses. It also trades below an estimated fair P/E of 8x, a level the market could plausibly move toward if sentiment or earnings expectations shift.
Explore the SWS fair ratio for BWP Trust.
Result: Price-to-Earnings of 6.9x (UNDERVALUED)
Still, the narrative can break if higher financing costs compress property values or if weaker tenant demand drags on rental income and earnings quality.
Find out about the key risks to this BWP Trust narrative.
Another view on BWP Trust’s value
On earnings multiples BWP Trust looks inexpensive, and our DCF model paints a similar picture. Units around A$3.53 trade at a discount to an estimated future cash flow value of A$4.58, which implies the market is pricing a wide margin of safety. Is that caution warranted or overdone?
Look into how the SWS DCF model arrives at its fair value.
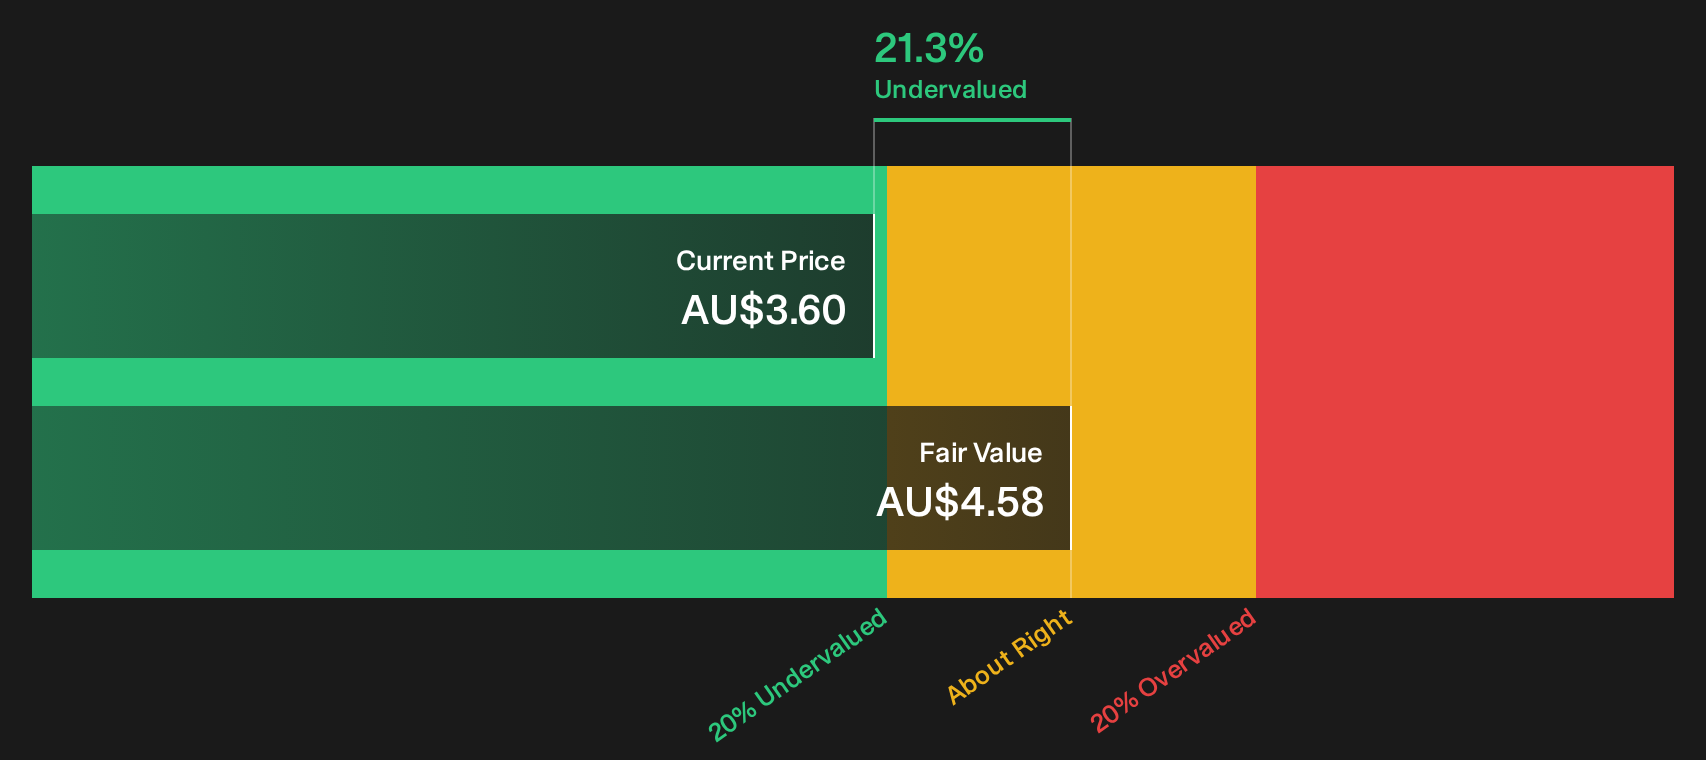
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out BWP Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals in BWP Trust’s recent performance and valuation make this a stock that rewards close inspection rather than headlines. Act quickly, pull up the full data, and weigh the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond BWP Trust?
Do not park everything in one income play. Broaden your watchlist with a few focused screens that surface different types of opportunities investors often overlook.
- Target resilient balance sheets by running the list of solid balance sheet and fundamentals (12 results) that filters for companies with financial foundations built to handle tougher conditions.
- Hunt for mispriced quality through the 5 high quality undervalued stocks that highlights businesses where fundamentals and current pricing look out of sync.
- Spot early-stage potential using the 15 high quality undiscovered gems that surfaces quieter companies with strong underlying metrics before attention fully arrives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com