
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Japanese Export Stocks Retail Investors Are Watching as Bond Yields Climb
Global bond markets are ripping up the old playbook, pushing yields toward multi year highs and forcing investors to rethink what risk really costs. Japanese exporters suddenly sit in a curious sweet spot, with a weaker yen and higher global discount rates pulling in opposite directions. This article examines three large cap stocks exposed to these cross currents and explains how this backdrop might help or hurt future performance.
The three stocks in focus are only a narrow sample of what is on offer, since the full screen surfaced 71 more Japanese large caps with export exposure and detailed stories that are not covered here.
If you want to move straight from ideas to your own short list, head into the Export-Oriented Japanese Large-Cap Equities screener to identify, filter, and analyze the highest conviction export oriented plays.
Renesas Electronics (TSE:6723)
Overview: Renesas Electronics is a large Japanese semiconductor producer supplying automotive and industrial chips worldwide, highly exposed to overseas demand and yen moves.
Operations: Renesas generates about ¥681.2b from Automotive and ¥771.9b from Industrial/Infrastructure/IoT, supported by sizeable sales in China, wider Asia, Europe and North America.
Market Cap: ¥6.4t
Renesas Electronics fits this exporter screen because its auto and industrial chips are built for global customers, yet its costs and reporting currency remain anchored in yen, which creates real leverage to currency swings and demand cycles in overseas end markets.
"The increasing adoption of electric vehicles and autonomous driving features is set to drive higher demand for advanced automotive MCUs and ADAS SoCs, particularly as Renesas ramps production of its new 28-nm MCU platform beyond China into Japan and Europe; this is likely to meaningfully support automotive segment revenue growth and help Renesas outpace the addressable market over the next 2 to 3 years."
What matters next is how one unresolved pressure on pricing power and mix shapes the payoff from that overseas demand surge.
That pricing pressure is only half the story, and the full narrative for Renesas Electronics shows how currency moves, product mix, and capital intensity could reshape Renesas Electronics over the next cycle.
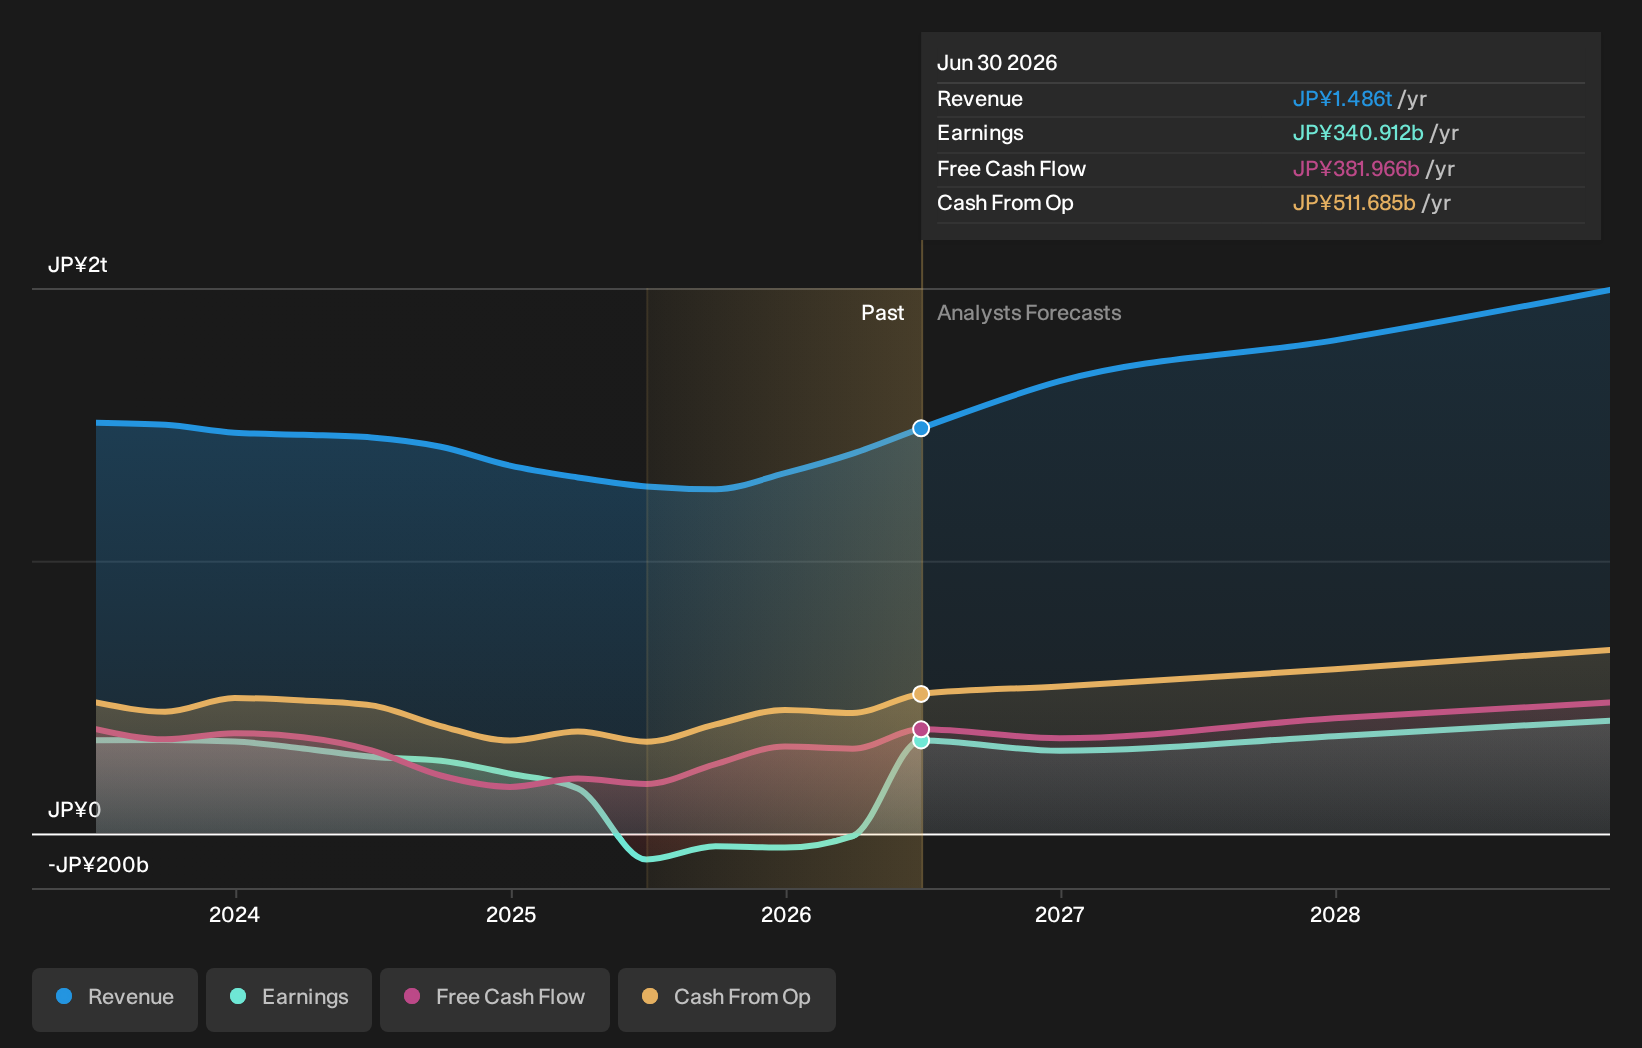
Keyence (TSE:6861)
Overview: Keyence supplies factory automation sensors, vision systems, and control equipment that help manufacturers worldwide measure, inspect, and run production lines efficiently.
Operations: Keyence generates about ¥1.25t in revenue from manufacturing and selling applied electronic equipment, primarily automation and sensing products for industrial customers.
Market Cap: ¥19.5t
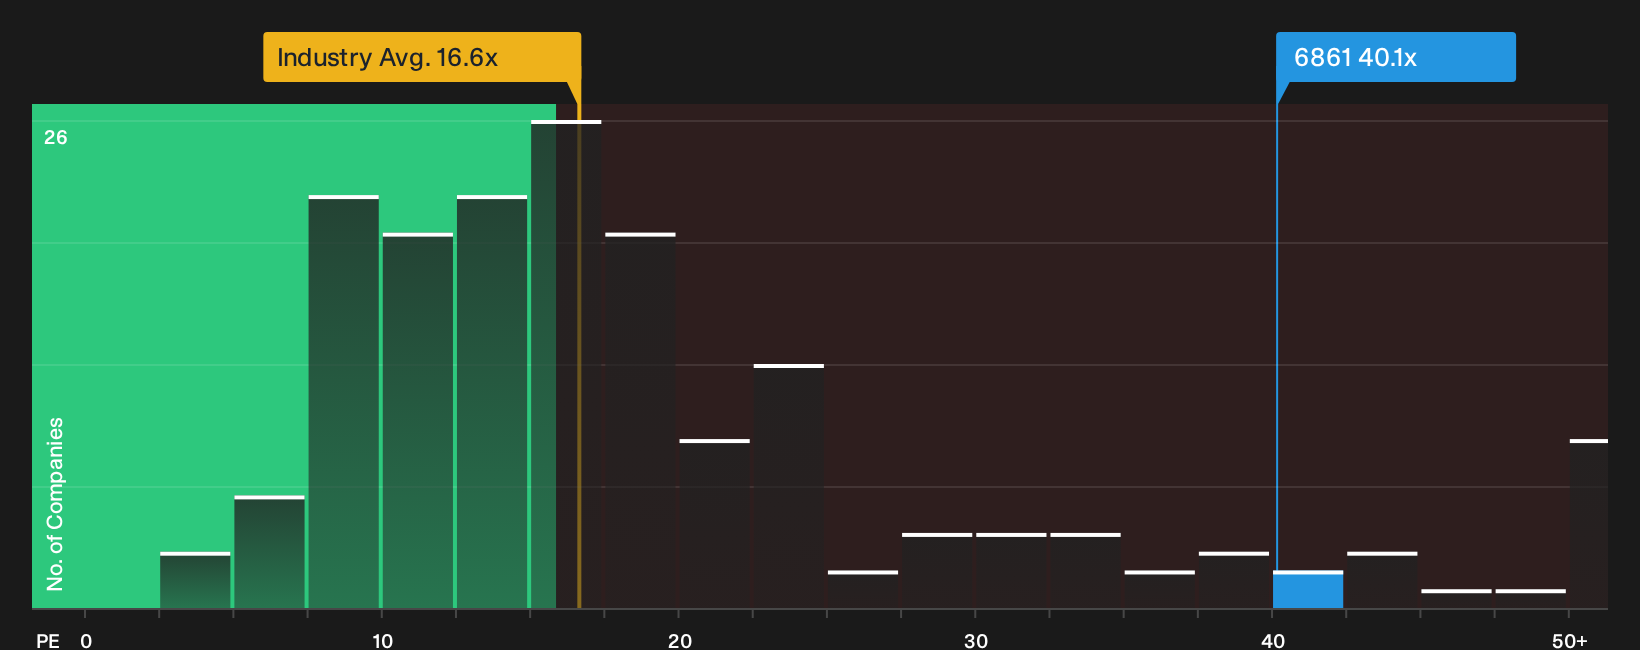
Keyence fits this export oriented screen because its automation gear is sold globally while costs are anchored in yen, so currency swings and overseas demand changes can significantly affect earnings. Investors get double exposure to factory investment cycles and FX, which can be powerful when both move in the same direction, but outcomes will also depend on how any pressure on high expectations and valuation develops.
When expectations feel stretched, the analysis report for Keyence shows where Keyence’s story of premium pricing, FX exposure and factory spend could still be underappreciated.
Sumco (TSE:3436)
Overview: Sumco produces high purity silicon wafers in Japan for chipmakers worldwide, tying its fortunes closely to global semiconductor demand and yen moves.
Operations: Sumco generates ¥419,314 million from high purity silicon wafers, serving customers across Japan, Taiwan, China, South Korea, Europe, and the United States.
Market Cap: ¥1.2t
Sumco fits into this export oriented screen because its wafers are priced in a global semiconductor supply chain while costs sit largely in yen, which can turn currency swings into either a helpful tailwind or an extra headwind on already volatile earnings.
"The accelerating requirements for ultra-high-purity substrates, driven by AI, advanced server logic, and HBM in DRAM, are beginning to outstrip customer manufacturing capacity, positioning Sumco as a potential beneficiary of volume growth and as a possible price-setter for high-end wafers, which could support higher ASPs and an expanding EBITDA margin over a multi-year horizon."
What happens to that margin story depends heavily on how one quiet shift in funding costs and external financing conditions plays out from here.
As funding costs shift, the full narrative for Sumco shows how Sumco’s AI wafer demand, pricing power and FX exposure could accelerate or stall the next phase.

Seeking Alternatives Beyond These Exporters
Fresh ideas move fast. Some are building breakout momentum, others are still under the radar for now, and pricing can get away quickly. Scan the field and act now.
- Spot resilient cash generators before they get repriced by the crowd by running a focused check on the list of solid balance sheet and fundamentals (23 results).
- Track where AI demand could be flying next by scanning the curated list inside the 90 AI infrastructure stocks.
- Catch powerful yield stories while prices are still dropping or drifting sideways by reviewing the hand-picked opportunities in the 20 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com