
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Higher Bond Yields Put Thai Life Insurance Stock And Other Insurers In Focus
When the 30 year US Treasury yield climbs to a level last seen roughly 25 years ago, the story is bigger than bond charts. It reshapes how cash flows are valued, which sectors feel squeezed, and where patient capital may find steadier income. Rising risk free rates can pressure growth heavy shares yet potentially improve investment returns for some insurers. This piece walks through three stocks exposed to that rate shock and how their profiles might appeal to, or concern, long term investors.
The insurers covered below are only a sample of this theme, and the full screen surfaced 34 more listed players with similarly detailed stories that are not broken out individually here. If you want to go straight to the source and size up the broader opportunity set yourself, analyze the Life and Property-Casualty Insurers Benefiting from Higher Long-Term Yields screener through the Life and Property-Casualty Insurers Benefiting from Higher Long-Term Yields screener.
Thai Life Insurance (SET:TLI)
Overview: Thai Life Insurance is a Thai pure-play life insurer that sells protection and savings policies and invests premiums in bonds.
Operations: Thai Life Insurance generates about THB 29.5b of revenue from its Agent Channel and THB 10.1b from Partnership and Other Channels, all in Thailand.
Market Cap: THB 127.1b
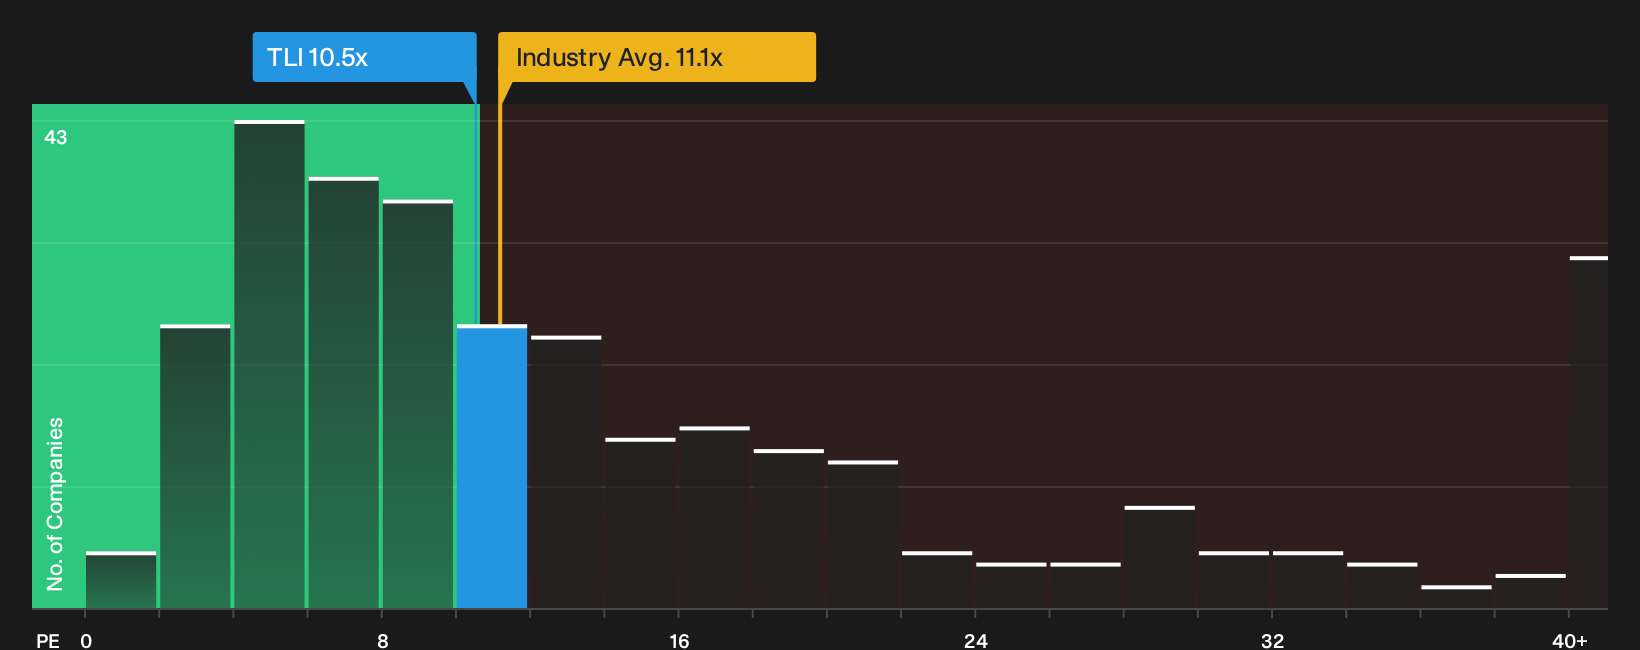
Thai Life Insurance links directly to this higher-yield theme because it is a life specialist with a large bond-heavy portfolio and a P/E of 10.5x versus an Asian insurance industry average of 11.3x. Analysts see faster 12.9% revenue growth than the Thai market and a positive dividend signal. However, everything still hinges on what happens when one pressure on funding costs and spreads shifts direction.
When funding costs and spreads are in flux, review the 4 key rewards and 1 important warning sign to see how that balance could reshape Thai Life Insurance’s risk and income mix.
Sampo Oyj (HLSE:SAMPO)
Overview: Sampo Oyj is a large Nordic non-life insurer that collects premiums and invests a substantial float in fixed-income assets.
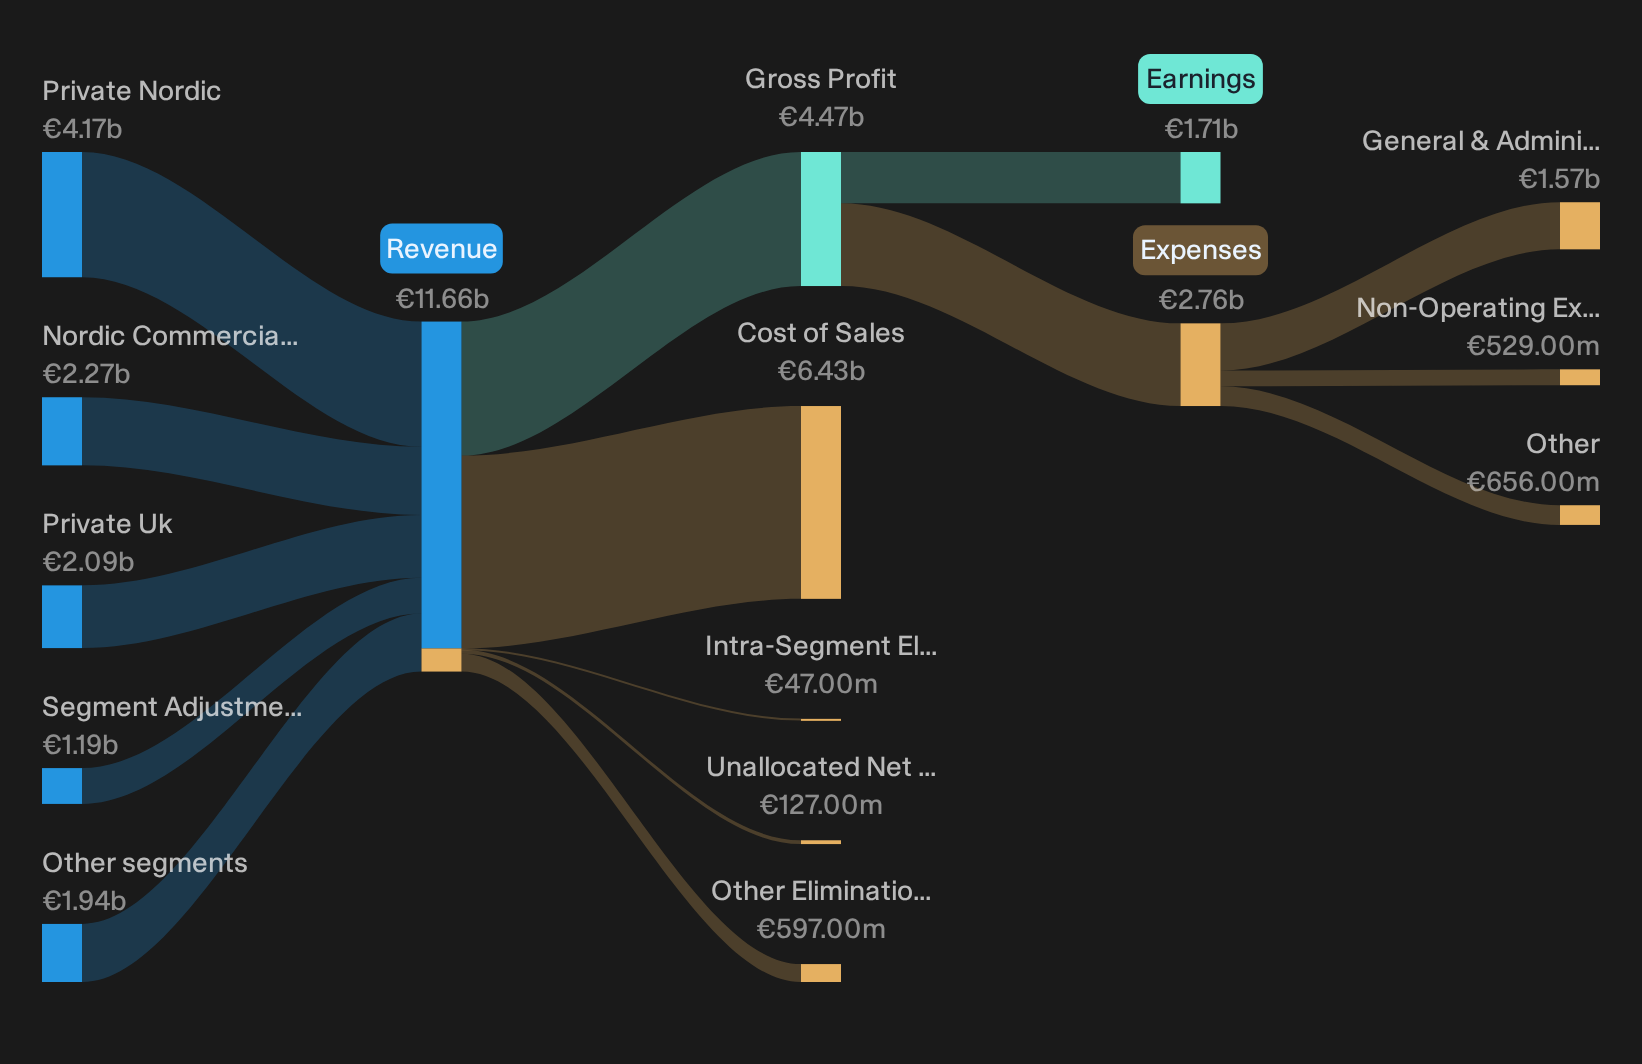
Operations: Sampo Oyj earns about €4.2b from Private Nordic, €2.3b from Nordic Commercial, €2.1b from Private UK and €600m from Nordic Industrial customers.
Market Cap: €22.96b
Sampo Oyj matters in this higher-yield theme because its sizeable Nordic and UK non-life franchises create a large pool of investable float that can respond directly to rising long-term bond returns.
"Ongoing investments in digital distribution, automation, and analytics are driving margin expansion through improved underwriting quality, lower cost ratios, and enhanced claims management, supporting higher net margins and bottom-line earnings."
The relationship between that underwriting engine and any sustained shift in long-term yields will likely influence how far profitability can stretch.
If you want to see how that underwriting engine and rate backdrop could be decoupling, read the full narrative for Sampo Oyj for the full context on where Sampo Oyj might be accelerating next.
Definity Financial (TSX:DFY)
Overview: Definity Financial is a Canadian property and casualty insurer that writes auto, home, pet and commercial policies and invests the resulting float.
Operations: Definity Financial generates about CA$6b of revenue from its P&C Insurance segment, which is the company’s sole reported business line.
Market Cap: CA$8.37b
Definity Financial sits squarely in this higher-yield theme because every policy it writes creates float that can be parked in longer-dated bonds. Rising risk free rates directly affect its investment income line at the same time as it works to sharpen underwriting.
"The pending acquisition of Travelers Canada is set to unlock significant scale benefits and operational synergies for Definity, which are expected to meaningfully lift combined profitability and ROE post-integration, supporting stronger future earnings and net margins."
The key issue for investors is how one unresolved pressure on future underwriting costs interacts with that larger float and higher bond yields.
That unresolved pressure is exactly what the full narrative for Definity Financial unpacks, showing where Definity Financial’s underwriting risks could be masking a sharper earnings and float story.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Some trends are already breaking out, while others are quietly building momentum under the radar for now. Consider researching potential opportunities early instead of responding only after major moves have already occurred.
- Target steady cash generators by scanning a curated 157 dividend fortresses that focus on durability, consistent payouts, and balance sheets built to handle rough patches.
- Review 92 robotics and automation stocks to explore companies involved in the hardware and software used in factories, warehouses, and smart devices.
- Assess 19 cryptocurrency and blockchain stocks to follow businesses tied to exchanges, payment rails, and core blockchain infrastructure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com