
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
UK Growth Stocks With Strong Insider Ownership
The United Kingdom's FTSE 100 index has recently faced challenges, closing lower due to weak trade data from China, which has impacted companies with significant exposure to the Chinese market. Amidst these global economic uncertainties, identifying growth stocks with strong insider ownership can provide investors with potential opportunities for stability and confidence in their investment choices.
Top 10 Growth Companies With High Insider Ownership In The United Kingdom
| Name | Insider Ownership | Earnings Growth |
| TEAM (AIM:TEAM) | 32% | 85.3% |
| Quantum Base Holdings (AIM:QUBE) | 31.8% | 111.8% |
| Mortgage Advice Bureau (Holdings) (LSE:MAB1) | 18.4% | 22.4% |
| Metals Exploration (AIM:MTL) | 15.9% | 118.9% |
| Hardide (AIM:HDD) | 20.8% | 76.2% |
| Energean (LSE:ENOG) | 19.3% | 32.9% |
| EARNZ (AIM:EARN) | 19.5% | 76.5% |
| Crimson Tide (AIM:TIDE) | 33.5% | 119.1% |
| Beauty Tech Group (LSE:TBTG) | 20.6% | 23.8% |
| ActiveOps (AIM:AOM) | 22.2% | 81% |
We're going to check out a few of the best picks from our screener tool.
RWS Holdings (AIM:RWS)
Simply Wall St Growth Rating: ★★★★☆☆
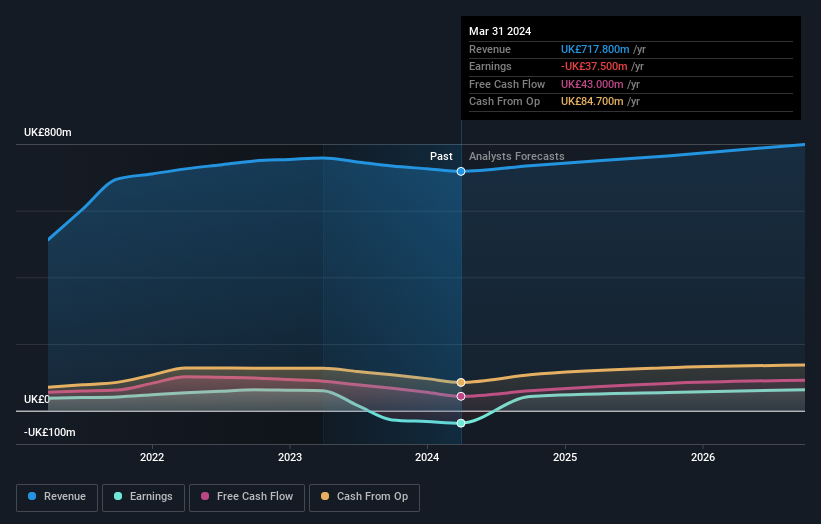
Overview: RWS Holdings plc provides artificial intelligence solutions across the United States, the United Kingdom, continental Europe, and internationally with a market cap of £497.32 million.
Operations: Revenue segments for the company include Language Services with £429.5 million, Regulated Industries at £259.3 million, and IP Services contributing £142.7 million.
Insider Ownership: 31.2%
RWS Holdings, with significant insider ownership, is positioning itself for growth through strategic product launches and leadership changes. The recent appointment of Patrick De Smedt as Chair brings valuable experience in guiding tech firms through strategic shifts. RWS's innovations, like the Tridion agentic platform and M-GATE benchmark, enhance its offerings in AI-driven content management and translation services. Despite a forecasted low return on equity (5.9%), RWS is expected to achieve profitability within three years, with earnings projected to grow significantly at 116% annually.
- Click here to discover the nuances of RWS Holdings with our detailed analytical future growth report.
- Our expertly prepared valuation report RWS Holdings implies its share price may be lower than expected.
Elixirr International (LSE:ELIX)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Elixirr International plc, with a market cap of £254.20 million, provides management consultancy services through its subsidiaries in the United Kingdom, the United States, and internationally.
Operations: The company generates £167.15 million in revenue from its management consulting services across various regions including the UK and the US.
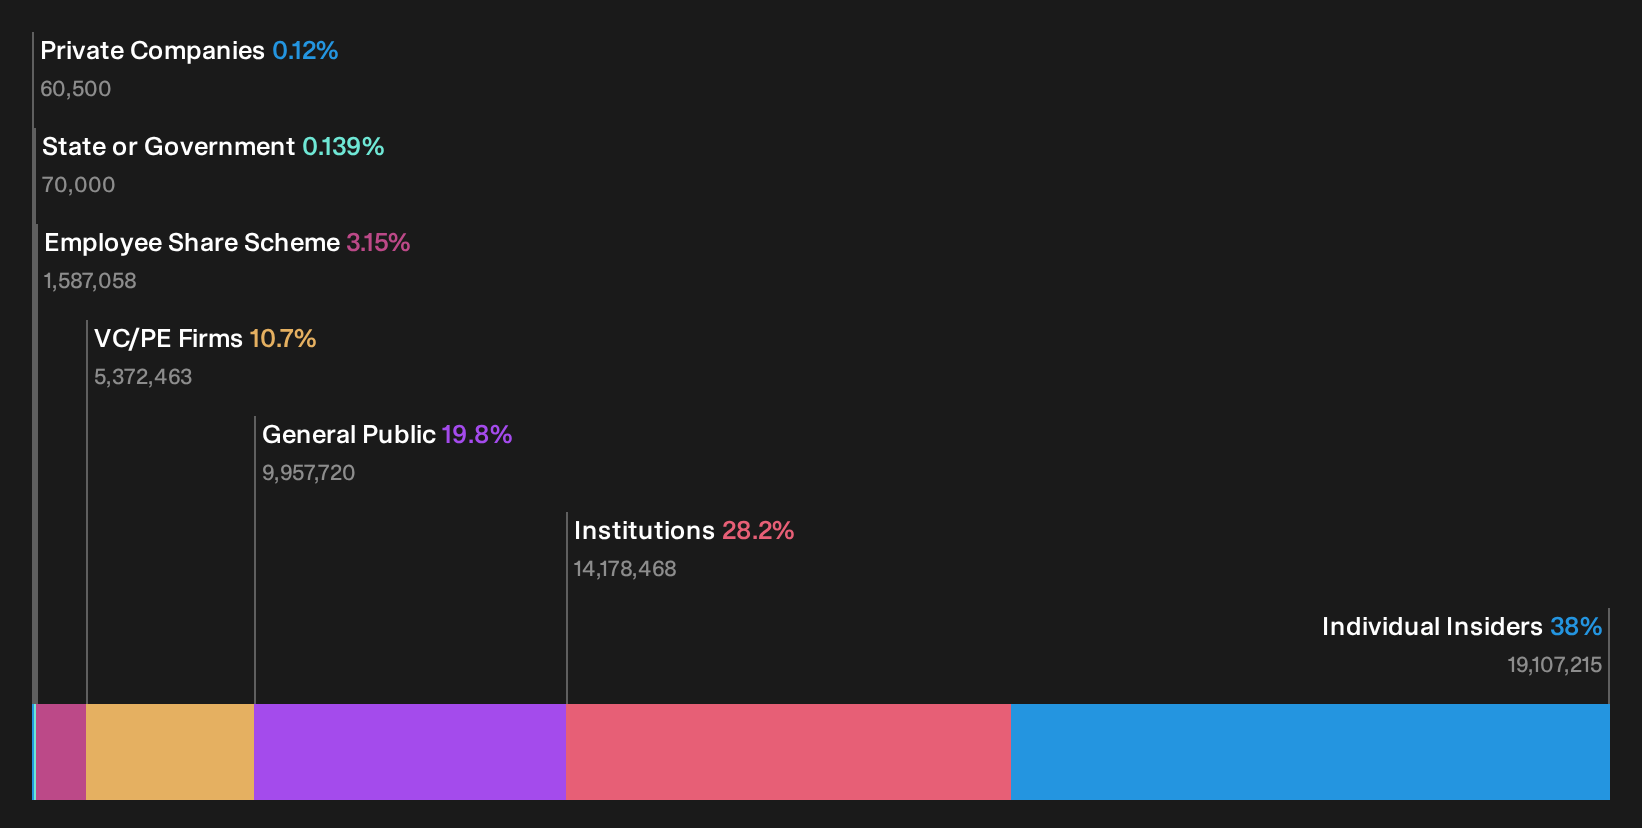
Insider Ownership: 37.4%
Elixirr International, with substantial insider ownership, demonstrates promising growth prospects. Its earnings are forecast to grow at 16.65% annually, surpassing the UK market average of 11.2%. Recent half-year results show a revenue increase to £88.96 million from £71.41 million and net income rising to £12.34 million from £11.02 million year-on-year, highlighting its growth trajectory despite an unstable dividend record and moderate revenue growth expectations of 8.1% per annum compared to the market's 3.9%.
- Get an in-depth perspective on Elixirr International's performance by reading our analyst estimates report here.
- Our valuation report here indicates Elixirr International may be undervalued.
Mortgage Advice Bureau (Holdings) (LSE:MAB1)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Mortgage Advice Bureau (Holdings) plc, along with its subsidiaries, offers mortgage advice and guidance on protection and general insurance products in the United Kingdom, with a market capitalization of £205.11 million.
Operations: The company generates revenue of £330.34 million from its financial services, which include mortgage advice and guidance on protection and general insurance products in the United Kingdom.
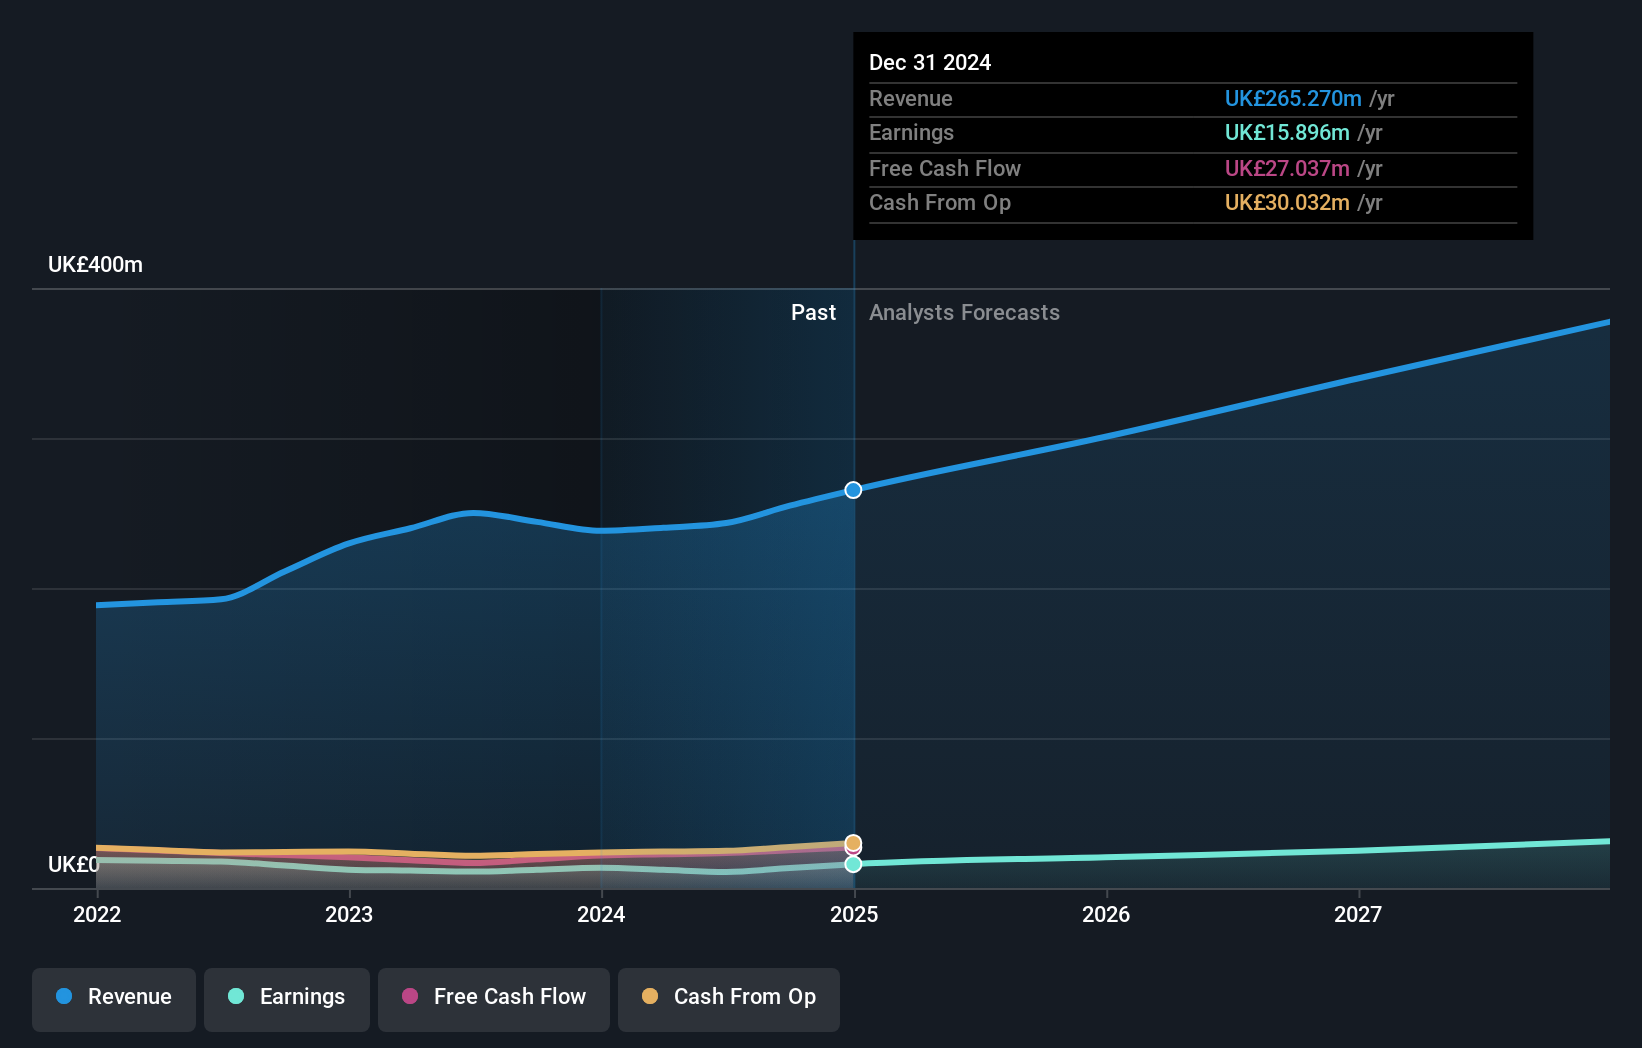
Insider Ownership: 18.4%
Mortgage Advice Bureau (Holdings) shows potential as a growth company with high insider ownership, despite recent executive changes. Its revenue rose by 8% to £160 million in H1 2026, though net income dropped to £3.63 million from £6.82 million year-on-year. Earnings are expected to grow significantly at 22.44% annually, outpacing the UK market's average growth forecast of 11.2%, while insider buying has been more frequent than selling recently but not substantial in volume.
- Take a closer look at Mortgage Advice Bureau (Holdings)'s potential here in our earnings growth report.
- Our valuation report unveils the possibility Mortgage Advice Bureau (Holdings)'s shares may be trading at a premium.
Make It Happen
- Explore the 63 names from our Fast Growing UK Companies With High Insider Ownership screener here.
- Interested In Other Possibilities? Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com