
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Novanta (NOVT) Still Undervalued After Its Riverpoint Medical Deal?
Novanta (NOVT) drew fresh attention after investors revisited the business profile behind its precision medicine, manufacturing, and medical solutions operations, following new coverage that highlighted its two core segments and global customer base.
Recent trading has been mixed, with a 1-day share price return of 0.69% and a 90-day share price return down 12.08%, while Novanta’s year-to-date share price return of 27.94% and 1-year total shareholder return of 37.71% point to momentum that has cooled in the short term but remains strong over a longer window.
Scan a curated field of peers in precision medicine, robotics, and automation by checking the 92 robotics and automation stocks, which reflects Novanta’s mix of healthcare technology and industrial motion control.
After a strong stretch over the past year but a softer three months, Novanta now sits at a crossroads where solid reported growth meets a cooler share price. Does that skew the risk reward toward fresh buyers or restraint?
Most Popular Narrative: 27% Undervalued
The most followed narrative pegs Novanta’s fair value at $194.50, well above the recent $142.19 close. This puts the focus squarely on execution risk rather than lack of upside in the model.
Expansion of minimally invasive and robotic surgery, together with the Riverpoint Medical acquisition that roughly doubles recurring medical consumables revenue to about US$300 million and lifts medical exposure to around 60% of sales, increases Novanta's mix of repeat consumables that can support more resilient revenue and gross margin over time.
See why 5 investors see Novanta as 27% undervalued.
Result: Fair Value of $194.50 (UNDERVALUED)
Still, the Novanta story could be knocked off course if Medical Solutions margins stay under pressure or if the US$1.45b Riverpoint Medical deal underdelivers.
Find out about the key risks to this Novanta narrative.
Another View On Novanta’s Valuation
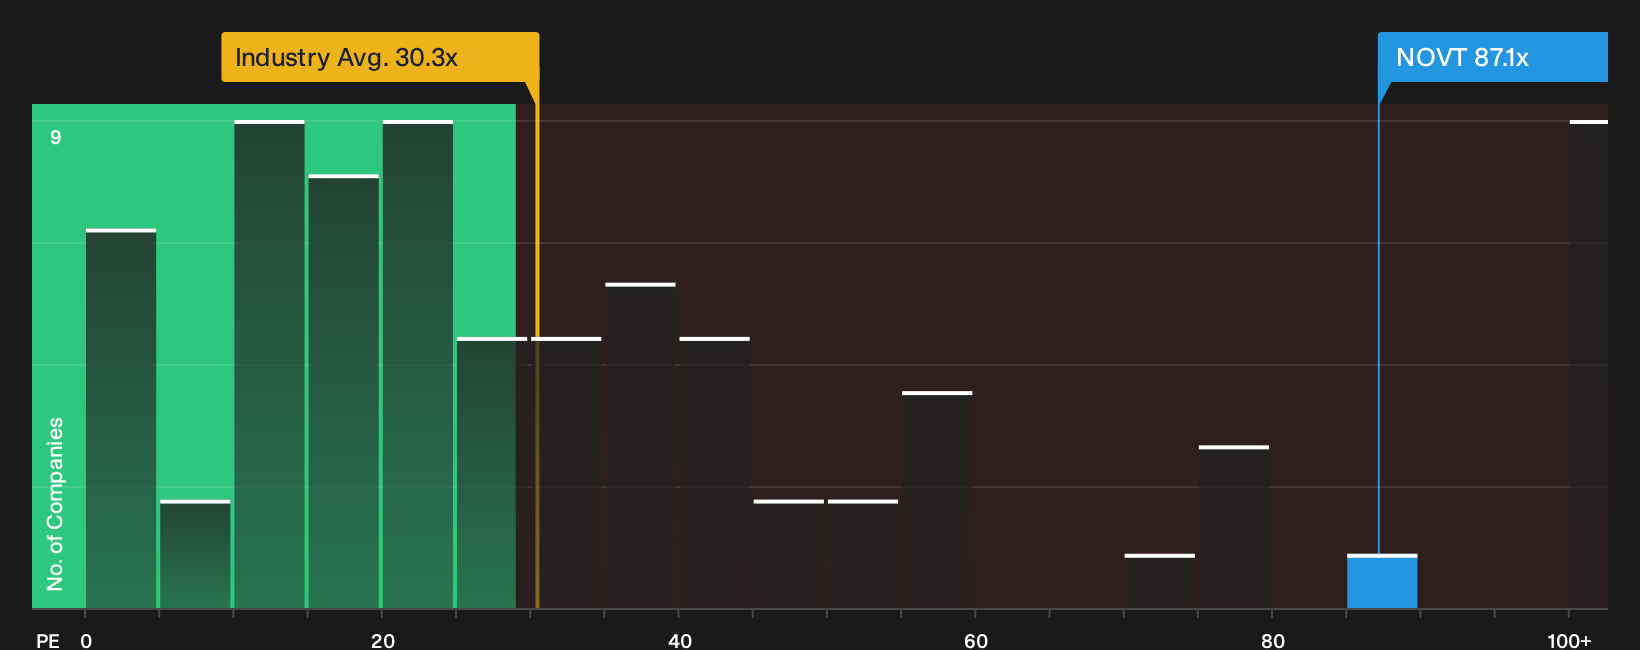
Analysts see Novanta as undervalued relative to a $194.50 price target, yet the P/E ratio of 87.1x is well above both the US Electronic industry average of 30.3x and an estimated fair ratio of 40.6x. That rich multiple shifts the question to whether investors are paying tomorrow’s optimism today.
For a closer look at how that premium compares with peers and the fair ratio that the market could move toward over time, check the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Novanta’s valuation and risk profile only matter if you test them yourself and decide where you stand. To see both the upside arguments and the caution flags in one place, review the 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Novanta?
If Novanta has you thinking harder about where to put fresh capital, do not stop at a single ticker when there are broader themes to compare.
- Target dependable cash generators by reviewing companies with resilient finances through the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality by scanning the 31 high quality undervalued stocks before sentiment or new information closes the gap.
- Spot potential early-stage upside by checking the 9 elite penny stocks with strong financials while these ideas still sit off most investors’ radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com