
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Nestlé (SWX:NESN) Following Legal Chief Change, Is The Fair Value Case Still Intact?
Nestlé (SWX:NESN) is back in focus after the board appointed Manuela Bernasconi as Group General Counsel and Group Executive Board member from January 2027, succeeding retiring legal chief Leanne Geale.
Nestlé’s recent leadership reshuffle comes amid a softer price backdrop, with the share price at CHF76.02 after declining about 10% over three months. The 1-year total shareholder return of 7.1% indicates that longer term holders have still seen gains, despite weaker three and five year total shareholder returns.
Scan how Nestlé compares with other large consumer staples by reviewing our curated list of 223 resilient stocks with low risk scores, which is built to weather choppy share price periods.
Bulls view Nestlé’s pullback alongside its recent net income growth as an opportunity to buy a quality business at a lower price. Bears, meanwhile, emphasize the company’s weaker multi year returns. Which side do the current valuation markers appear to support?
Most Popular Narrative: 16.5% Undervalued
Nestlé’s most followed narrative pegs fair value at CHF91.08 per share, which sits above the recent CHF76.02 close and naturally focuses attention on how the business earns its keep.
Nestlé is no longer a high-growth company, but a global compounder transforming toward higher-value nutrition categories. The key investment thesis is that Nestlé can gradually improve profitability through:
• Health Science,
• GLP-1 Nutrition,
• Pet Care,
• Premium Coffee,
• and Emerging Markets.
See why 19 investors see Nestlé as 17% undervalued.
Result: Fair Value of CHF91.08 (UNDERVALUED)
Still, the Nestlé thesis could wobble if the shift toward higher value nutrition underdelivers or if multi year share returns remain under pressure.
Find out about the key risks to this Nestlé narrative.
Another View: What Nestlé’s Market Multiple Is Saying
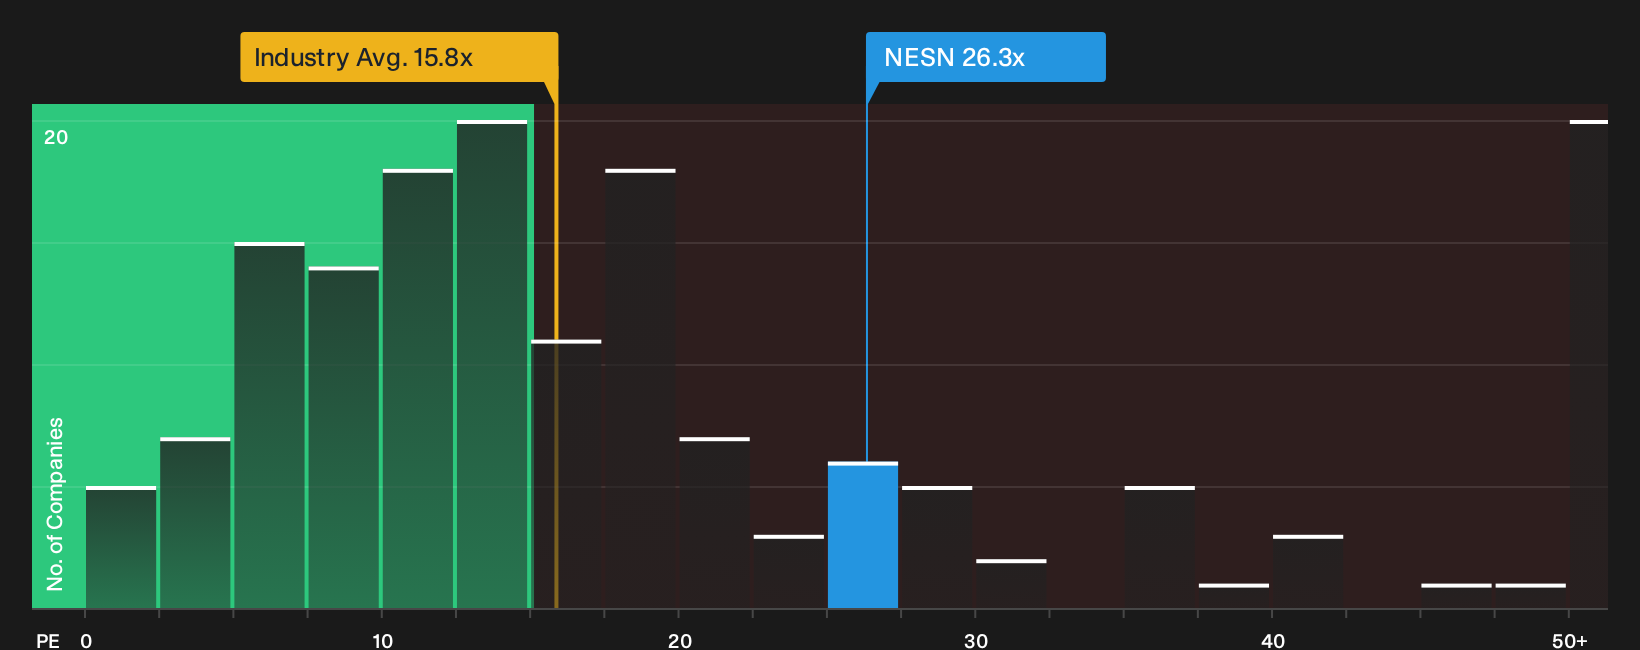
Nestlé may look cheap against a CHF91.08 fair value narrative, but the market’s own yardstick tells a different story. The shares change hands at a P/E of 26.3x, compared with 15.8x for the wider European food group and 22.3x for peers, while the fair ratio sits at 30.4x.
That mix of premium versus sector yet discount to the fair ratio points to a stock that already carries expectations, but could still re-rate if earnings grow as forecast. The real question for investors is which side of that gap ends up being wrong about Nestlé.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sitting between cautious and optimistic takes on Nestlé, you now have sentiment, valuation markers and context on the table. Move quickly and weigh both sides by checking the 2 key rewards and 3 important warning signs.
Looking for more Nestlé investment ideas beyond this story?
Do not stop your research at Nestlé alone. Broaden your watchlist with curated ideas filtered by quality, resilience and potential so you always stay one step ahead.
- Target resilient compounds that pair strong fundamentals with healthy balance sheets by scanning the list of solid balance sheet and fundamentals (205 results).
- Hunt for mispriced quality and see which companies screen as 192 high quality undervalued stocks before the crowd pays attention.
- Strengthen your income stream by reviewing the 156 dividend fortresses that combine higher yields with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com