
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Arista Networks (ANET) Lifted Its Outlook, Is The Upside Already Priced In?
Arista Networks (ANET) recently slipped 1.01% in a session where broader indexes moved higher, putting a spotlight on expectations for significantly higher upcoming earnings and revenue, as well as on shifting analyst estimates.
That slip comes after strong momentum, with a 90 day share price return of 27.25% and a year to date share price return of 52.39%. The 3 year total shareholder return of about 3.4x hints that investors have already priced in substantial growth expectations and are now reacting more finely to earnings and AI demand signals.
Spot potential echoes of Arista Networks’ AI-driven momentum by scanning our hand picked list of 90 AI infrastructure stocks.Arista Networks now trades close to rich expectations while analyst targets still sit meaningfully higher. Is the fair value closer to today's US$203.59, or to the implied upside in those models?
Most Popular Narrative: 16% Undervalued
On Simply Wall St, the most followed narrative pegs Arista Networks' fair value near $241.04, which sits above the recent $203.59 close and frames current pricing as a discount to that long term earnings view.
The renewed investment cycle in cloud and AI infrastructure now includes Arista Networks’ higher 2026 revenue outlook of about US$12.6b and specific goals for at least US$3.5b of AI fabrics revenue. Together with a maintained 62% to 64% gross margin range and a higher 48% to 49% operating margin target, this could support stronger earnings power.
See why 309 investors see Arista Networks as 16% undervalued.
Result: Fair Value of $241.04 (UNDERVALUED)
Still, the Arista Networks story leans heavily on a few giant cloud and AI buyers, and on AI data center buildouts that could slow if policy or demand shifts.
Find out about the key risks to this Arista Networks narrative.
Another View: Arista Networks Through The P/E Lens
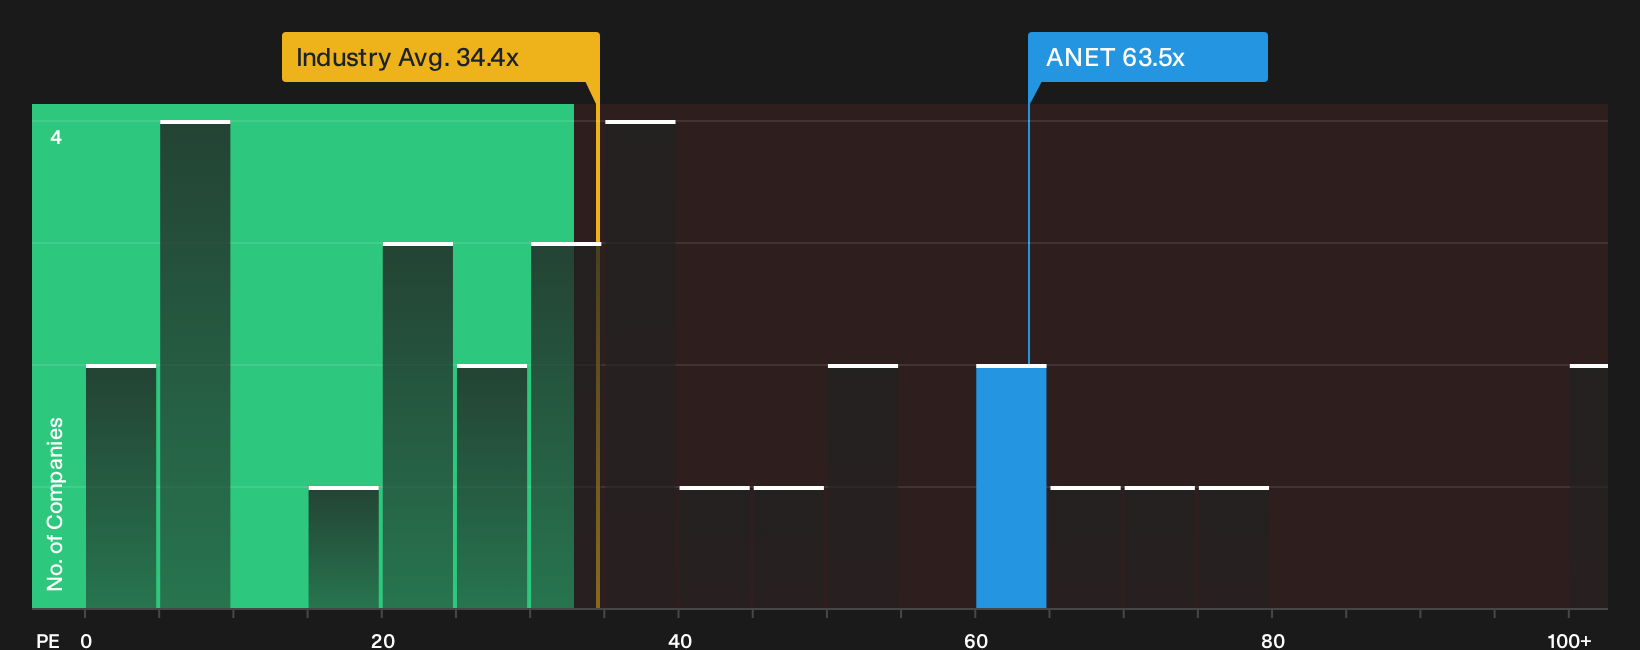
Arista Networks may look cheap on a long term earnings narrative, but the current P/E of 63.5x tells a tougher story. That is far above the US Communications industry at 34.4x, the peer average at 44.6x, and the fair ratio estimate of 41.1x, which points to meaningful valuation risk if expectations cool.
For investors weighing that gap between price and earnings, the detailed breakdown of how these ratios stack up against fundamentals can help frame what would need to change for the market to drift closer to that fair ratio over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Arista Networks is clearly split between excitement and caution, so take a moment to weigh both sides for yourself, then review the 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Arista Networks?
If Arista Networks has sharpened your focus on quality and pricing power, do not stop here. Use the Simply Wall St Screener to widen your opportunity set across different styles of businesses.
- Target resilient compounding potential by scanning a 32 high quality undervalued stocks that combine strong fundamentals with prices that lag their underlying metrics.
- Prioritise capital preservation by reviewing 31 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
- Hunt for future leaders early by checking a 19 high quality undiscovered gems before they attract broad market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com