
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Air Water (TSE:4088) Faces A Fresh Valuation Test Following Governance Overhaul
Air Water (TSE:4088) is back in focus after shareholders approved a shift to a Company with an Audit and Supervisory Committee and elevated Independent Outside Director Mikihiko Kato to chair the board on September 22, 2026.
Recent governance changes arrive as Air Water’s share price trades at ¥2,920, with a 1-month share price return of 11.24% and a year-to-date share price return of 29.06%. That sits alongside a 1-year total shareholder return of 19.93% and a 5-year total shareholder return of 105.33%, which indicates that momentum has been building over a multi year horizon, even as sentiment reacts in the short term to shifts in oversight and risk perception.
Scan how Air Water’s governance shift compares with peers by reviewing companies on the 21 resilient stocks with low risk scores that combine resilient balance sheets with a focus on oversight quality.
Bulls see stronger governance and a sizeable intrinsic value gap. Bears point to the recent share price run and analyst targets sitting below the market. Which side does the valuation math support next?
Preferred Price-to-Sales of 0.6x for Air Water: Is it justified?
On simple revenue terms, Air Water screens as inexpensive, with the shares at ¥2,920 aligned to a P/S ratio of 0.6x while peers and fair value markers both sit higher.
The P/S multiple compares the equity value of the business to its annual sales. For a group like Air Water that spans industrial gas, energy solutions, healthcare, agriculture and logistics, revenue is a central reference point because earnings can swing around depreciation, interest costs and one off items, while sales remain a cleaner signal of commercial traction.
Here the pricing gap is clear. Air Water trades on a P/S of 0.6x compared with an estimated fair P/S ratio of 1.1x and a peer average of 1.7x. That combination points to the market assigning a lower valuation to each ¥ of revenue than both regression based fair value and the broader JP Chemicals set. This could narrow if sentiment toward the group and its risk profile shifts closer to those benchmarks.
Explore the SWS fair ratio for Air Water.
Result: Price-to-sales of 0.6x (UNDERVALUED).
Still, the recent loss of ¥63,949 and the share price trading 12.4% above the average analyst target could both pressure the Air Water narrative if sentiment cools.
Find out about the key risks to this Air Water narrative.
Another View on Air Water’s Value
The discount story looks very different when switching from sales multiples to cash flows. Our DCF model values Air Water at ¥5,519.22 per share, which is higher than the current ¥2,920 price and signals an undervalued outcome on this framework as well. If both revenue and cash flow lenses point to a discount, the key question is what risk the market is pricing in that these models might be smoothing over.
Look into how the SWS DCF model arrives at its fair value.
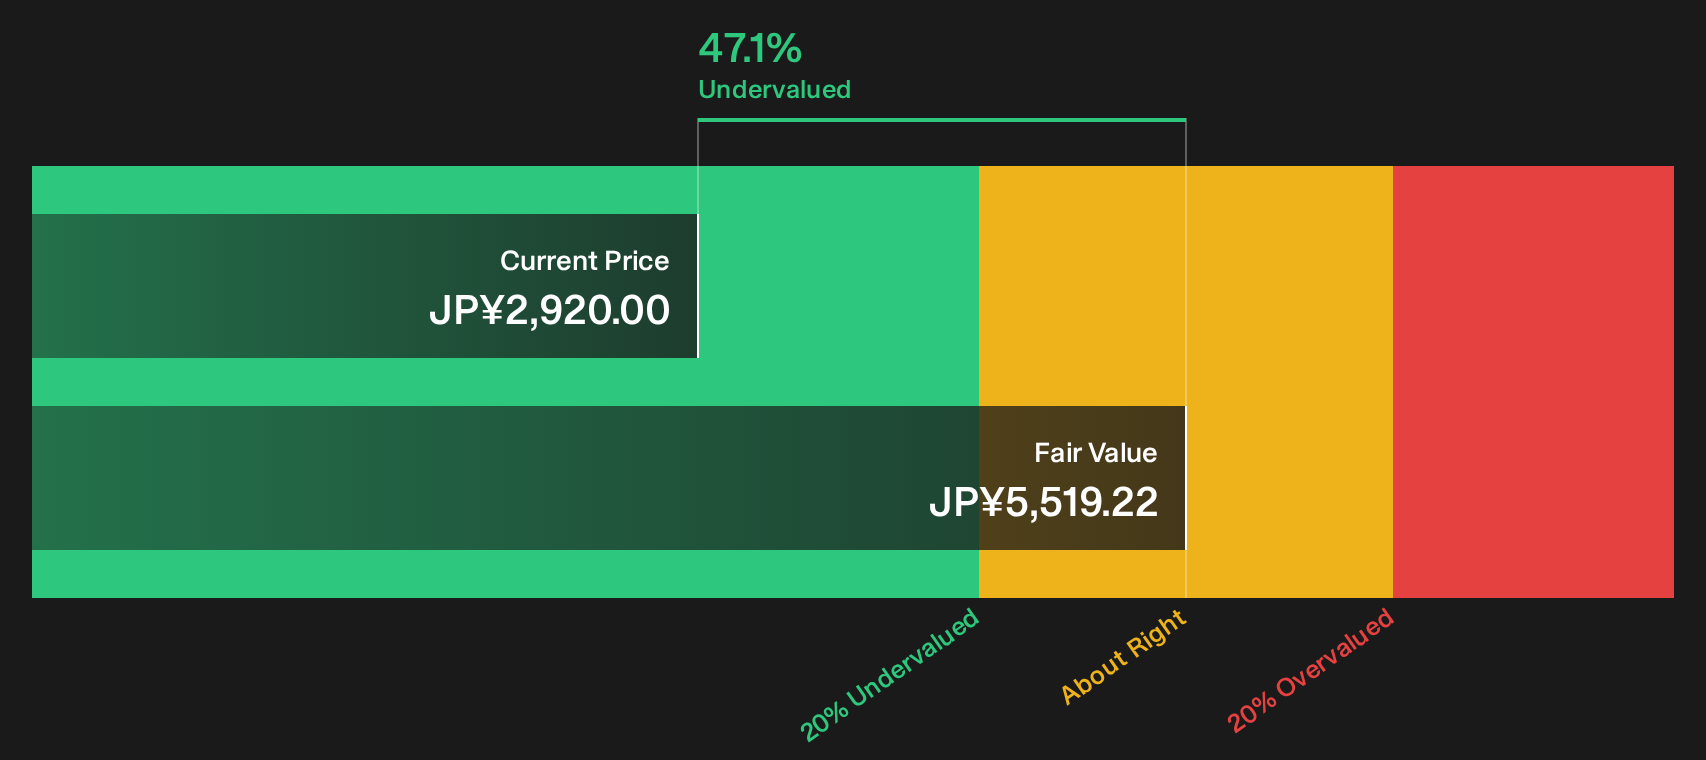
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Air Water for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Air Water’s valuation and governance only matter if you use them. Act while the data is fresh and weigh both sides by checking the 3 key rewards and 2 important warning signs
Hunting For More Ideas Beyond Air Water?
If Air Water has sharpened your focus on valuation and risk, do not stop here. Broaden your watchlist now or you risk missing the next opportunity.
- Target potential mispricing by scanning companies with strong fundamentals that still trade at a discount through the 18 high quality undervalued stocks.
- Strengthen portfolio resilience by filtering for businesses with robust finances using the list of solid balance sheet and fundamentals (23 results).
- Spot tomorrow’s potential standouts early by reviewing the 76 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com