
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can D Wave Quantum (QBTS) Stay A Bargain After Its 17x Run?
D-Wave Quantum has been on a wild ride in recent years, and the share price now forces a basic question for investors who care about fundamentals. Is the current market value of D-Wave Quantum stock meaningfully supported by what its balance sheet is actually worth on paper?
- Over the past 3 years, the stock has delivered a very large gain of about 17x. That puts serious pressure on whether its book value can justify where the shares trade today.
- Recent partnerships such as the tie-up with CGI, along with growing commercial interest in quantum applications, may support expectations for future revenue. That can influence how much of a premium investors are willing to pay over the company’s book value.
- Your read on D-Wave Quantum is one view; the desks covering it have another. See what analysts think D-Wave Quantum's shares could be worth.
The issue now is whether D-Wave Quantum’s current share price, after that kind of move and recent business momentum, lines up with what its book value and the industry average suggest it should be worth.
If you want to test the same book value question across more than just D-Wave Quantum, run the numbers on the 25 quantum computing stocks.
Does D-Wave Quantum Look Pricey on Book Value?
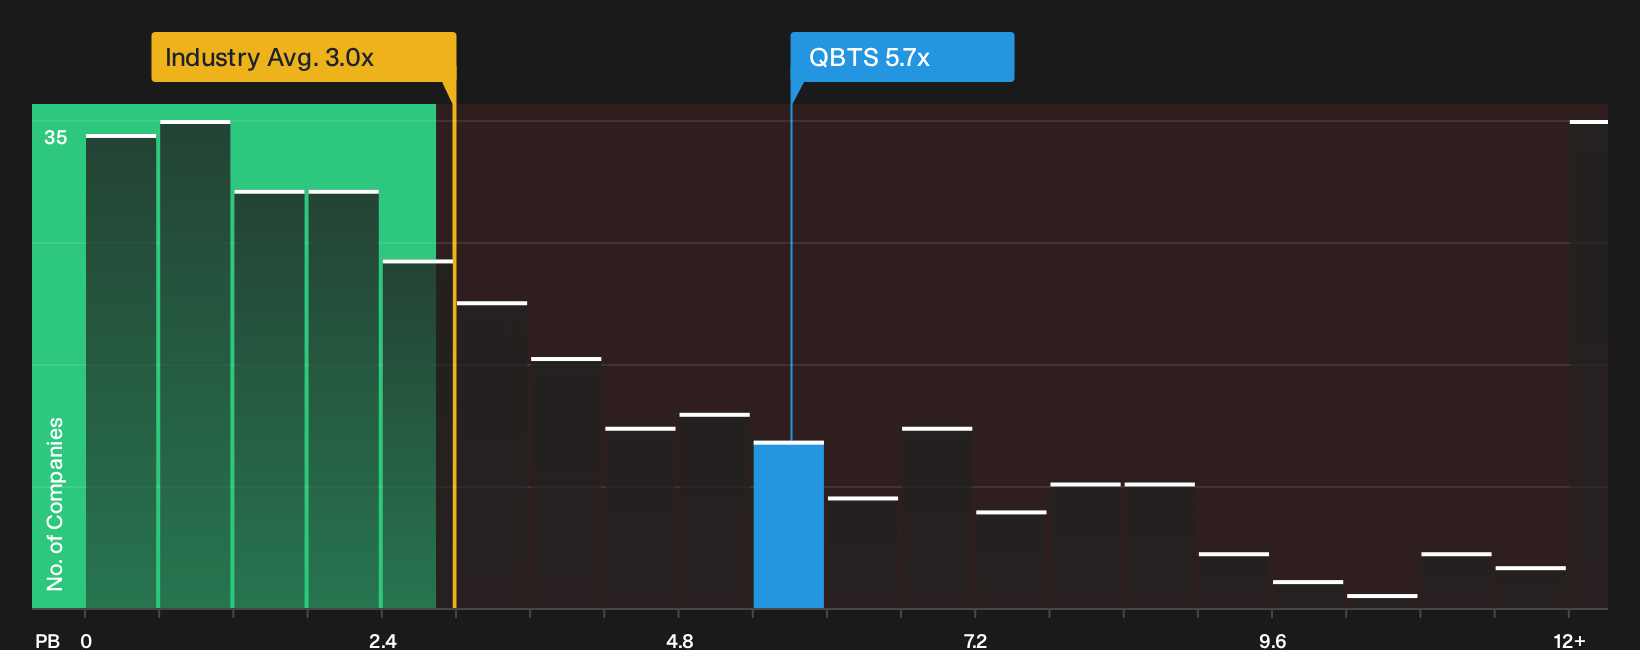
P/B is the cleaner yardstick for D-Wave Quantum because earnings are negative and revenue is still small, so the balance sheet gives you the clearest anchor. On that measure, the stock trades on a P/B of about 5.7x, compared with an industry average near 3.0x for Software.
That gap suggests investors are willing to pay a sizeable premium over the sector’s typical price for each dollar of D-Wave Quantum’s net assets. The CGI partnership and other commercial traction stories help explain why some shareholders may accept that markup, even though the business is still working with losses and very early stage revenue. In this context, the current P/B multiple appears high relative to the wider Software group. Explore the numbers behind D-Wave Quantum's P/B valuation.
The D-Wave Quantum Narrative: What Would Justify Today's Price?
D-Wave Quantum’s valuation puzzle does not end with the P/B multiple. Narratives on Simply Wall St’s Community page turn that high-level question into concrete scenarios, spelling out what kinds of growth, profitability and earnings paths would need to play out for the stock to be worth meaningfully more or less than it is today. Each narrative links its number to a specific view on how D-Wave Quantum’s growth, margins and risks might shift, which you can revisit as new information comes through.
One of the top community narratives on D-Wave Quantum: 59% undervalued
"Through a massive $550 million acquisition, a record-breaking month of sales, and a newly fortified balance sheet, D-Wave has moved the 'Quantum Era' off the whiteboards and into the executive boardroom..."
Discover why this Narrative puts D-Wave Quantum at 59% undervalued.
One more D-Wave Quantum check that belongs beside the valuation
The share price story is only part of it, because the people steering D-Wave Quantum and the way their pay is structured can heavily influence how risks and opportunities are handled over time. See who runs D-Wave Quantum and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com