
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Vistance Networks Stock Could Change Following DOCSIS 4.0 Rollout
- Vistance Networks, through its Aurora Networks business, recently highlighted a series of DOCSIS 4.0 and 50G PON launches and customer deployments, including Ziggo’s large-scale unified DOCSIS 4.0 rollout in Europe and Comcast’s field trials of the Unified OM6180 node and smart amplifiers.
- The combination of unified DOCSIS 4.0 hardware, AI-based management tools and an expanded 50G PON portfolio points to a push for more flexible, software-centric broadband infrastructure that can help major operators manage upgrade costs, deployment complexity and evolving capacity needs using existing network assets.
- We will now examine how Vistance Networks’ unified DOCSIS 4.0 rollout and 50G PON expansion could reshape the company’s broader investment narrative.
Vistance Networks Investment Narrative Recap
For a shareholder in Vistance Networks, the core belief is that DOCSIS 4.0, 50G PON and AI-managed networks can offset pressure in more cyclical parts of the business. The firm is currently unprofitable, with revenue of about US$1.99b and an annual revenue decline of 9.9%. The Aurora Networks updates matter because Aurora is the larger segment and heavily tied to operator capex cycles.
The near term swing factor is how fast large customers move from trials to broader adoption of unified DOCSIS 4.0 and 50G PON platforms as legacy HFC spend fades. The biggest risk remains concentrated exposure to a few cable operators and uncertainty around the pace and breadth of DOCSIS 4.0 upgrades, especially with a volatile share price and higher risk funding mix.
The Comcast field trials of Aurora Networks’ Unified DOCSIS 4.0 Opti Max OM6180 node and smart amplifiers look most relevant right now. These tests sit directly on the key operating question for Vistance Networks, which is whether DOCSIS 4.0 deployments can provide a durable replacement engine as older product lines slow and project timing remains lumpy.
If Comcast progresses from lab work into broader field use of the OM6180 and the unified Starline BLE amplifier, it would speak directly to that DOCSIS 4.0 catalyst. Execution risk is still real. Vistance Networks is closely tied to a small group of large buyers, and any delay, redesign or spending pause on this platform would quickly feed through to the Aurora segment’s revenue visibility.
Vistance Networks Forecasts and Valuation Anchors
Analysts sketch a future for Vistance Networks where revenues reach about US$2.4b and earnings come in at US$89.6 million by 2029, based on an assumed 7.6% yearly revenue growth rate and an earnings decline of US$165.8 million from US$255.4 million today.
Uncover why Vistance Networks' fair value indicates a 286% potential upside to its current price, which could narrow quickly.
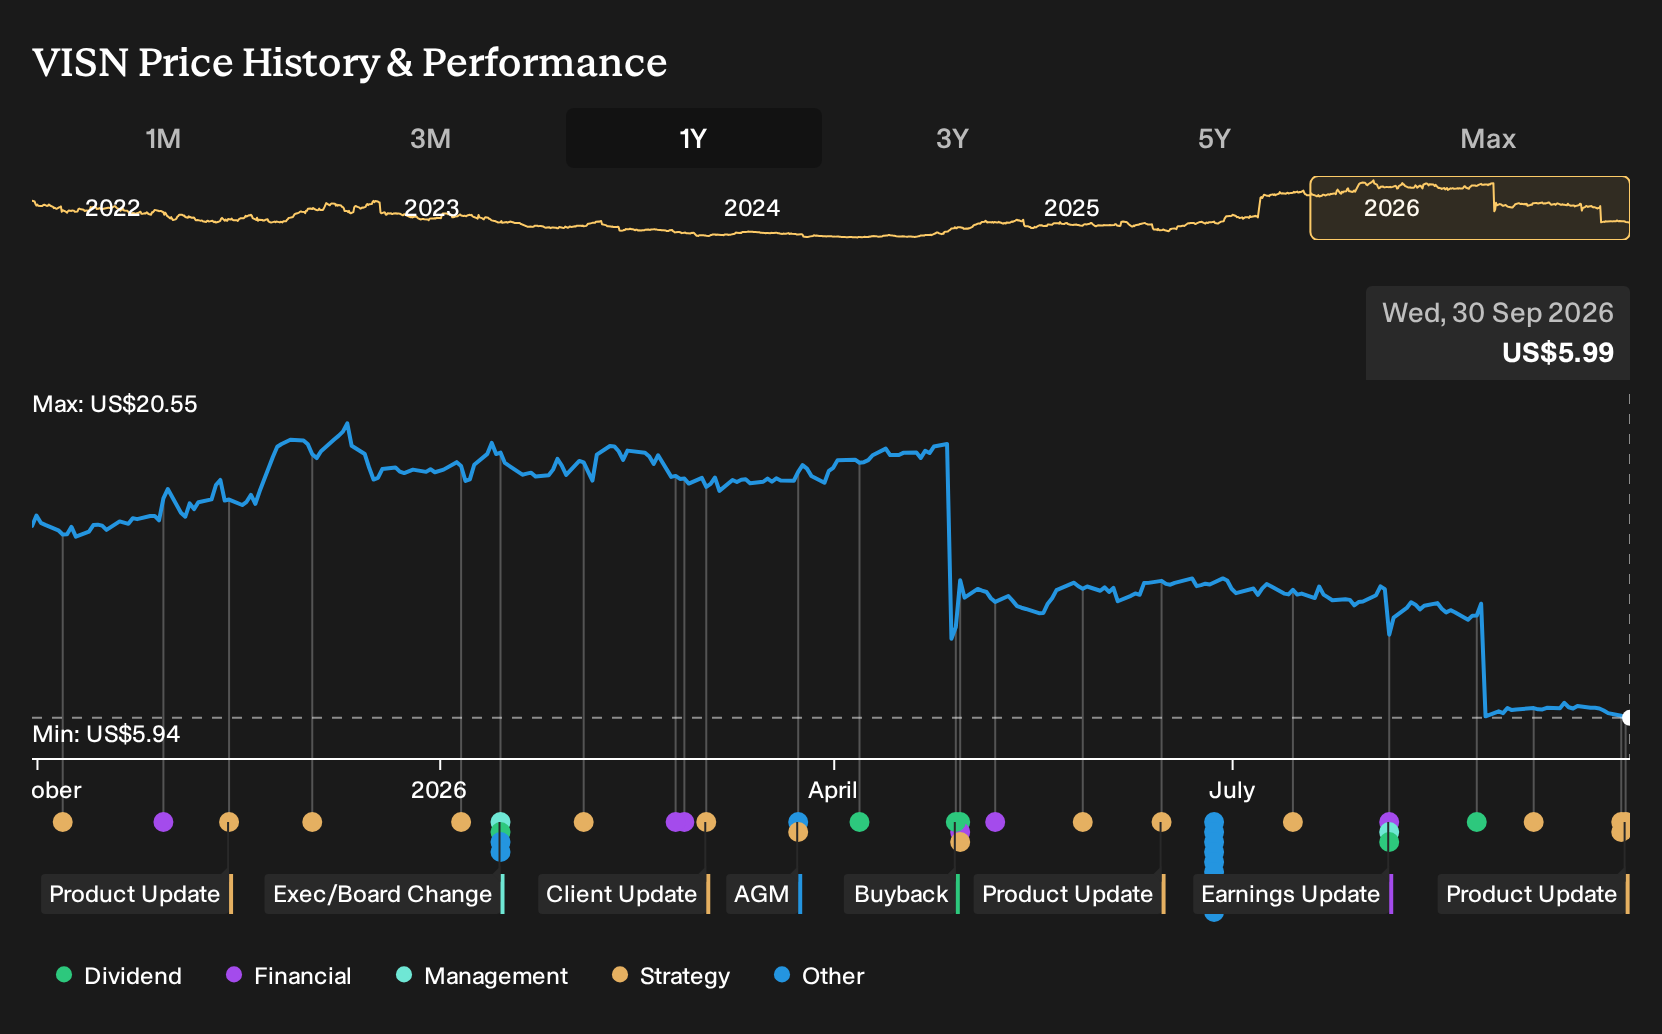
Exploring Other Perspectives
Some of the most optimistic analysts frame the Comcast and Ziggo activity as proof that Vistance Networks could keep DOCSIS 4.0 and 50G PON traction running hotter than the baseline narrative implies. Before this news, the bullish camp was already pencilling in revenue of about US$2.5b and earnings of US$79.4 million by 2029. That is more aggressive than the consensus view of US$2.4b and US$89.6 million. Use this spread in expectations as a reminder that views can differ widely. It is worth exploring both sides before deciding how these TechExpo26 announcements might shift your own outlook.
Explore 5 other Vistance Networks fair value estimates, including one that suggests a potential 318% increase from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own perspective.
- A great starting point for your Vistance Networks research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Vistance Networks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vistance Networks' overall financial health at a glance.
Looking for more investment ideas beyond Vistance Networks?
If Vistance Networks has sharpened your thinking about broadband, it can be useful to cross-check that view against other opportunities. Use the Simply Wall St Screener to line up different types of companies, compare their fundamentals side by side, and see where your capital might work hardest next.
- For investors who care most about quality and value, filter for companies that pair strong balance sheets with attractive valuations using the list of solid balance sheet and fundamentals (25 results).
- If you want income to play a bigger role in your returns, focus on cash-generative businesses by reviewing the 7 dividend fortresses.
- When you are hunting for potential future leaders that are not widely followed, cast a wider net with the 18 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com