
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hyakujushi Bank (TSE:8386) Creates CISO Role, Is The Stock Overvalued?
Hyakujushi Bank (TSE:8386) has reshaped its senior ranks after a September 18 board meeting, creating a Chief Information Security Officer role and appointing Managing Executive Officer Tetsuya Iwase, effective October 1, 2026.
For context, Hyakujushi Bank’s share price has climbed to ¥3,255, with a 90 day share price return of 24.0% and a year to date share price return of 93.46%. The 1 year total shareholder return of 167.33% and very large 5 year total shareholder return suggest strong longer term momentum, and this cybersecurity focused reshuffle now feeds into the broader risk and governance story.
Compare Hyakujushi Bank’s governance shift with other financial institutions stepping up their risk controls by scanning our hand picked 21 resilient stocks with low risk scores for your watchlist.
Hyakujushi Bank now carries a very large multi year return and trades at an implied premium to intrinsic value. At the same time, the new CISO move points to tighter risk control. Is the market being too cautious or not cautious enough?
Price-to-Earnings of 18.2x: Is it justified?
Hyakujushi Bank trades on a P/E of 18.2x, which sits above several comparison points and echoes the premium to intrinsic value flagged by the SWS DCF model at ¥1,697.95 versus the current ¥3,255 share price.
The P/E ratio compares the current share price with earnings per share and effectively shows how much investors are paying for each unit of profit. For a lender like Hyakujushi Bank, where profit growth and risk control sit in constant tension, this metric often reflects how confident the market feels about the durability of recent results.
Recent data shows reported earnings grew 44.6% over the past year, with profit growth over the last 5 years averaging 13.7% per year and current net profit margins of 20.3% compared with 19.2% a year earlier. With that backdrop, an 18.2x P/E can be read as investors placing a relatively rich tag on those earnings, especially given the SWS DCF estimate of ¥1,697.95 suggests the share price is well above the implied future cash flow value.
Compared with the JP Banks industry average P/E of 15.6x and a peer average of 17.1x, Hyakujushi Bank trades on a clearly higher multiple. This points to the stock being priced more expensively than many domestic banking peers on current earnings.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 18.2x (OVERVALUED)
Still, Hyakujushi Bank’s premium P/E and reliance on domestic Japanese banking and leasing conditions leave the story exposed if earnings or risk costs disappoint.
Find out about the key risks to this Hyakujushi Bank narrative.
Another View on Hyakujushi Bank’s valuation
The P/E discussion points in one direction, yet the SWS DCF model already frames Hyakujushi Bank as expensive at ¥3,255 versus an estimated future cash flow value of ¥1,697.95. That is a sizeable gap. Is the market paying up for momentum that the cash flow model does not fully reflect?
Look into how the SWS DCF model arrives at its fair value.
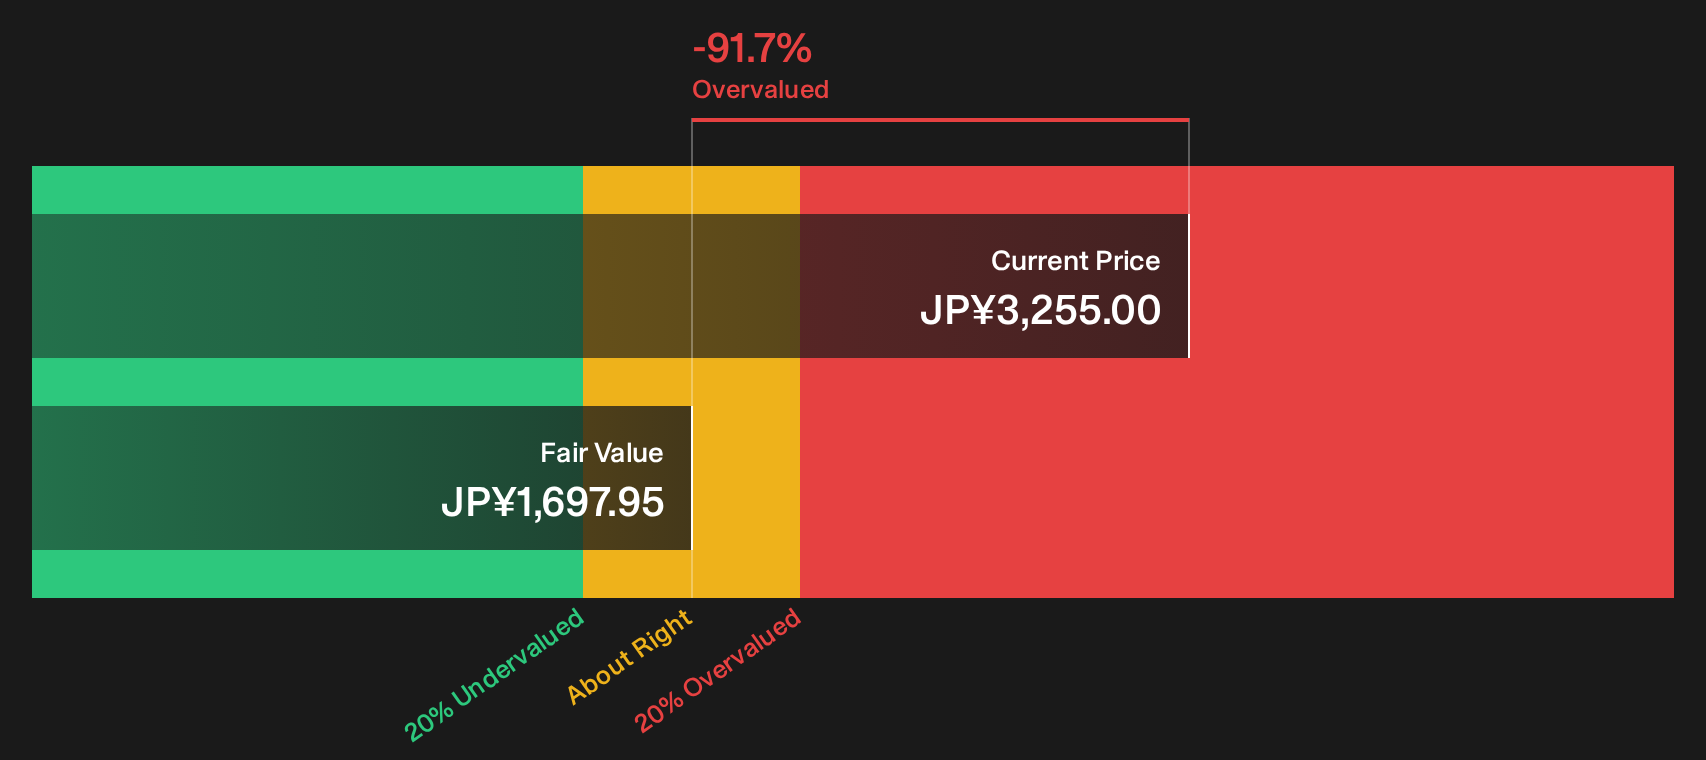
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hyakujushi Bank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Hyakujushi Bank is mixed, with both risks and rewards on the table, so move quickly, review the numbers, and weigh both sides through the 1 key reward and 2 important warning signs
Looking for more investment ideas beyond Hyakujushi Bank?
If Hyakujushi Bank has caught your attention, use that momentum. Put fresh ideas on your radar before the next wave of opportunities moves without you.
- Target potential mispricing by reviewing companies that screen as 18 high quality undervalued stocks and could merit a closer look on fundamentals.
- Strengthen your income focus by scanning resilient payers in the 20 dividend fortresses and pressure test how those yields fit your goals.
- Prioritise balance sheet resilience by checking the list of solid balance sheet and fundamentals (23 results) and see which businesses hold up best when conditions get tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com