
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 European Bank Stocks Investors May Prefer Over French Financial Shares
French sovereign stress has turned government bond markets into the main story, and that ripple effect is hitting financial stocks across Europe. When investors step back from French banks and insurers, capital often goes hunting for alternatives that still offer scale, liquidity and solid balance sheets. This article looks at three European large caps exposed to that shift and explains how the current market reset could matter for your portfolio decisions.
The stocks below are just a starting sample, and the wider screen on European non French financials surfaced 16 more large caps with similarly interesting setups that are not covered here. To identify and analyze those additional banks and insurers straight away, head into the European Non-French Banks and Insurers Benefiting from French Sovereign Stress screener.
Skandinaviska Enskilda Banken (OM:SEB A)
Skandinaviska Enskilda Banken plugs directly into the screener theme as a large Nordic lender that some investors see as a safer counterpart to French banks, with a broad corporate and private client franchise that could draw reallocations if French sovereign stress lingers.
"The expansion of AI initiatives across the bank is expected to enhance efficiency and productivity, positively impacting net margins over the medium to long term."
What happens to those margin gains if one quiet regulatory and tax pressure in Sweden and the Baltics moves in the wrong direction?
Skandinaviska Enskilda Banken is a universal Nordic bank spanning corporate, retail, investment and private banking. Revenue is led by Corporate & Investment Banking at SEK 27.7b, Business & Retail Banking at SEK 22.2b, Wealth & Asset Management at SEK 11.2b and Baltic operations at SEK 10.5b. Its market value is around SEK 457.6b.
If that risk dial starts to move, the full picture sits inside the full narrative for Skandinaviska Enskilda Banken, where AI upside, capital returns and regulatory pressure are all weighed.
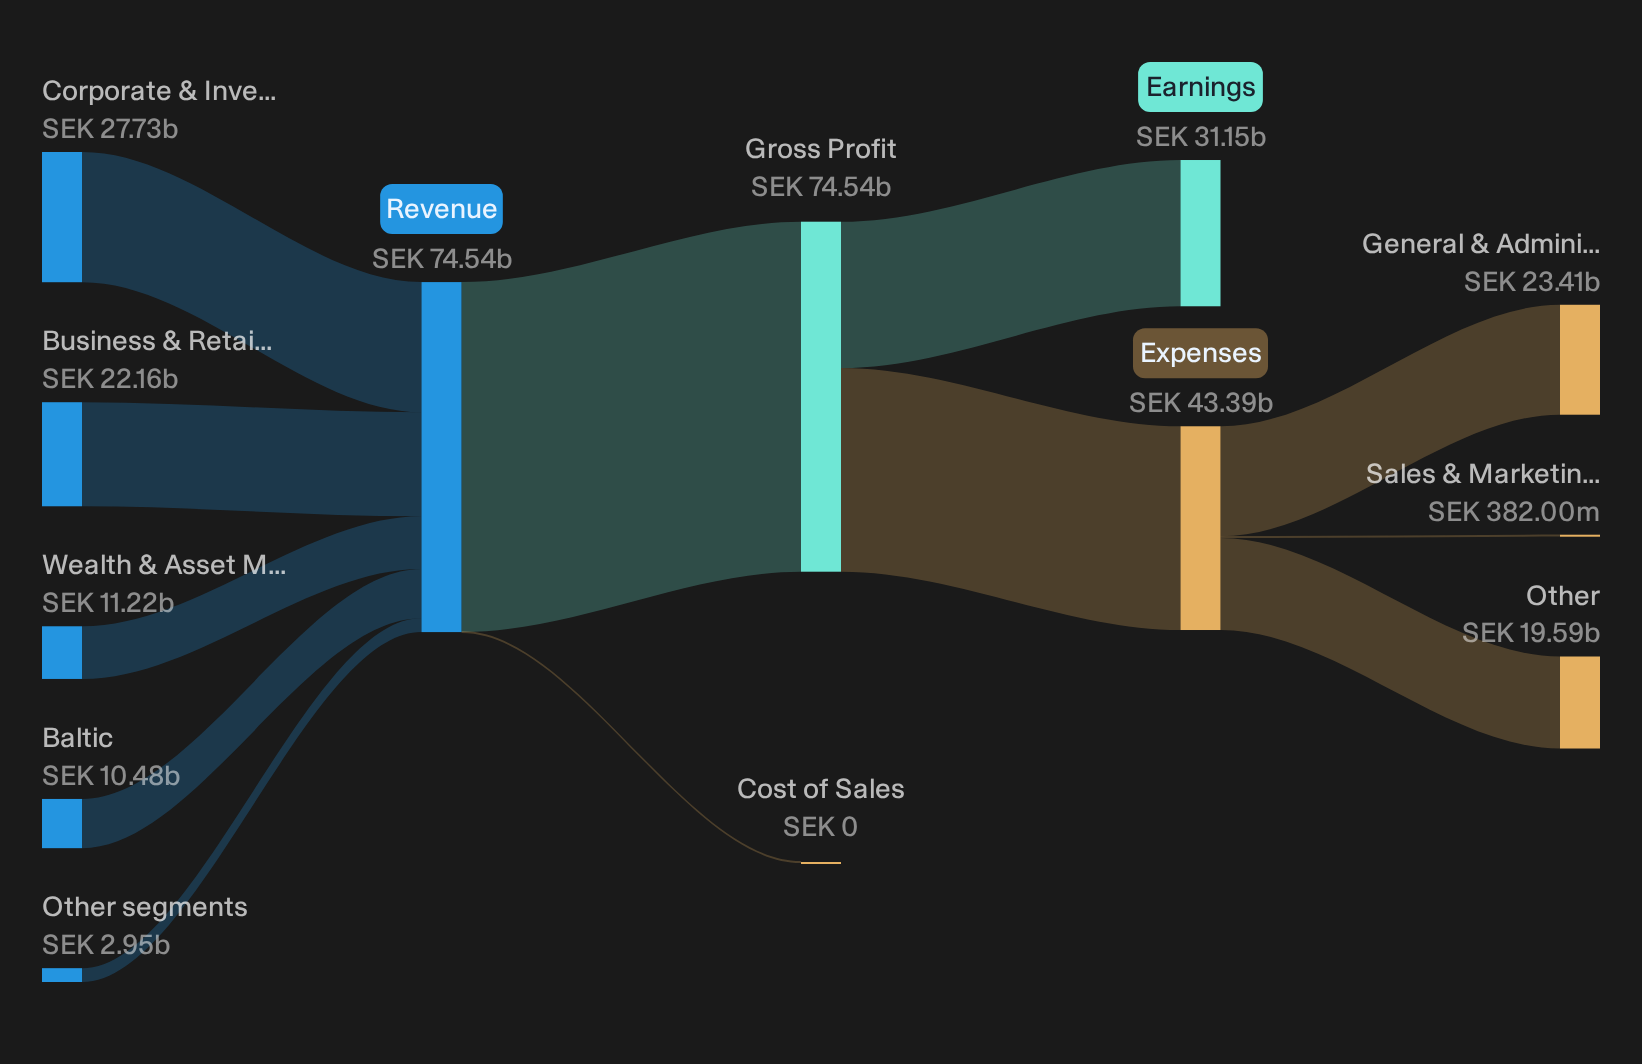
Swedbank (OM:SWED A)
Swedbank sits squarely in this screener as a large Nordic lender that some investors view as a safer way to get bank exposure if money moves out of French financials into more politically stable Sweden and the Baltics.
Swedbank AB is a universal bank focused on everyday lending, savings, payments and investment services for households and businesses, with revenue led by Swedish Banking at SEK 24.6b, Corporates & Institutions at SEK 17.9b, Baltic Banking at SEK 18.6b and smaller contributions from Group Functions and Premium & Private Banking, giving the stock a market value of about SEK 463b.
"Volume growth in core lending products, such as Swedish mortgages distributed through Swedbank’s own channels and broad based lending growth in Baltic Banking on both private and corporate sides, can underpin interest income and support earnings if credit quality and pricing discipline are maintained."
For investors watching Swedbank, a single unresolved pressure on its funding mix and loss buffers could be what really decides future returns.
That funding question is only the start, and the full narrative for Swedbank shows how Swedbank’s lending engine, capital stack and French stress link could be quietly decoupling expectations.

KBC Group (ENXTBR:KBC)
KBC Group brings a combined banking and insurance model in Belgium and Central and Eastern Europe to a screener that focuses on large non French financials with solid balance sheets, giving investors another way to think about where money might rotate as French risk stays in focus.
KBC Group runs a bancassurance model anchored in Belgium, where the Belgium Business segment produces about €7.4b of revenue, with further income from the Czech Republic at roughly €2.7b and international markets in Hungary, Bulgaria and Slovakia. The group is valued at about €52.1b.
"If KBC’s equity beta normalizes toward 1.0 (pushing Cost of Equity to approximately 8.15%), both model outputs drop significantly below the bottom of their sensitivity ranges."
For anyone eyeing KBC Group as a potential beneficiary of flows away from French banks and insurers, one unseen assumption could still reshape the whole reward story.
That hidden assumption is exactly what the full narrative for KBC Group unpacks, showing where KBC Group’s risk, capital and flow story could be quietly accelerating or stalling.

Seeking Alternatives Before The Crowd
Fresh ideas move first. Breakout stories gain momentum, laggards keep dropping and the best setups fly under the radar for now. Screen them while it matters and act now.
- Spot resilient cash generators before they are widely caught by the market by running your filters through the list of solid balance sheet and fundamentals (205 results).
- Hunt for reliable income opportunities with yields that could steady a portfolio using the curated group of 157 dividend fortresses.
- Track momentum at the frontier of computing by scanning the hand picked universe of 25 quantum computing stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com