
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Earnings Report Could Be A Key Test For Symbotic Stock (SYM)
- Symbotic is due to release financial results that are expected to show EPS of $0.16, which would be 69.81% lower than the same quarter last year, alongside consensus revenue expectations that point to nearly 25% growth over that period.
- Investors are weighing a rare mix for Symbotic: slowing earnings per share alongside strong top line expectations and a sizeable contracted backlog that highlights how warehouse automation demand and execution risk are pulling in different directions.
- We will now explore how Symbotic's expected EPS decline, alongside strong revenue estimates, could reshape the investment narrative around its automation platform.
Compare Symbotic's automation story with other robotics and warehouse plays by scanning our hand picked 93 robotics and automation stocks that are also tied to real world adoption and execution risk.
Symbotic Investment Narrative Recap
To own Symbotic, you need to believe warehouse automation keeps pushing forward and that the firm can turn its record US$22.4b backlog into predictable, profitable rollouts. The expected 69.81% drop in EPS to US$0.16, alongside nearly 25% revenue growth, puts execution timing in the spotlight rather than the demand story itself.
The key short term catalyst is whether the newer storage structure and faster deployments show up cleanly in upcoming quarters without more lumpiness. The biggest risk right now sits in project delays, customer concentration with Walmart, and higher CapEx and R&D spending compressing free cash flow if ramps slip.
The most relevant recent datapoint for this earnings setup is the contrast between Symbotic and Serve Robotics. Serve is dealing with revenue guidance cuts and heavy cash burn. In contrast, Symbotic is working from a sizeable contracted backlog and recent profitability. That difference matters when you think about how a softer EPS print is received.
Investors are essentially testing whether Symbotic behaves like a high burn automation story or a scaling platform with clearer revenue visibility. Strong demand signals from its backlog and software margins above 70% pull one way, while transition risk to the next generation architecture and concentrated exposure to Walmart pull the other.
Symbotic Long Term Assumptions And Valuation Setup
Symbotic's longer term story leans heavily on what the analyst models are baking in today rather than just the next quarter. The current consensus framework assumes revenue grows by 25.8% per year over the next three years, while profit margins move from 0.3% today to 3.0% in that same window. That is a big shift in how much profit each warehouse system is expected to generate once more projects are live and software and services scale.
On earnings, the gap between where Symbotic is today and where forecasts sit is wide. Analysts are modeling a move from US$8.2 million of earnings today to US$159.5 million by 2029, with earnings per share of US$0.99. That implies earnings increasing by roughly US$151 million within a few years. The spread between the most bullish forecast at US$515.7 million and the most cautious at US$113.3 million shows how much uncertainty investors are still pricing around execution, customer appetite, and the pace of deployments.
Valuation math in these reports also asks investors to accept a very different P/E profile for Symbotic over time. To line up with the consensus view, the stock would need to move from trading on about 713x current earnings to 79.8x the 2029 estimate, based on US$159.5 million of earnings on US$5.3b of revenue. That future multiple still sits well above the 24.6x P/E cited for the broader US machinery peer group. This means the market is being asked to treat Symbotic more like a high growth software or automation platform than a traditional industrial company.
All of this is being run through a discount rate just above 8%, which is how the analyst group gets from those 2029 building blocks back to a present day view of value. At a current share price of US$45.07, the consensus price target of US$62.86 implies a 28.3% higher level than where the stock trades now. The relationship between that implied upside, the very high starting P/E, and the spread in earnings expectations is what investors need to weigh when deciding how much of Symbotic's automation runway to factor into their own framework.
Symbotic's current analyst narrative points to about US$5.3b of revenue and US$159.5 million of earnings by 2029, built on an assumed 25.8% yearly revenue growth rate and an earnings increase of roughly US$151 million from US$8.2 million today.
Uncover how Symbotic's fair value indicates a 51% potential upside to its current price that may not last much longer.
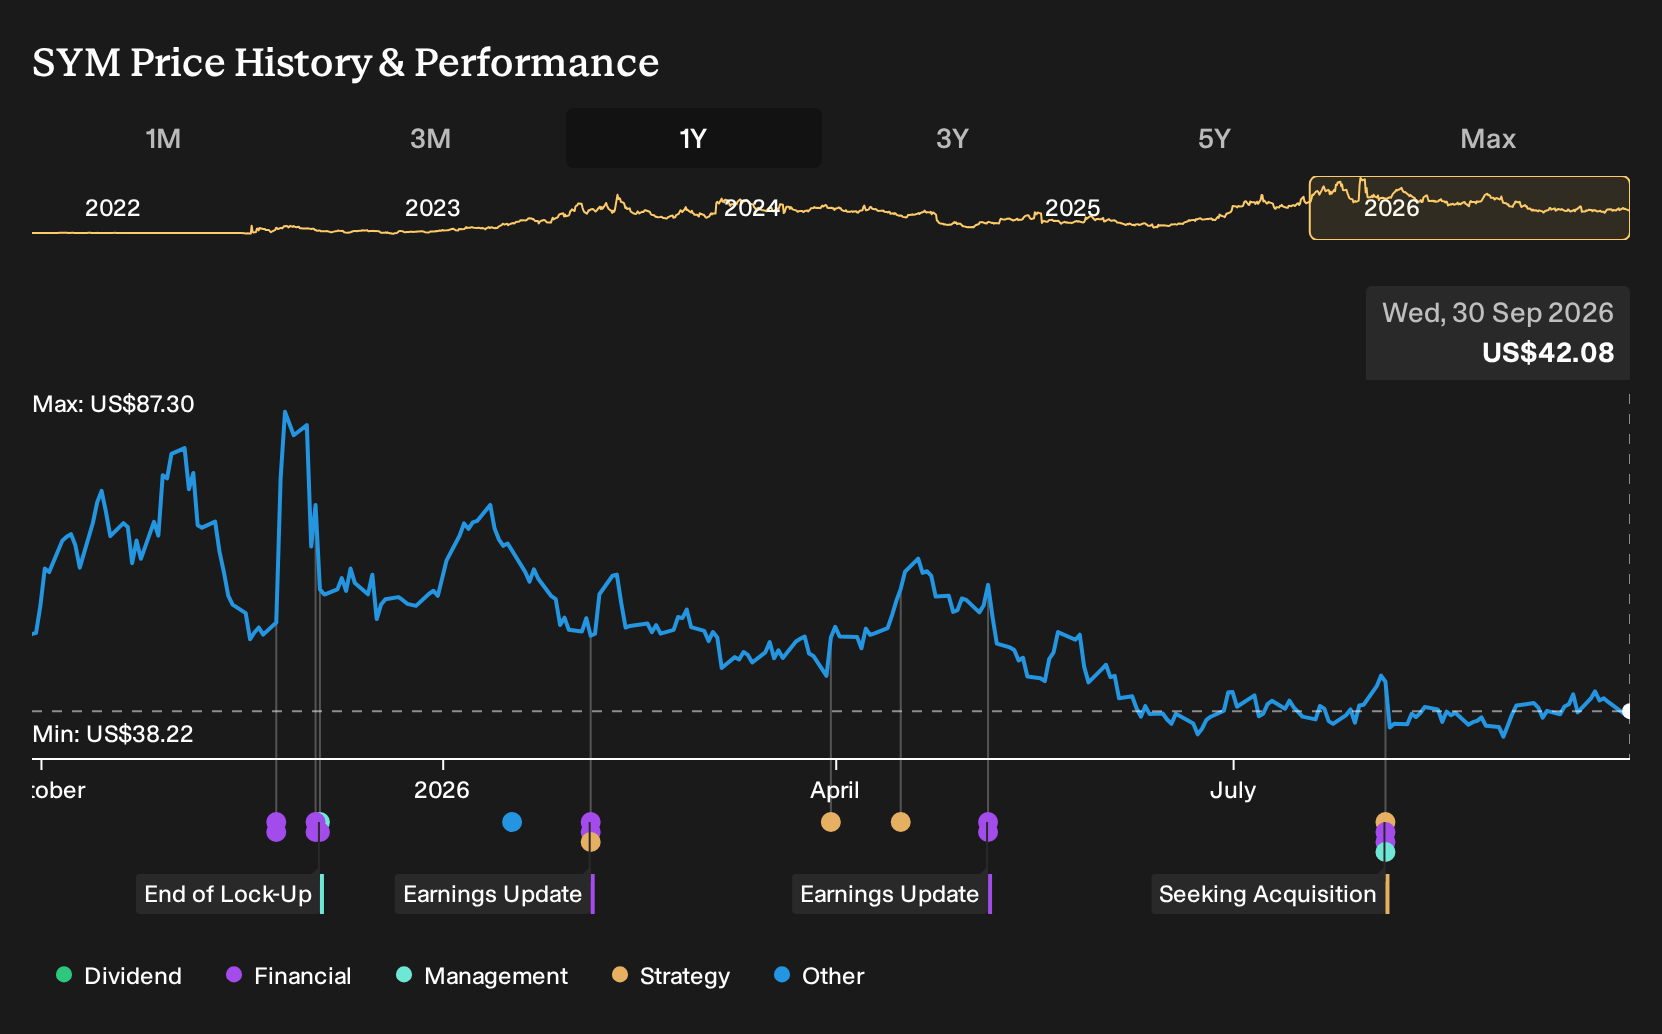
Exploring Other Perspectives
One alternate angle on Symbotic focuses heavily on customer concentration risk. The most cautious analysts were pencilling in about US$4.9b of revenue and US$114.2 million of earnings by 2029, which is far below the consensus path. That creates a more pessimistic backdrop for this EPS report and gives you a reason to compare several viewpoints before updating your own thesis.
Explore 5 other Symbotic fair value estimates, including one that suggests it could be worth just $44.62.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Symbotic research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Symbotic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Symbotic's overall financial health at a glance.
Looking For More Investment Ideas Beyond Symbotic?
If the Symbotic story has you thinking about position sizing and diversification, it can help to line it up against other stocks with very different risk and return profiles. The Simply Wall St Screener lets you do that quickly by filtering for specific traits that match how you like to invest.
- For investors who want potential upside without paying up for quality, start by scanning a focused group of 18 high quality undiscovered gems that pair strong fundamentals with limited market attention.
- If capital preservation and a steadier ride matter more to you than chasing every headline, filter for 31 resilient stocks with low risk scores that screen well on balance sheet strength and risk scores.
- Income focused investors can line up Symbotic beside yield driven opportunities by reviewing 7 dividend fortresses that combine payouts above 5% with an emphasis on resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com