
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Newmont (NEM) Could Be 31% Undervalued On Record Free Cash Flow And Gold Price Swings
Newmont (NEM) is back in focus after a sharp move in gold prices pulled the stock lower, even as the miner reported record free cash flow and kept major growth projects moving forward.
That pullback lines up with a 1-day share price return of down 1.49% and a 7-day share price move of down 6.65%, even though Newmont has delivered a 90-day share price gain of 18.86% and a 1-year total shareholder return of 35.45%. Shorter term momentum is cooling, while the longer record, including a 5-year total shareholder return of 142.72%, still reflects investors rewarding the company’s cash generation and project pipeline.
Compare Newmont's recent pullback and cash generation with a curated group of peers by scanning the 36 elite gold producer stocks now that gold price swings are back in the spotlight.
That mix of record free cash flow and a sharp pullback in Newmont raises a simple tension. Are you seeing a crack in the business, or just sentiment resetting while the valuation case is unchanged?
Most Popular Narrative: 31% Undervalued
At a last close of $115.34 against a widely followed fair value estimate of $168.00, Newmont screens as materially cheaper in that narrative. This view leans on higher margins, buybacks, and a richer project base to justify the gap.
The ongoing digitalization and automation of Newmont's core operations, combined with the deep technical talent bench and best-in-class asset reliability initiatives, is setting the stage for sustained productivity gains and production stability, materially improving long-term operating leverage and reducing earnings volatility.
See why 16 investors see Newmont as 31% undervalued.
Result: Fair Value of $168.00 (UNDERVALUED)
Still, Newmont’s reliance on gold pricing and exposure to lower ore grades at operations like Cadia and Peñasquito could quickly test this 31% undervaluation story.
Find out about the key risks to this Newmont narrative.
Another View: Newmont Through A Different Lens
The bullish $168.00 fair value story leans on analyst forecasts and narrative assumptions, but the SWS DCF model tells a different story. On that cash flow view, Newmont at $115.34 screens as overvalued versus an estimated future cash flow value of $96.78.
That gap shows how sensitive Newmont’s appeal can be to the inputs you trust most. If earnings play out closer to the DCF path than the optimistic scenario, today’s price could already be baking in a lot of the good news investors are hoping for.
Before relying on any single outcome, it helps to understand how that cash flow view is built in the first place. You can do this by walking through the Look into how the SWS DCF model arrives at its fair value..
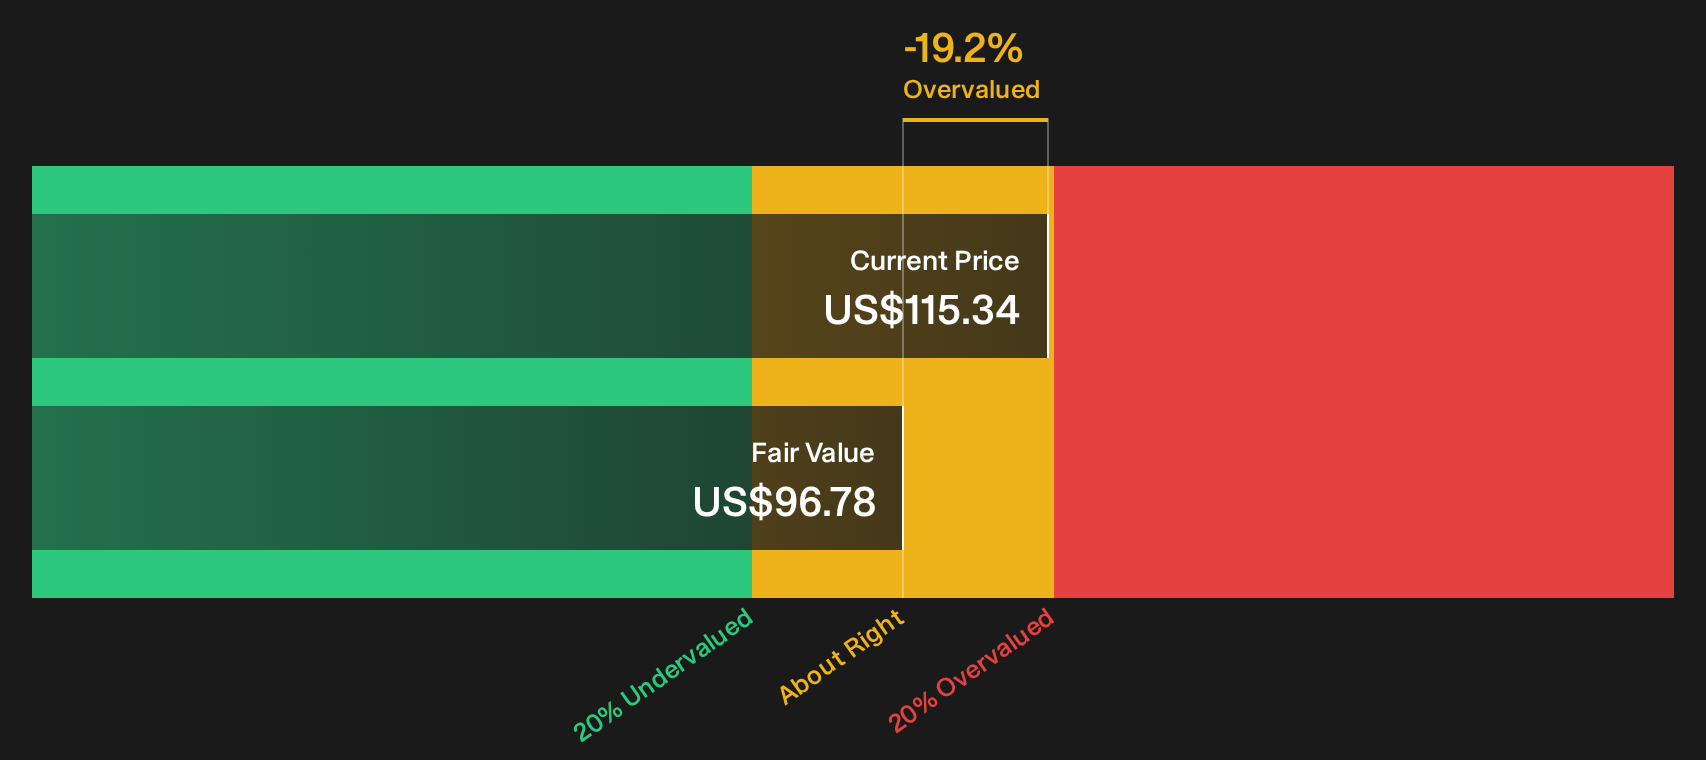
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Newmont for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views remain on whether Newmont is signaling opportunity or risk after these moves and ongoing fair value debates. Consider acting before sentiment shifts again by walking through both sides of the story, starting with 4 key rewards and 1 important warning sign.
Looking For More Ideas Beyond Newmont?
Round out your research by scanning other opportunities on Simply Wall St's screener so you do not miss ideas that fit your style and risk limits.
- Target steadier compounding by reviewing the 7 dividend fortresses that focus on robust income potential backed by sizeable yields.
- Hunt for mispriced opportunities through the 32 high quality undervalued stocks that highlight companies with quality fundamentals at compressed valuations.
- Prioritise resilience by filtering companies in the 31 resilient stocks with low risk scores so your next pick balances upside with measured downside exposure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com