
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Signet Jewelers Stock Could Change Following Profit Outlook Raise
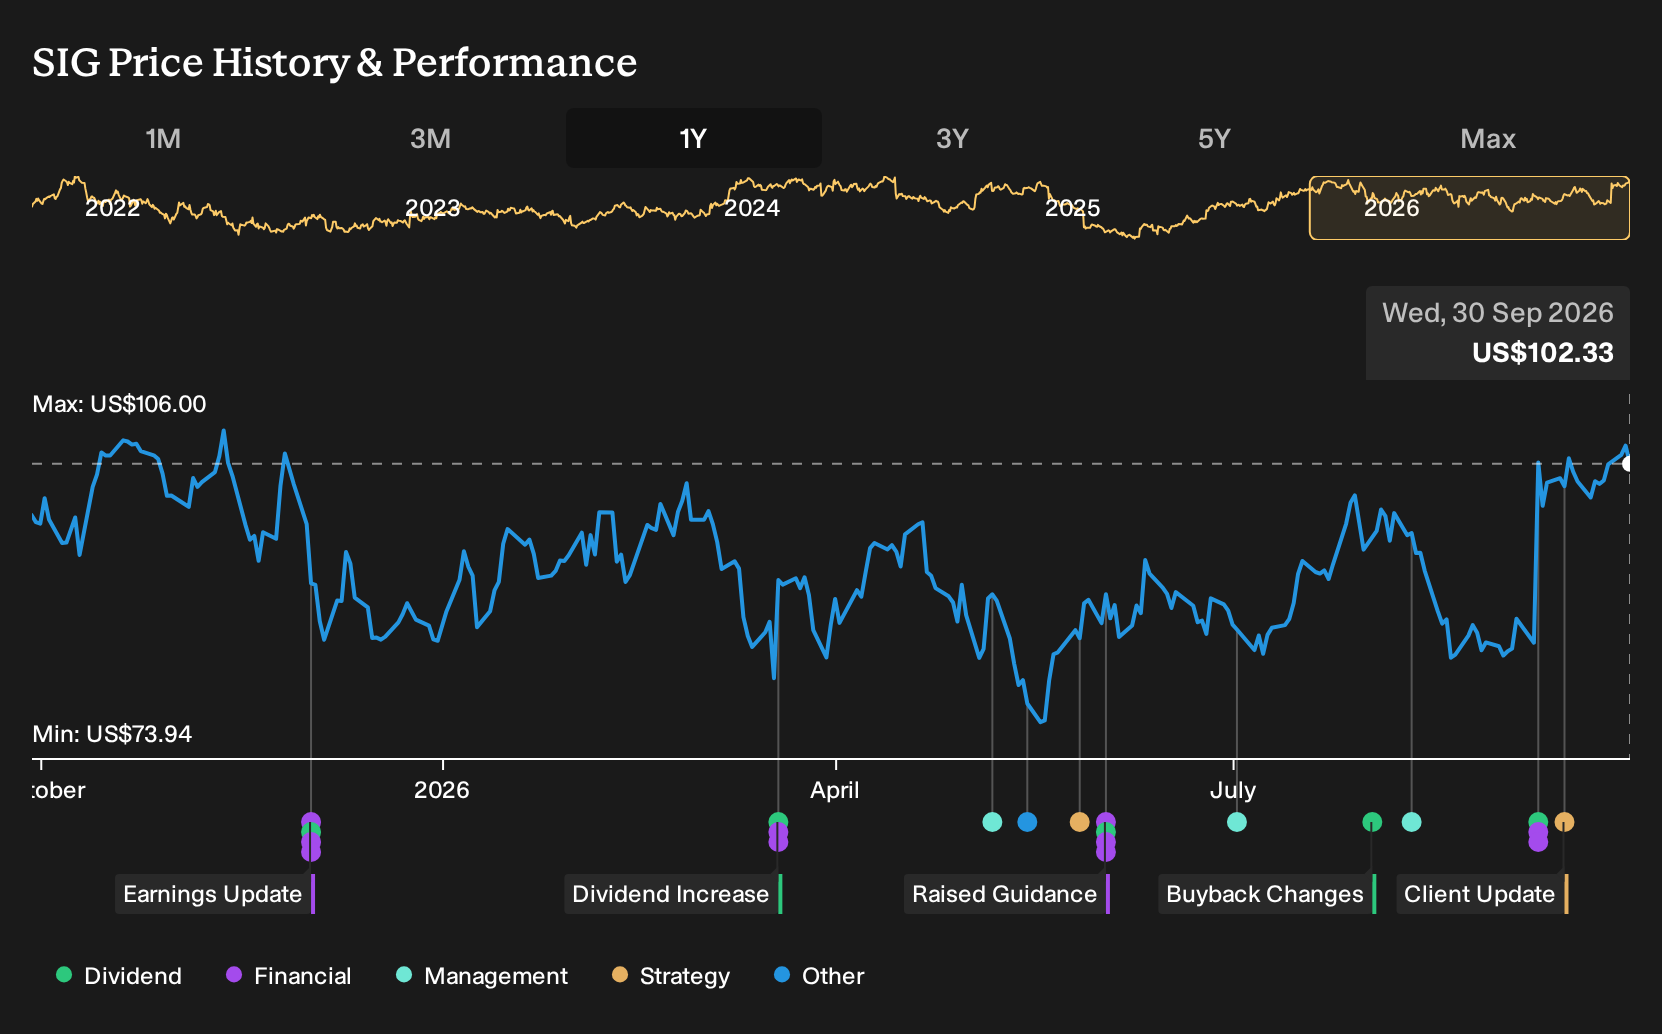
- Signet Jewelers recently raised its full-year profit outlook after reporting positive same-store sales, strong operating cash generation, and effective cost optimization, while also declaring a cash dividend of $0.35 with an ex-date that fell on 23 October 2026.
- The combination of higher guidance and a maintained dividend signals management confidence in Signet Jewelers' cash flow resilience despite tariff refunds, higher gold costs, and softer near-term guidance.
- Next, the focus turns to how Signet Jewelers' improved profit outlook reshapes its existing investment narrative around margins, cash flow, and growth.
Review how Signet Jewelers compares on cash generation and resilience, then evaluate it alongside a curated group of list of solid balance sheet and fundamentals (25 results)
Signet Jewelers Investment Narrative Recap
To own Signet Jewelers, you need to believe its mix of brick and mortar banners, online brands, and lab grown diamond offerings can keep pulling cash out of a slow growing category. The higher profit outlook and stronger same store sales support that case in the near term, even with softer third quarter guidance in the background.
The key short term catalyst is execution on merchandizing and omnichannel investments that support margins without leaning too hard on price increases. The biggest risk remains pressure on units and input costs, especially gold and tariffs, which could squeeze profitability if pricing power or tariff mitigation tactics lose effectiveness.
The most relevant announcement to watch alongside this guidance raise is the US$0.35 cash dividend with an ex date of 23 October 2026. A maintained payout, combined with higher earnings guidance, suggests management currently sees the balance between cash needs for operations, investment, and shareholder returns as manageable.
For you as an investor, that dividend is not just yield. It is a live test of cash generation resilience in the face of tariff related costs, higher gold prices, and uneven demand across fashion and bridal. If operating cash flow remains strong enough to fund both the dividend and ongoing omnichannel and service initiatives, it supports the existing catalyst story around margins and free cash flow.
What The New Guidance Implies For Signet Jewelers' Targets
Analysts currently sketch a future for Signet Jewelers that leans on modest top line expansion and firmer profitability rather than a big demand upswing. Consensus assumes revenue rises by 1.3% per year over the next three years, while profit margins edge from 5.2% today to 6.6% by around 2029 as merchandising, mix and cost controls do more of the heavy lifting.
On earnings, forecasts point to US$353.8 million today moving to US$470.7 million by about 2029, which is an increase of roughly 33%. That path is far from settled, since analyst views range from US$383.9 million on the cautious side to US$524.9 million at the high end, so you are dealing with a wide performance band rather than a single clean number.
Revenue expectations sit around US$7.1b by 2029, paired with that US$470.7 million profit figure, and backed by an assumed P/E multiple of 10.7x versus 11.4x today. In plain terms, for that scenario to line up, Signet Jewelers needs to grow earnings while the market is willing to pay a slightly lower earnings multiple. That puts more pressure on execution than on multiple expansion.
Signet Jewelers' narrative projects US$7.1b revenue and US$470.7 million earnings by 2029. This requires 1.3% yearly revenue growth and an earnings increase of roughly US$116.9 million from US$353.8 million today.
Uncover why Signet Jewelers' fair value indicates a 12% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One optimistic twist in the alternate Signet Jewelers story is the idea that lab grown diamonds could accelerate much faster than consensus expects. Bullish analysts were already modeling about US$7.3b of revenue and US$587.7 million in earnings by 2029 before this guidance raise. That is a far stronger path than the baseline. Use this guidance upgrade as a prompt to compare those more aggressive forecasts with your own view on how quickly lab grown demand and digital marketing can really scale, because the gap in opinions is wide and the news may eventually reshape both narratives.
Explore 3 other Signet Jewelers fair value estimates, including one that suggests a potential upside of as much as 109% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Signet Jewelers research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Signet Jewelers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Signet Jewelers' overall financial health at a glance.
Looking For More Investment Ideas Beyond Signet Jewelers?
If the Signet Jewelers story has sharpened your thinking on cash flow, dividends, and balance sheet strength, it can be useful to stress test that framework on other businesses. The Simply Wall St Screener lets you filter for different types of opportunities and apply the same discipline you just used here.
- If you want income to do more of the heavy lifting in your returns, scan for companies that look like potential income workhorses through a curated set of 6 dividend fortresses.
- If resilience and downside protection matter most to you right now, focus your attention on a 32 resilient stocks with low risk scores that may better match a capital preservation mindset.
- If you prefer to hunt where fewer investors are looking, broaden your watchlist with a 17 high quality undiscovered gems that combine solid fundamentals with lower profile coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com