
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Canadian Energy Stocks To Own In September 2026
Global markets have been reacting to fresh geopolitical risks around energy supplies, and policy makers have responded with new stimulus plans to support growth. That puts Canadian oil and gas stocks back in the spotlight for investors watching fuel prices and security of supply. This article walks through three companies from our Oil and Gas screener and explains how each could fit into a diversified portfolio in this kind of market.
The three stocks covered below are only a small sample from the Oil and Gas idea. The full screen surfaced 43 more companies with equally detailed stories that are not included here.
If you want to quickly identify and analyze the highest conviction oil and gas opportunities for your own watchlist, head straight into the Oil and Gas screener.
Cenovus Energy (TSX:CVE)
Overview: Cenovus Energy is an integrated Canadian producer that develops oil sands and heavy oil, extracts natural gas, and refines crude into fuels across North America and Asia.
Operations: Cenovus generates about CA$62.3b in revenue, mainly from Oil Sands and U.S. refining, with most sales in Canada and the United States.
Market Cap: CA$81.4b
Cenovus Energy matters in this Oil and Gas screen because its oil sands production and refining network directly connect crude extraction to end fuels that drivers, airlines, and shippers rely on. The next detail shows how management plans to grow that footprint further.
"The planned ramp up of multiple oil sands pads and 5 wells per year at West White Rose out to 2028 concentrates future growth into higher carbon, capital intensive barrels."
What happens to Cenovus Energy’s future returns if one unseen pressure quietly shifts the balance between higher output and tighter project economics?
That quiet pressure point is exactly where the story gets interesting, so read the full narrative for Cenovus Energy to see whether project economics are quietly compounding or stalling.

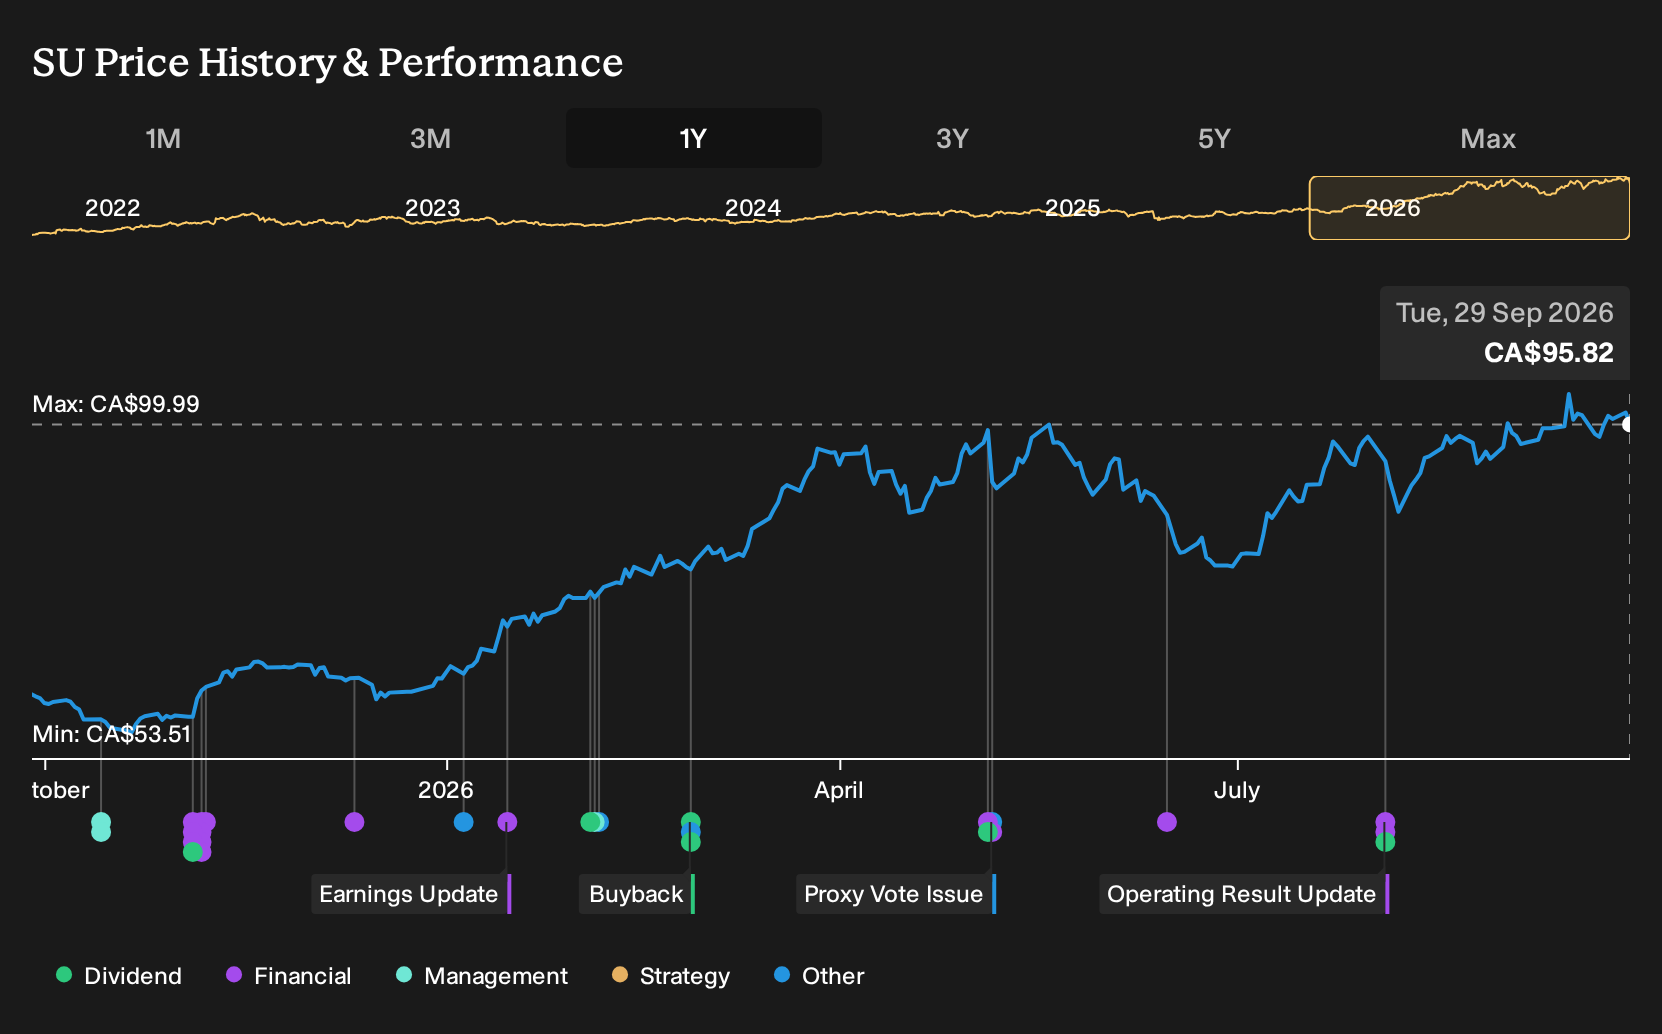
Suncor Energy (TSX:SU)
Overview: Suncor Energy is an integrated Canadian producer that pulls bitumen from Alberta oil sands and converts it into refined fuels for customers.
Operations: Suncor generates about CA$26.9b from Oil Sands, CA$36.8b from Refining and Marketing, and CA$2.5b from Exploration and Production activities.
Market Cap: CA$114.0b
Suncor Energy matters to this Oil and Gas screen because its oil sands production feeds directly into its refineries, tying upstream barrels to downstream fuel margins in a way few global producers can match.
"Reliance on very high utilization of existing oil sands and refining assets, including refinery runs consistently at or above 100% and upgrader utilization above 100%, leaves little unused capacity to offset unplanned outages, which could pressure volumes and compress margins if reliability slips from current record levels."
The real tension for Suncor now is what happens to cash generation if one key assumption about that tight operating window stops holding.
If that tight operating window is what worries you most, read the full narrative for Suncor Energy to see whether reliability risk is masking a stronger Suncor Energy story.
Whitecap Resources (TSX:WCP)
Overview: Whitecap Resources acquires, develops, and produces crude oil and natural gas in Western Canada, with upstream drilling and field programs driving output.
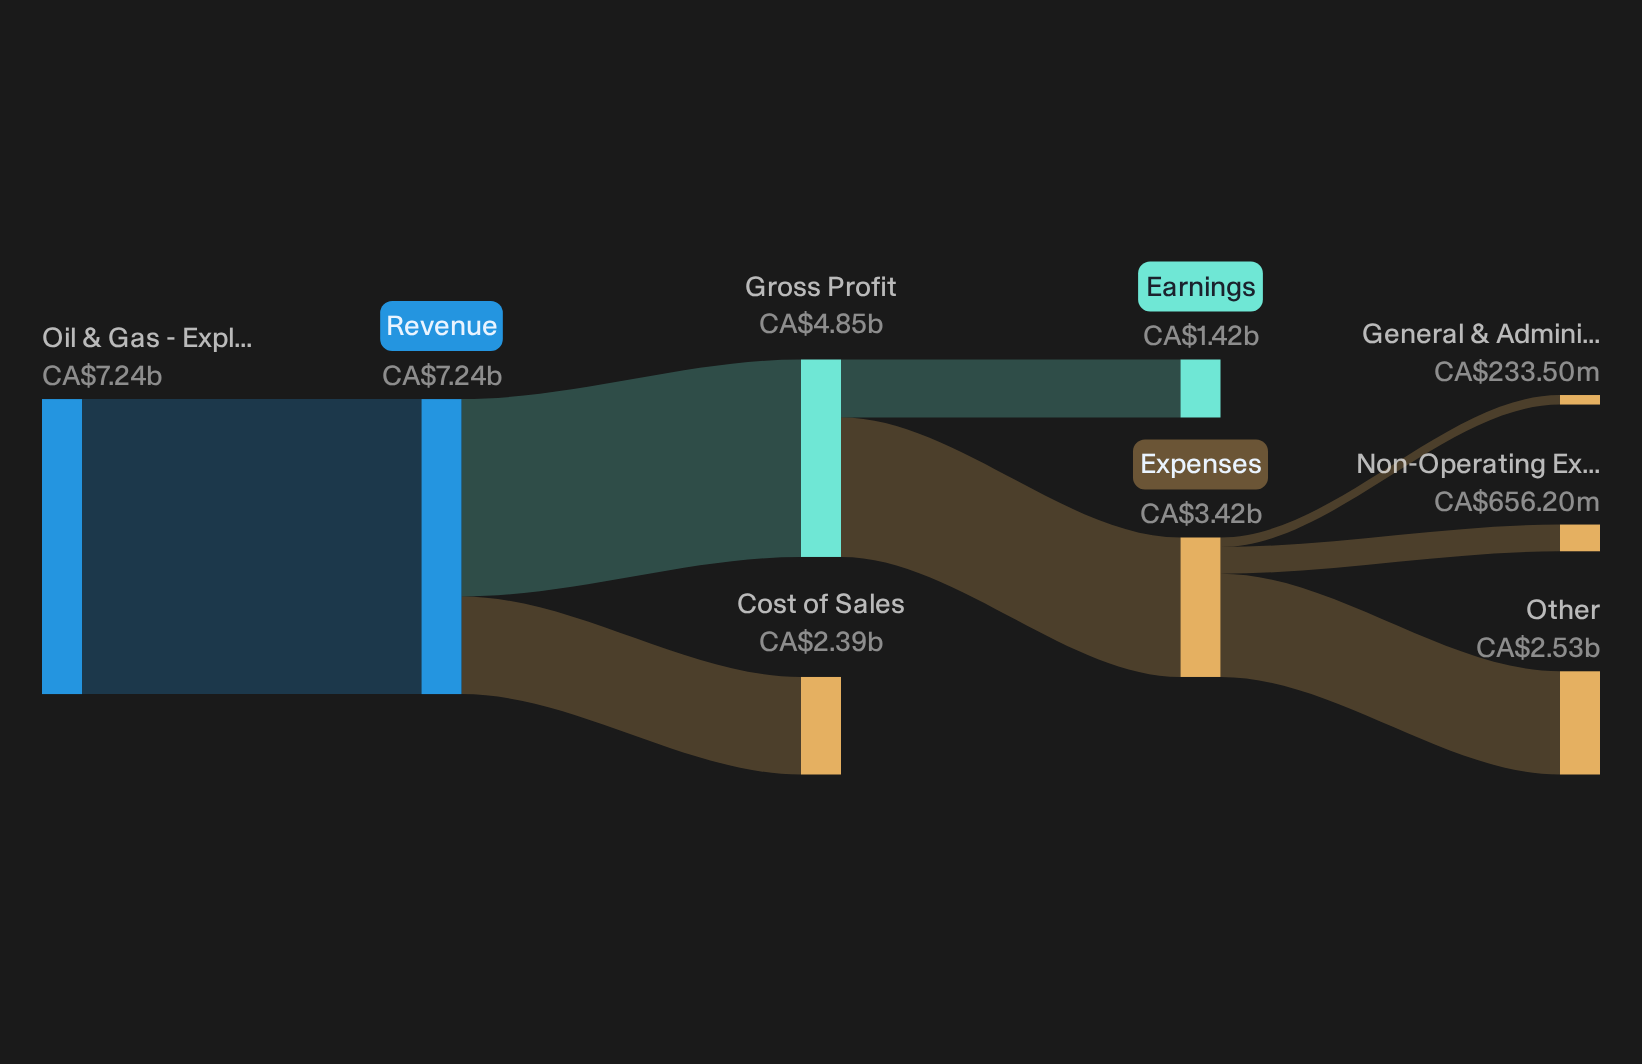
Operations: Whitecap Resources generates about CA$7.2b in revenue from oil and gas exploration and production activities, entirely from Canadian operations.
Market Cap: CA$21.9b
Whitecap Resources matters for an Oil and Gas screen because its wells, pads, and drilling programs directly convert Western Canadian reservoirs into saleable barrels and gas, giving you pure upstream exposure with meaningful scale.
"Successful integration of Veren assets is resulting in early operational synergies, cost reductions, and improved capital efficiency, which are expected to unlock further sustainable cost savings and margin expansion over the next 6 to 12 months, directly supporting higher future earnings and free cash flow."
The real test for Whitecap Resources now is what happens to its free cash flow profile if a single key assumption quietly shifts.
If that assumption is what you keep circling back to, read the full narrative for Whitecap Resources to see whether Whitecap Resources’ free cash flow story is quietly accelerating.
Seeking Fresh Alternatives Beyond Oil?
Markets move fast and new themes can gain breakout momentum while older ideas drop out of focus. Scan these fresh stock picks before the crowd and act now.
- Spot under the radar quality before momentum really starts flying by screening companies in the 9 high quality undiscovered gems while the window for early entries still matters.
- Target income streams as yields move and prices react by tracking high payout candidates in the 1 dividend fortresses before they stop looking cheap.
- Explore the next leg of the AI build out by focusing on infrastructure suppliers in the 89 AI infrastructure stocks while they remain under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com