
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Defensive Dividend Stocks Investors Are Weighing As Cash Yields Lose Appeal
Inflation just surprised to the soft side, rate expectations are wobbling and suddenly cash yields no longer feel like a sure thing. Some investors are wondering if dependable dividend payers exposed to this inflation story could offer a middle ground between pure safety and market upside. This article walks through three high dividend defensive stocks from our screener that appear well positioned for this backdrop and explains why each one may deserve a closer look now.
The three stocks highlighted below are just a sample, as the full high-dividend defensive screen surfaced 14 more U.S. companies with similar income profiles and equally compelling stories that are not covered here.
If you want to identify which of these income ideas best fits your risk profile and time horizon, go straight to the U.S. High-Dividend Defensive Stocks Competing with Cash Yields screener to filter, analyze, and focus on your highest conviction candidates.
DiamondRock Hospitality (DRH)
DiamondRock Hospitality brings a high-yield REIT twist to this defensive income screen, tying hotel cash flows to a macro setup where easing rate pressure can make equity income feel more compelling than sitting in cash.
DiamondRock Hospitality is a self-advised hotel REIT owning 34 premium properties with 9,400 rooms, generating about US$1.1b from hotel ownership in the United States and carrying a market value near US$2.6b.
"The acceleration of remote and hybrid work models continues to weaken business travel growth, creating persistent risk to DiamondRock’s future occupancy rates and revenue, particularly as first-quarter business transient demand improvement is unlikely to offset this long-term structural decline."
What happens to DiamondRock Hospitality’s income appeal depends heavily on how one less visible pressure on future cash generation unfolds.
That cash flow pressure is only part of the story, and the full narrative for DiamondRock Hospitality maps how DiamondRock Hospitality could turn today’s hybrid work drag into tomorrow’s misunderstood opportunity.

MGE Energy (MGEE)
MGE Energy is a regulated utility rooted in Madison, Wisconsin, supplying electricity and natural gas to about 170,000 customers. This aligns with the screener’s defensive, cash-generative utility theme.
The group earns around US$540 million from electric operations, US$252 million from gas and US$46 million from non regulated energy, offset by US$69 million of consolidation adjustments, all in the United States. MGE Energy’s market value is about US$2.6 billion.
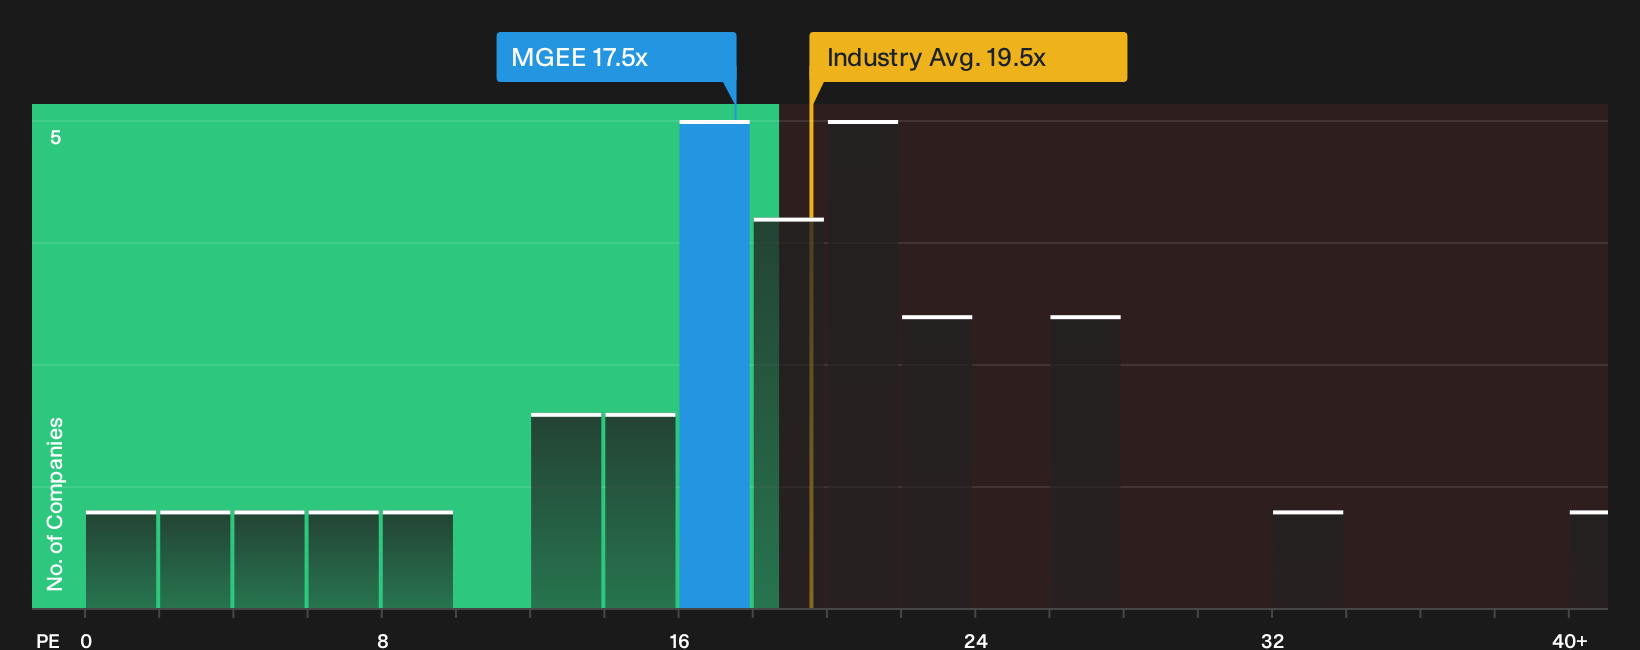
For investors comparing dividend stocks with cash, MGE Energy combines regulated utility stability, a long record of dividend increases and a P/E of 17.5x that sits below both the broader market and its industry. The key test will be how one pressure on free cash flow plays out against that defensive earnings profile.
That free cash flow question is exactly what the analysis report for MGE Energy reveals, including how MGE Energy’s dividend profile could react if that pressure accelerates or eases.
Archer-Daniels-Midland (ADM)
Archer-Daniels-Midland taps into the screener’s defensive income theme through its global food and feed footprint, giving investors exposure to essential nutrition demand while tying cash generation to a mix of traditional processing and higher value ingredients.
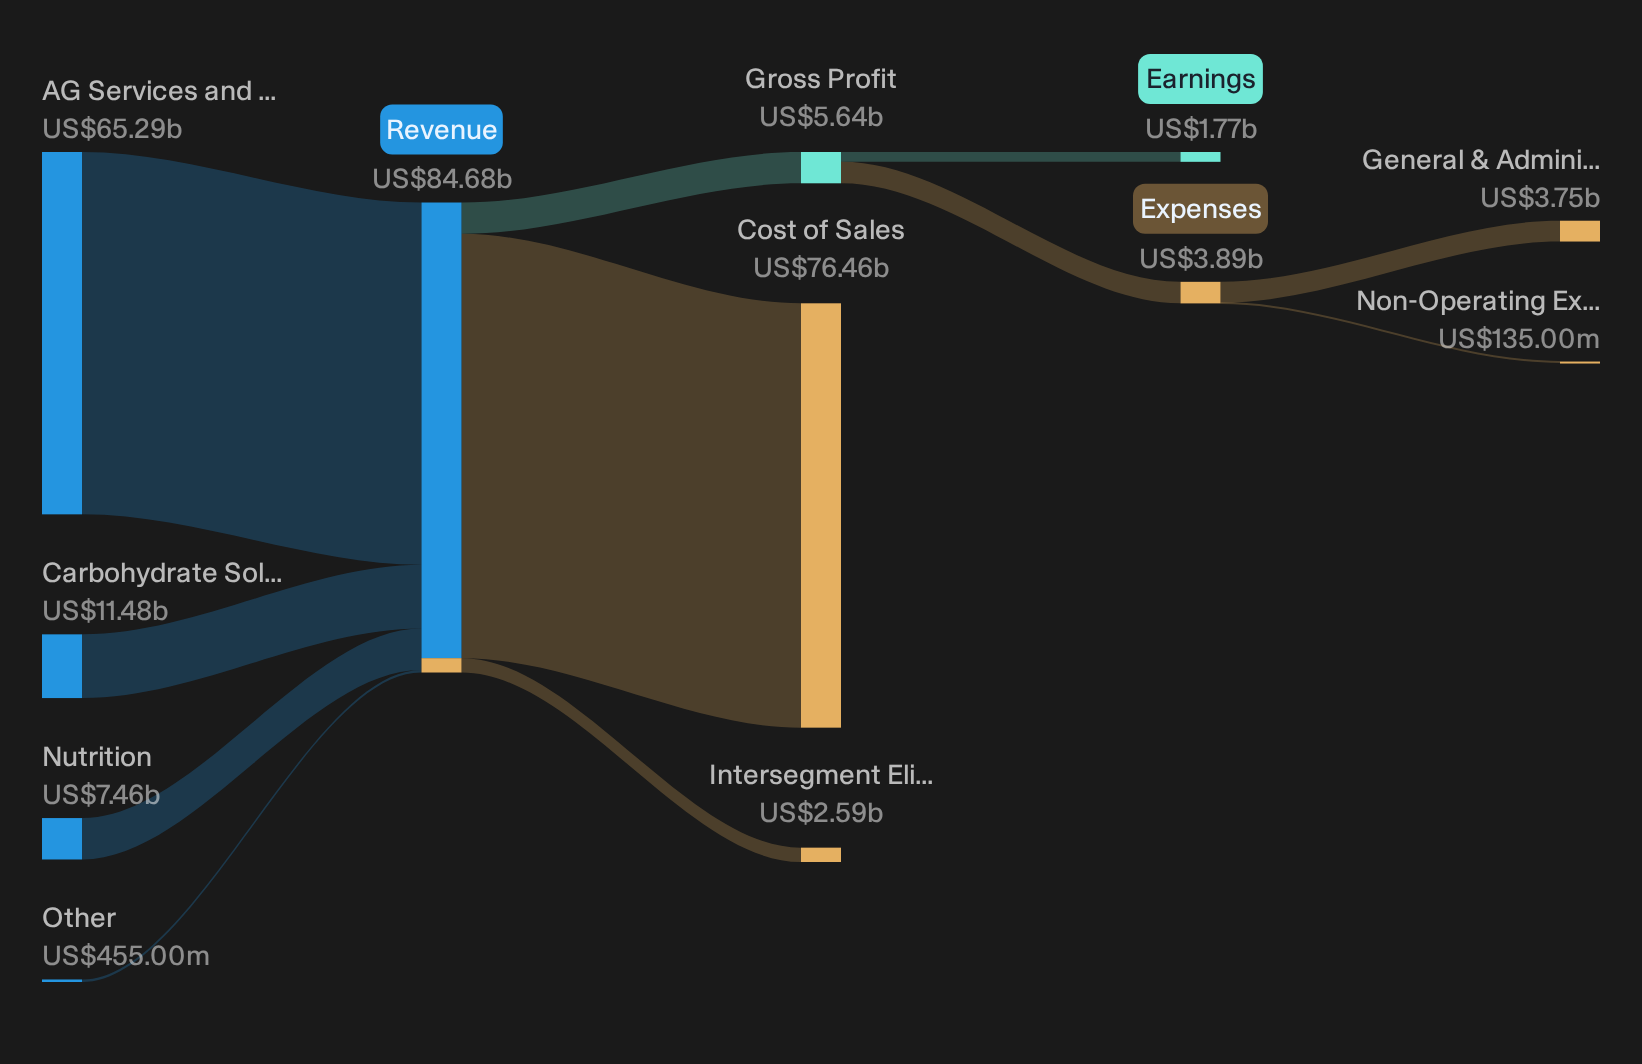
ADM runs a broad agribusiness, with Ag Services and Oilseeds producing about US$65.3b of revenue, Carbohydrate Solutions US$11.5b, Nutrition US$7.5b and Other US$455 million, partly offset by US$2.6b of intersegment eliminations. The stock carries a roughly US$38.7b market cap.
"Policy clarity and government support for biofuels, including the 45Z production tax credit that Archer-Daniels-Midland now expects to contribute about US$250 million in 2026, together with favorable blending mandates and domestic feedstock incentives, are expected to support crush economics and feed into revenue and earnings."
What investors really need to watch is how one less visible swing factor ultimately shapes ADM’s margin profile and dividend headroom.
That swing factor is exactly what the full narrative for Archer-Daniels-Midland unpacks, showing how the income story for Archer-Daniels-Midland could change if that margin lever quietly moves in its favor.
Seeking Alternatives Before Momentum Flies
Fresh ideas tend to move first. Slow research often gets caught flat footed while prices start breaking out and momentum builds under the radar. For those who want exposure earlier in a move, it can be important to identify potential opportunities before they become widely followed.
- Identify potential income engines with durable balance sheets by zeroing in on a curated list of solid balance sheet and fundamentals (25 results) before the broader market re-prices quality and yields begin to adjust.
- Consider structural demand shifts by scanning a focused 39 power grid technology and infrastructure stocks while grid upgrades, electrification and AI-driven loads may still be treated as a legacy story.
- Monitor monetary themes by filtering a targeted 36 elite gold producer stocks while some producers remain less followed and gold-linked cash flows are still being reassessed in light of evolving currency concerns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com