
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Warehouse Group (NZSE:WHS) Stock Eyes Recovery As Dividend Stays Suspended
The Warehouse Group stock comes into this result bruised but not broken. The share price is up about 5.8% over the past week and roughly 17.6% over three months, yet still soft over 30 days. That sets the stage for a sentiment test rather than a victory lap.
The headline is a return to profit and cash discipline, not a sales story. Operating profit reached NZ$22.6m with adjusted net profit after tax of NZ$13.5m, and free cash flow of NZ$79m helped cut net debt to NZ$17m. The sting is a suspended final dividend, which forces investors to weigh recovery against income sacrifice.
Is Warehouse Group starting to look stretched on a 19.5x P/E, or are analysts correct about the implied upside and potential earnings rebound story? Compare the current share price to our valuation analysis for Warehouse Group.
FY 2026 Earnings Summary
- Revenue (FY 2026 vs FY 2025, trailing 12 months): NZ$3,027.6m vs. NZ$3,086.7m (top line slightly lower year on year)
- Net Income (Excl. Extra Items, FY 2026 vs FY 2025, trailing 12 months): NZ$11.2m profit vs. NZ$2.8m loss (returned to positive earnings)
- Basic EPS (FY 2026 vs FY 2025, trailing 12 months): NZ$0.0035 per share vs. NZ$0.0080 loss per share (moved back into positive territory)
- Same Store Sales Growth (FY 2026, Half 1 vs FY 2025, Half 2): +0.5% vs. prior period decline (underlying store performance slightly ahead)
Prefer clear visuals over scrolling through paragraphs of figures on Warehouse Group? See the full financial picture, including a concise view of its recent earnings recovery story, in the interactive company report for Warehouse Group.
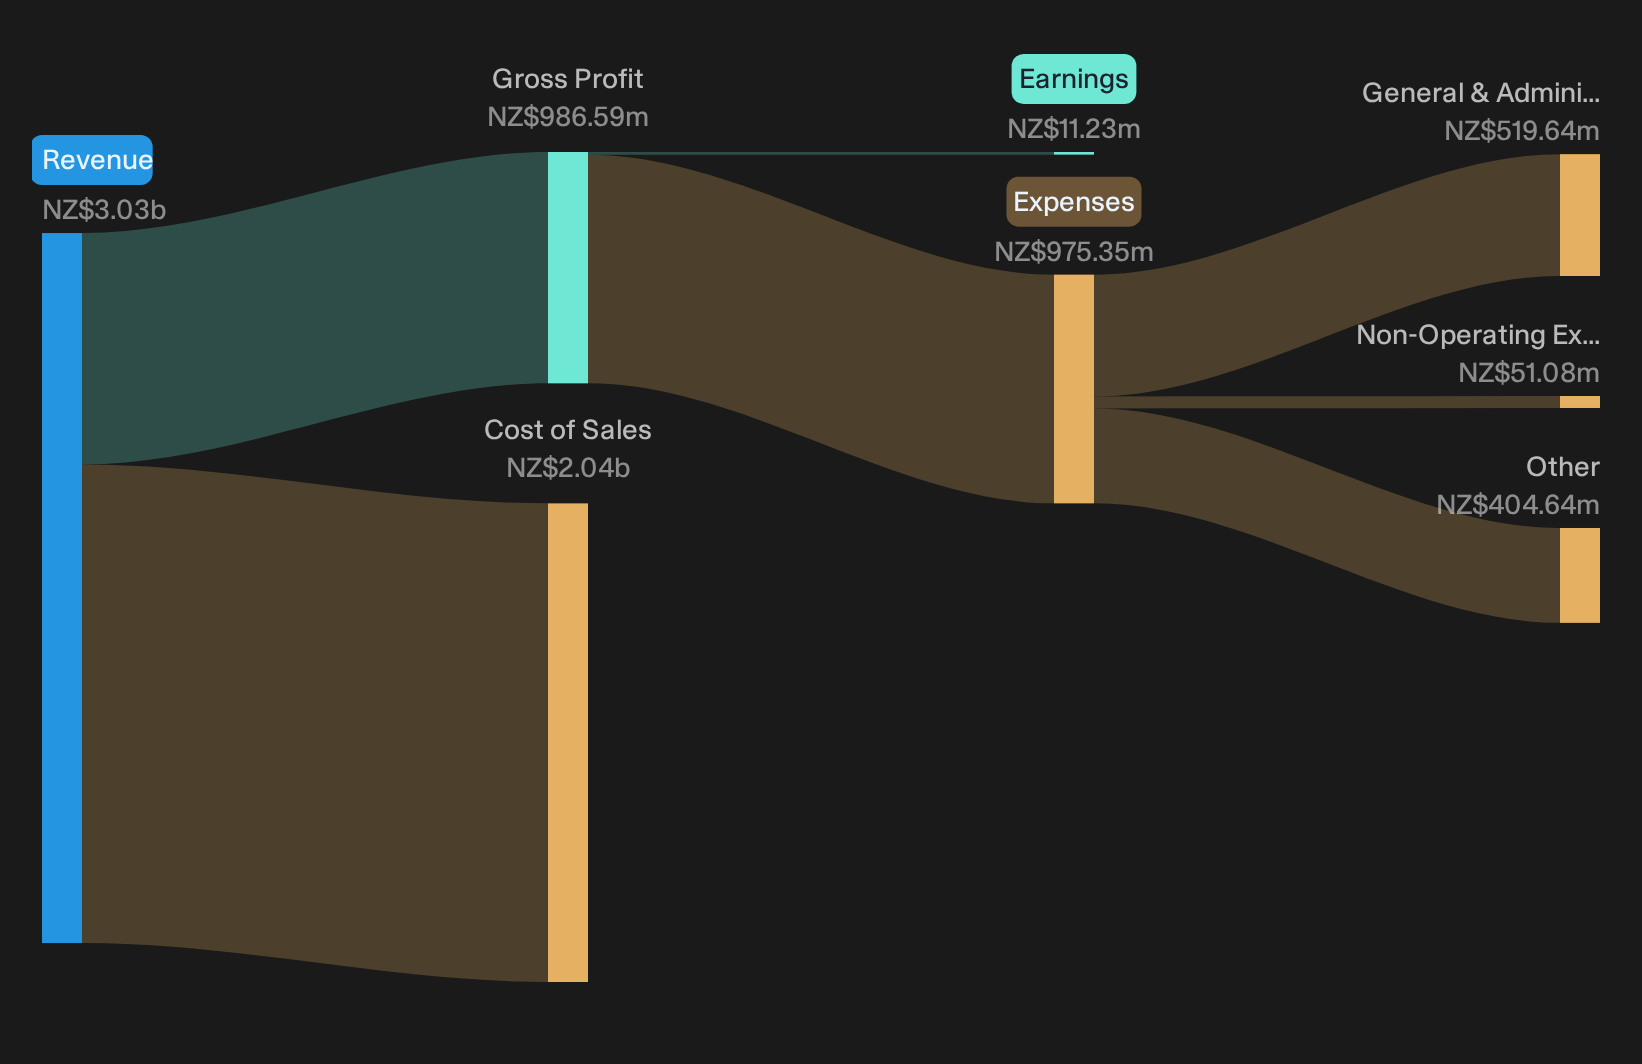
Warehouse Group bulls focus on profit and cash
Bulls argue Warehouse Group is finally proving that cost and inventory work can rebuild earnings, even without strong sales growth. The latest year goes some way to backing that up. Sales of just over NZ$3.0b are slightly softer, yet operating profit has lifted to NZ$22.6m and adjusted NPAT to NZ$13.5m. That shift, alongside gross margin at 32.6% and cost of doing business trimmed to 31.8% of sales, shows the cost reset is flowing through the income statement. Cash tells the same story. Operating cash flow of NZ$194m and free cash flow of NZ$79m have cut net debt to NZ$17m. Store level progress is uneven, but Warehouse Stationery on a 7% operating margin and Noel Leeming at 2.1% indicate the margin playbook is working in parts of the group.
Bear case tests dividend, sales and category risks
Bears worry the turnaround rests on cost cutting while sales stall and income investors walk away. Parts of the result support that caution. Group revenue is lower and comparable 52 week sales are broadly flat, which fits the concern that new stores and range work are not yet lifting the top line. The Warehouse banner still reports an operating loss of NZ$7.5m despite better Q4 gross margin, so the largest chain remains unfinished business. Suspension of the final dividend underlines that cash is being kept inside the business rather than paid out. Inventory metrics are cleaner, with stock down NZ$37.9m and aged stock reduced, but provisions are now NZ$18.9m. That signals residual clean up costs while the merchandising reset in home and apparel is still working through.
Reveal whether Warehouse Group's margin repair and cash generation are changing analyst conviction, or if the flat sales and dividend pause are keeping a lid on expectations by checking the consensus price target analysis for Warehouse Group.
Stay Ahead With Simply Wall St
If Warehouse Group's return to profit and focus on cash has your attention, register for free with Simply Wall St and add it to a Watchlist to track price against fair value and watch for your preferred entry point. Once you own shares, keep control of the bigger picture by using the Portfolio Command Center to cut through noise and surface only the key developments that matter to your holdings. For longer term decisions, tap into broader investor thinking through the Community and see how others are interpreting the same data. By surfacing hidden catalysts and risks early, Simply Wall St helps you move faster and stay ahead of the market.
Seeking Alternatives Before The Crowd?
Fresh ideas keep moving while attention stays locked on Warehouse Group. Some themes could be setting up for a breakout or quietly dropping under the radar for now, so consider exploring them sooner rather than later.
- Spot potential momentum leaders early by scanning curated 617 high quality undiscovered gems that may still be flying under most radars, before sentiment shifts and pricing moves away from you.
- Target resilient cash generators by reviewing the hand picked list of solid balance sheet and fundamentals stocks (205 results) while they are still priced for caution, not confidence.
- Track demand tied to critical resources by checking the focused 35 best rare earth metal stocks before attention floods the sector and the most attractive entry points change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com