
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Essentials Expansion Might Change The Case For Investing In Hyatt Stock (H)
- Hyatt Hotels has expanded its Essentials Portfolio across the United States, adding new Hyatt Place, Hyatt House, Hyatt Studios, Hyatt Select, Caption by Hyatt, and Unscripted by Hyatt properties in regional, coastal, business, and extended stay locations, and has also appointed Amar Lalvani as its first Chief Creative Officer.
- The broader rollout of Essentials brands into secondary and tertiary U.S. markets gives Hyatt Hotels another way to pursue an asset light, fee driven model, while a dedicated Chief Creative Officer concentrates on keeping the portfolio differentiated for guests and owners.
- We will look at how Hyatt Hotels' investment narrative is shaped by the Essentials Portfolio expansion and the new creative leadership focus.
Scan beyond Hyatt Hotels and see how other lodging and travel stocks are positioning for fee driven growth with our hand picked 17 high quality undiscovered gems in the sector.
Hyatt Hotels Investment Narrative Recap
To own Hyatt Hotels, you need to believe in a hospitality platform that leans into an asset light, fee driven model and a broad mix of brands. The Essentials Portfolio build out, especially in secondary and tertiary U.S. markets, fits that story but does not fundamentally change the near term focus on stabilizing margins after a year where profit quality was affected by one off items and thinner net margins.
The immediate swing factor still looks like booking behavior and RevPAR trends, particularly in upscale U.S. segments. A key risk is that weaker demand or economic volatility keeps interest coverage tight and delays payoff from the development pipeline. Construction cost inflation and any slowdown in new openings could also stretch the timeline for better earnings.
The appointment of Amar Lalvani as Hyatt Hotels’ first Chief Creative Officer sits closest to this Essentials expansion. A clearer creative lead across Hyatt Place, Hyatt House, Hyatt Studios, Hyatt Select, Caption by Hyatt, and Unscripted by Hyatt can help keep these flags distinct for both owners and guests, which matters when fees, not bricks and mortar, drive most of the economics.
For catalysts, the relevance is straightforward. A cohesive creative vision can support price discipline, owner interest, and loyalty engagement in the World of Hyatt program as more midscale and extended stay hotels come online. Execution risk is that the creative refresh does not translate into stronger booking trends at a time when analysts already expect meaningful earnings growth and the stock trades on a relatively rich P/S multiple.
Hyatt Hotels’ analyst narrative points to forecast revenues of US$8.5b and earnings of US$590.4m by 2029. This implies annual revenue growth of 35.4% and an earnings swing of about US$624.4m from a current loss of US$34.0m to the projected profit level.
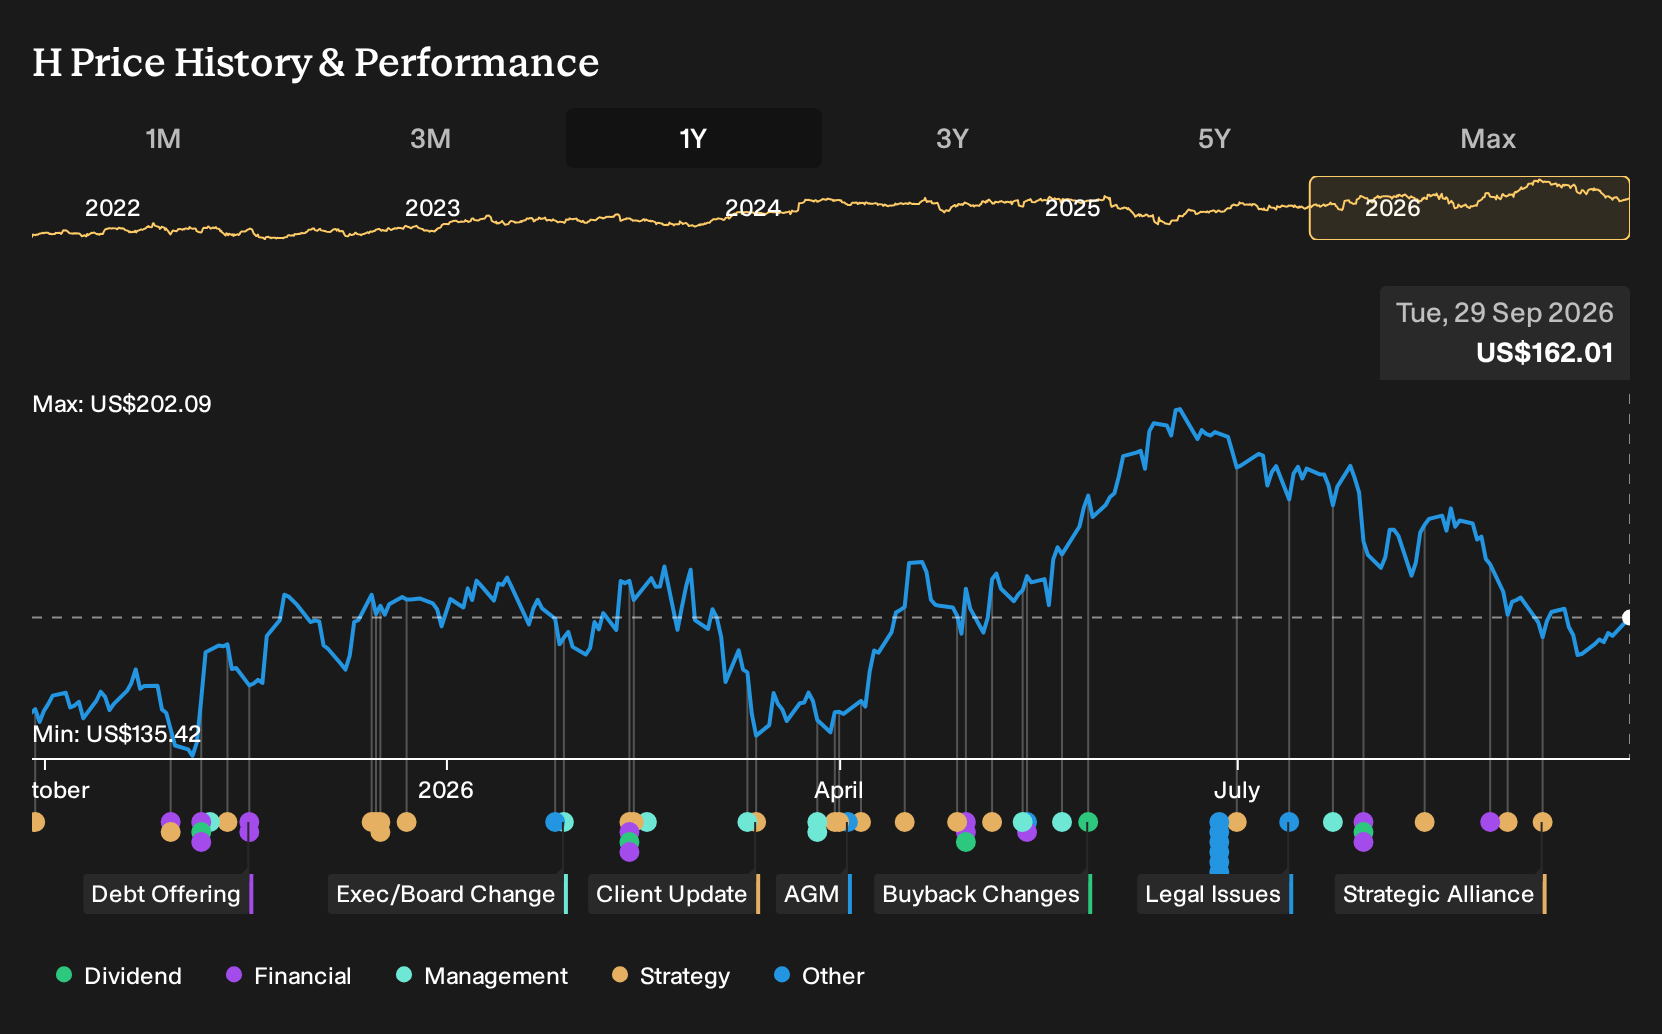
Uncover why Hyatt Hotels' fair value indicates a 22% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate take on Hyatt Hotels focuses less on creative leadership and more on timing risk in the pipeline. The most bearish analysts were penciling in about US$8.7b of revenue and US$497.0m of earnings by 2029 before this news. That is meaningfully lower than consensus, so consider using this expansion and the new Chief Creative Officer appointment as a prompt to compare several viewpoints and decide which story you find more convincing.
Explore 2 other Hyatt Hotels fair value estimates, including one that suggests it could be worth just $160.85.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Hyatt Hotels research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Hyatt Hotels. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hyatt Hotels' overall financial health at a glance.
Looking For More Investment Ideas Beyond Hyatt Hotels?
Once you have a view on Hyatt Hotels, it can help to benchmark that thesis against a broader watchlist of potential opportunities using the Simply Wall St Screener.
- If you are hunting for quality at a reasonable price, scan across our curated set of 32 high quality undervalued stocks that combine strong fundamentals with more modest expectations baked into the share price.
- For readers who care most about resilience, stress test your portfolio candidates against our 32 resilient stocks with low risk scores that focus on companies with lower risk profiles.
- If you want to spot potential outliers before the crowd, broaden your research with a 17 high quality undiscovered gems that highlight businesses with solid fundamentals that are less widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com