
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Comes Next For ZIM After 123% Was The Harder Bet
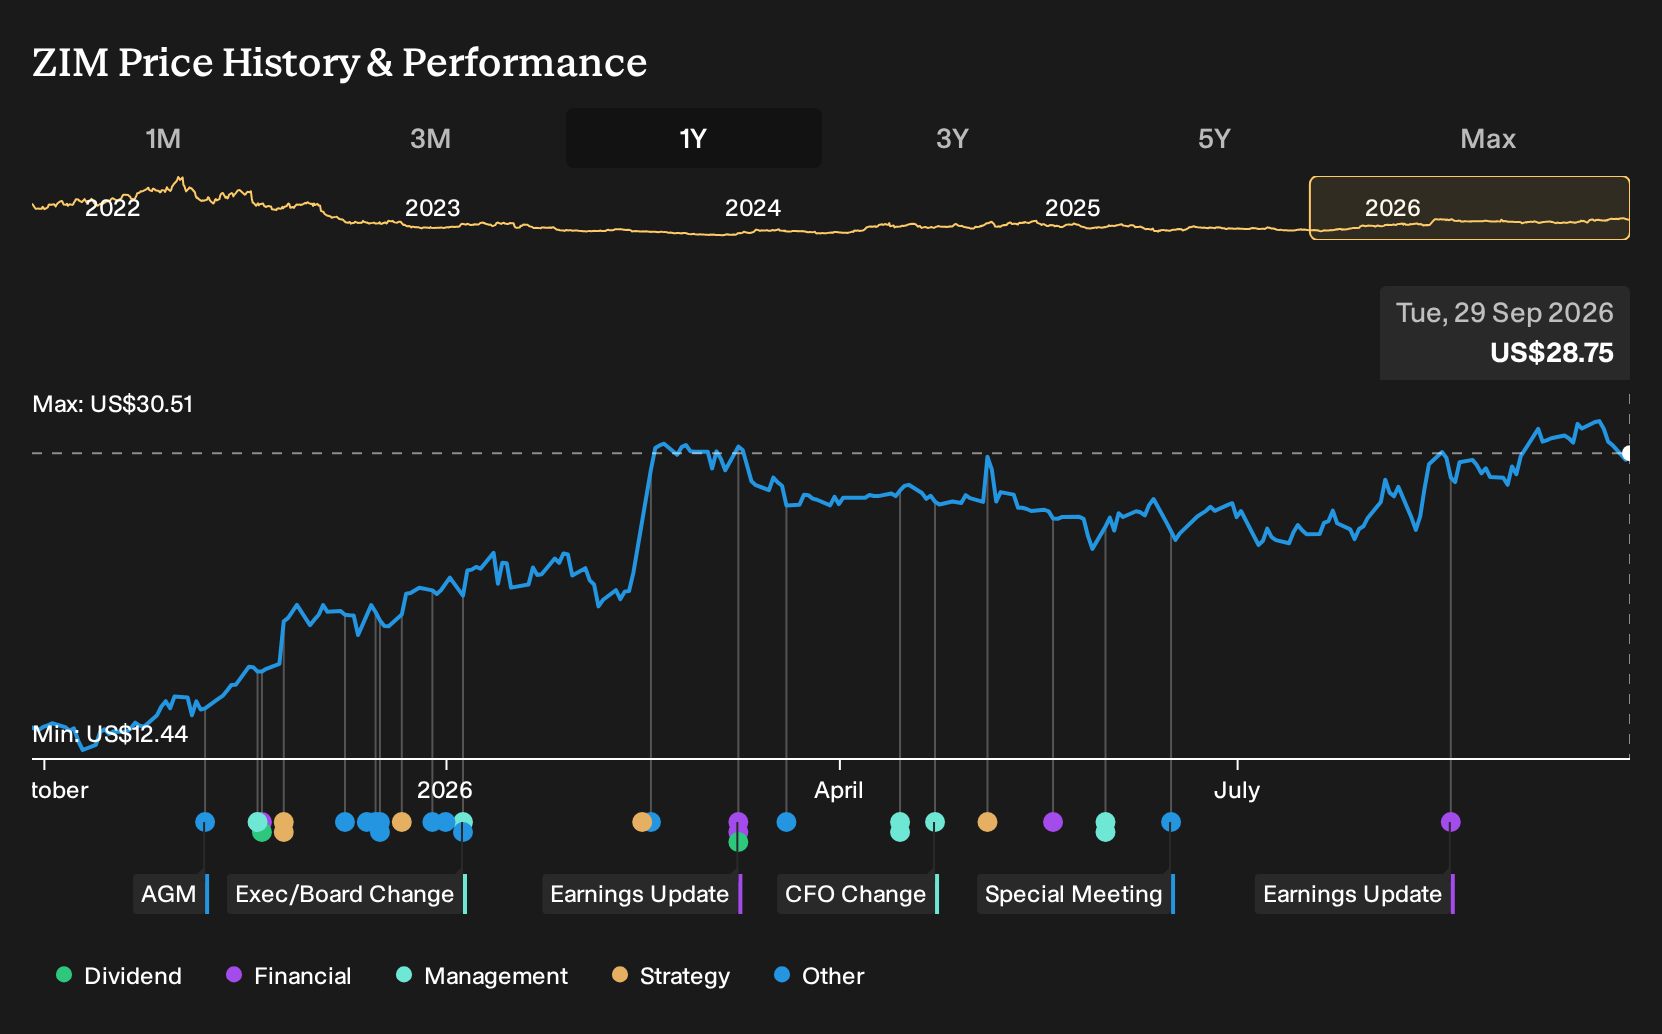
If ZIM Integrated Shipping Services sat on your watchlist instead of your brokerage statement, the past year might feel like a missed shot. For ZIM Integrated Shipping Services shareholders, the return over the past year was 122.7%, including dividends. That outcome arrived while analysts were split between bulls arguing digital shipping and LNG-powered vessels would attract resilient e-commerce demand, and bears warning that onshoring and tighter regulation would crush margins. If you rewind to late September 2025, which side of that profitability debate looked more convincing?
This theme extends beyond ZIM Integrated Shipping Services. See which of 37 profitable AI stocks that aren't just burning cash may still merit a closer look.
The Two ZIM Stories Investors Were Arguing About
The shares of ZIM Integrated Shipping Services cost US$13.61 at the start of the period, and investors were pulled between two sharply different stories about where the container carrier might head next.
On the bullish side, one camp argued that digital shipping tools and LNG-powered vessels could win higher quality e-commerce demand, with a Fair Value of US$19 that reflected what those assumptions implied rather than a proven outcome. That view leaned on ZIM's push into end-to-end digital booking and AI-driven pricing to support margins even if freight markets stayed tough.
The bearish Narrative pointed to onshoring and stricter environmental rules as long-run threats, and pinned Fair Value closer to US$9.5 based on more cautious expectations. This side worried that higher regulatory costs and pressure to invest in cleaner technology could erode profitability and leave ZIM at a disadvantage to larger rivals.
What The Results Changed In The ZIM Story
ZIM Integrated Shipping Services reported Q2 2026 revenue of US$1.78b and net income of US$63.5m, compared with US$1.64b and US$22.8m in Q2 2025. Net margin rose from 1.4% to 3.6%. That improvement supported the optimistic case that digital tools, LNG vessels, and newer routes could help profitability, although the higher margin remained modest.
The key lesson is about what to track. When a thesis leans on better quality demand and efficiency, it may be more useful to follow the net margin line and management commentary on route mix rather than looking only at headline revenue or share price.
What ZIM's Run Up 123% Already Assumes
At today's share price of US$28.75, ZIM Integrated Shipping Services trades well above the Fair Value that the selected Narrative outlines. This view frames the stock as pricing in a lot of good news already.
The Narrative emphasizes pressure from onshoring, regulation, chartered vessels, and bigger rivals. A buyer today would need to judge whether ZIM can keep modernizing its fleet and digital tools fast enough to offset those structural headwinds.
"A global movement towards onshoring and nearshoring by multinational manufacturers is threatening to structurally diminish long-haul containerized shipping demand, pointing to persistent volume stagnation or decline for ZIM, which would directly pressure long-term revenue growth. Intensifying environmental regulations and decarbonization mandates are expected to drive materially higher capital expenditure for cleaner technology and force the retirement of less efficient ships; for ZIM, these pressures will compress margins and could erode its competitive position as compliance costs accelerate faster than cost reductions from recent fleet upgrades."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Beyond ZIM's Shipping Lanes
ZIM shows how moving physical goods can hinge on efficient digital coordination. Your watchlist does not need to stop at the ocean.
People still expect the same thing on land. They tap a screen, request a ride or send a package, and trust it will arrive.
One platform focuses on stitching that demand together. It matches riders, couriers and shippers with available vehicles and routes in real time.
Its future may hinge on a different twist. As vehicles automate, the question shifts to who controls the customer connection and marketplace data.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 67% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com