
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Takeover Chatter Just Put Chipotle Stock in the Spotlight
Chipotle Mexican Grill (CMG) seems to be one of those volatile stocks with big risks and big rewards. Look at the recent history—shares jumped 65% in 2023, far outpacing the S&P 500 ($SPX), then collapsed in 2025, dropping 39% while the broader index enjoyed a 16% gain. And that trend is continuing this year, as CMG stock is down more than 13% while the S&P 500 is up 12%.
But shares got an interesting jolt this week—jumping as much as 4% on Monday on takeover speculation. Betaville published an “uncooked” alert saying Chipotle had attracted takeover interest from an unidentified company. The stock ultimately closed 1.7% higher at $31.85, with 31.4 million shares changing hands—nearly twice its 50-day average trading volume.
While the report hasn’t been substantiated and there’s no confirmation that Chipotle has received an offer or is in discussions, the report comes at an intriguing time for the fast-casual company, as revenues have been increasing but profitability is sagging.
Let’s see why Chipotle may be an appealing takeover target—and a fit in your portfolio.
About Chipotle Stock
Crazy ups and downs are nothing new for Chipotle. It experienced a series of foodborne illnesses from 2015 to 2018 that resulted in a $25 million fine from the Department of Justice.
But Chipotle, which pioneered the fast-casual dining model, also has a rabid fan base that lines up for bowls, burritos, and customized meals. The stock soared so high in 2024 that the company successfully executed a 50-for-1 stock split in order to make shares more accessible to employees and retail investors.
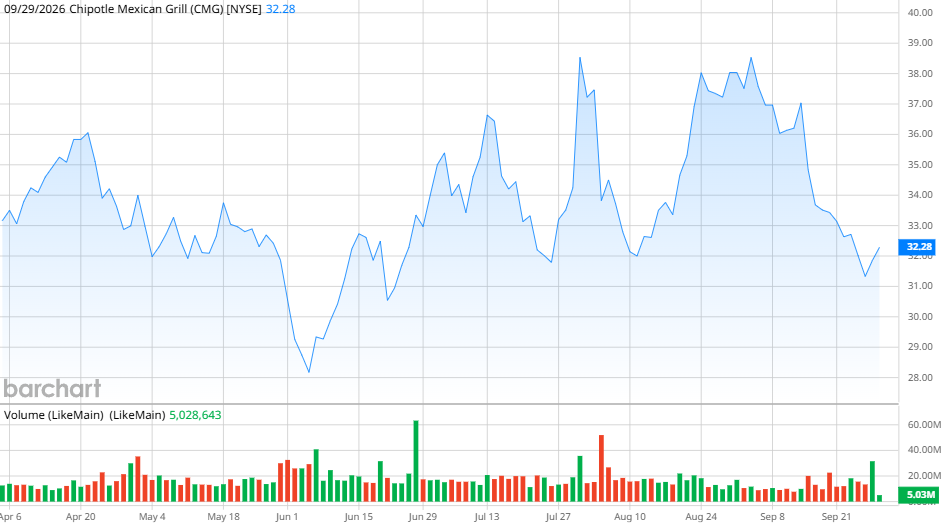
Shares are down 19% over the last year, far below the S&P 500's 15% gain. But that’s not unusual in this economy—the S&P 500 restaurant sector is down 15.5% over the last 12 months, due to lower foot traffic and higher beef and commodity prices. Chipotle currently has a forward price-to-earnings ratio of 28, which is roughly half of its five-year mean.
Chipotle also notably doesn’t pay a dividend, which sets it apart from other top restaurant stocks, including McDonald’s (MCD), Restaurant Brands International (QSR), and Darden Restaurants (DRI).
Beats on Earnings
Chipotle’s second-quarter results managed to beat Wall Street expectations by the slimmest of margins. Revenue rose 9.3% year-over-year (YoY) to $3.35 billion, driven primarily by new restaurant openings and a 2.2% increase in comparable restaurant sales. Transactions increased 1%, while the average check rose 1.2%. Adjusted earnings were $0.33 per share, beating the consensus estimate by a penny per share.
However, restaurant-level operating margins fell to 25.2% from 27.4% a year earlier as food, beverage, and packaging costs increased, partly due to inflation in beef and freight, while labor costs also rose.
The company is pinning its hopes on its “Recipe for Growth” plan to drive more customer traffic and support long-term expansion. The plan includes boosting operations and food quality, menu innovation, an updated rewards program, and international expansion.
“Our positive results reflect the momentum we're building as our Recipe for Growth strategy continues to take shape,” CEO Scott Boatwright said. “We're seeing encouraging progress because we're focused on the right growth drivers—bringing meaningful menu innovation to our guests, deepening engagement through Chipotle Rewards, elevating hospitality in every restaurant, and expanding opportunities to serve more group occasions. These efforts are building a stronger business and reinforcing our confidence in Chipotle's ability to deliver sustainable long-term growth and shareholder value.”
Management issued full-year guidance that raised its comparable restaurant sales outlook to growth in the low-single-digit range. Chipotle also reiterated its plan to open as many as 370 restaurants this year.
What Do Analysts Expect for CMG Stock?
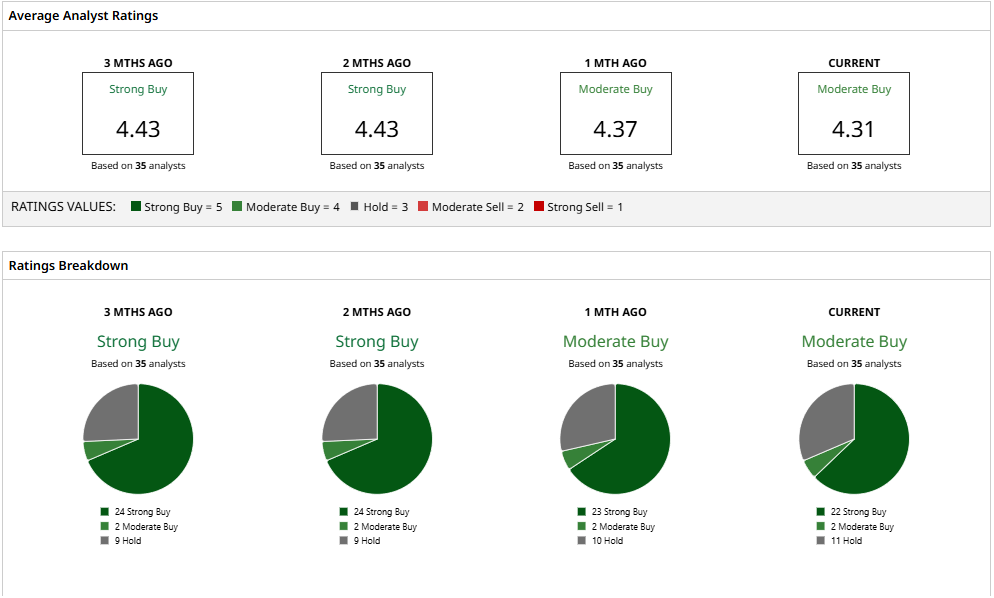
Wall Street remains bullish on Chipotle, although sentiment has cooled somewhat in recent months. Thirty-five analysts covering CMG stock give the stock a consensus “Moderate Buy” rating, with 22 “Strong Buy” ratings, two “Moderate Buy” ratings, and 11 “Hold” ratings.
Analysts have a mean price target of $44.02 for CMG, with estimates ranging from $36 to $53. Based on the current share price, the mean target represents a potential upside of approximately 36%.
Chipotle is expected to report third-quarter earnings on Oct. 28. Until then, investors will be watching closely if this fast-casual restaurant chain is ripe for a takeover—or in a position to grow once again.
On the date of publication, Patrick Sanders did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.