
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Accenture (ACN) Is Back In The Spotlight, What Is Driving The Attention?
Accenture (ACN) recently completed a complex SAP rollout for Yoplait’s newly acquired Canadian business, creating a unified platform across regions and a template for future integrations. Investors now weigh how this kind of repeatable work might influence Accenture stock.
Accenture’s recent contract wins and AI-focused partnerships sit against a choppy trading backdrop, with the 90 day share price return of 35.1% contrasting with a year-to-date share price decline of 31.9% and a 1-year total shareholder return that is down 25.8%. This suggests that momentum has picked up in the short run, even as longer-term holders remain under water.
Scan how Accenture’s AI-heavy consulting backlog compares with other potential candidates by reviewing the curated list of 32 high quality undervalued stocks.
Accenture now trades below the average analyst price target after a sharp rebound, while some estimates of intrinsic value sit higher still. Is that a genuine margin of safety or a warning that the market’s caution is warranted?
Most Popular Narrative: 41% Undervalued
Accenture’s most followed narrative pegs fair value at $301 per share, compared with the recent close at $177.12. That gap has investors asking whether the recent AI-related contract activity, like the Yoplait integration, justifies such a wide valuation view.
My core view: ACN is not a broken company; it is a strong company going through a credibility reset. The market is asking whether Accenture can convert AI from a threat into a growth engine.
See why 27 investors see Accenture as 41% undervalued.
Result: Fair Value of $301 (UNDERVALUED)
Still, the Accenture story can break if AI projects fail to scale into recurring work, or if U.S. federal softness drags on bookings longer than expected.
Find out about the key risks to this Accenture narrative.
Another View on Accenture’s Value
The SWS DCF model tells a different story to the popular $301 fair value narrative. On that framework, Accenture stock at $177.12 sits above an estimated future cash flow value of $153.76, which points to the shares looking expensive rather than cheap. Which version of “fair” do you trust more for your own process?
Look into how the SWS DCF model arrives at its fair value.
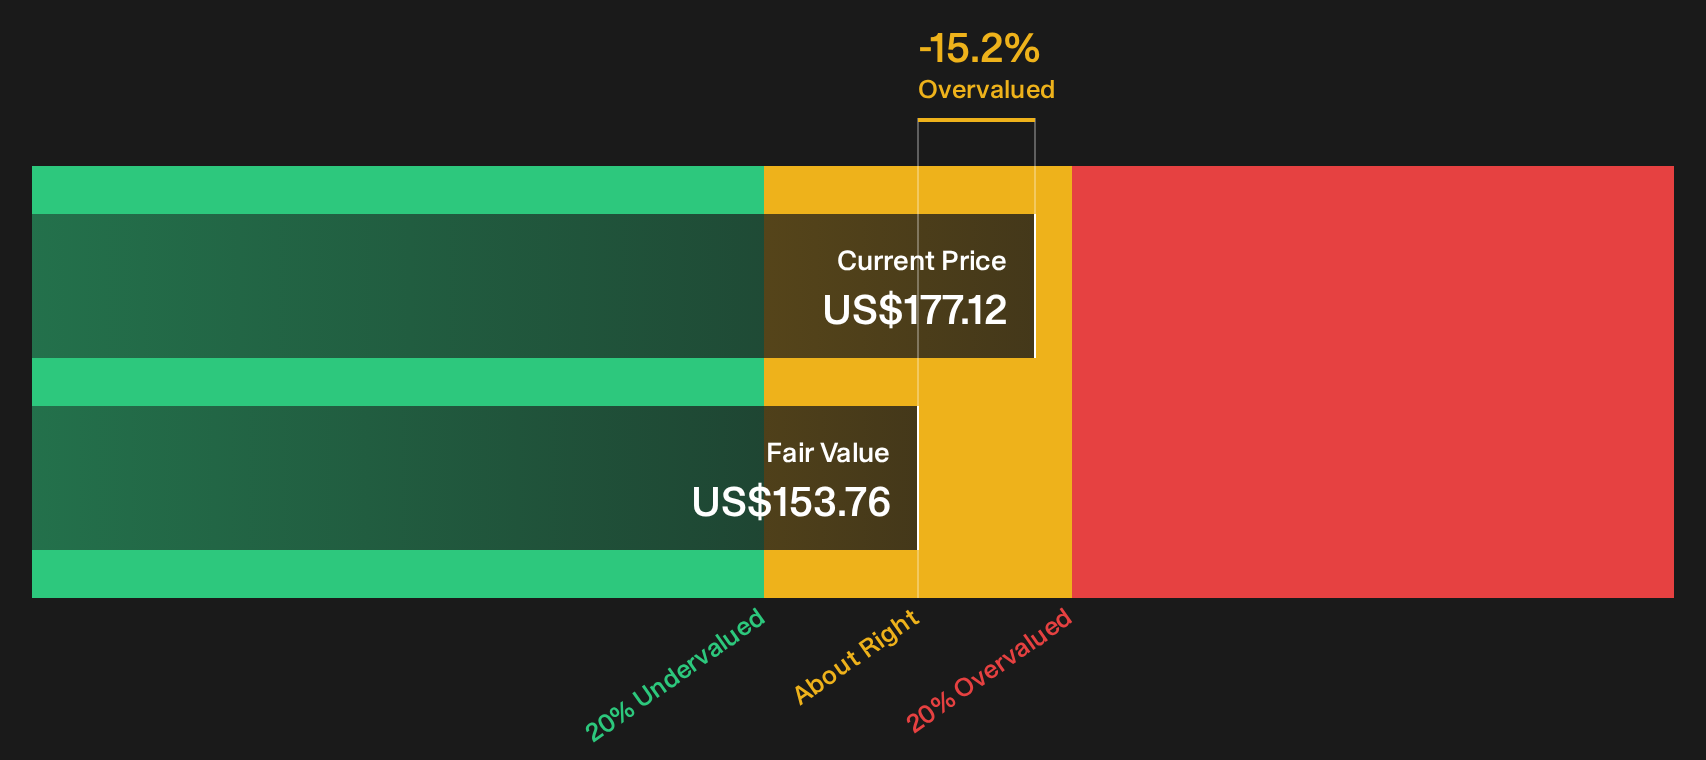
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Accenture for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by bullish fair value stories and a mixed recent share price path for Accenture? Act while the data is fresh and pressure test the optimism by reviewing the 4 key rewards.
Looking for more Accenture investment ideas?
Do not stop your work with Accenture alone. Broaden your watchlist with fresh angles that can help you spot opportunities before the crowd notices.
- Target resilient compounding potential by reviewing companies in the 32 resilient stocks with low risk scores that aim to keep volatility in check while still offering room for upside.
- Hunt for quality at a discount by scanning the 17 high quality undiscovered gems where strong fundamentals may not yet be fully appreciated by the broader market.
- Strengthen the defensive side of your portfolio by focusing on businesses in the list of solid balance sheet and fundamentals (25 results) that prioritize robust financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com