
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
IonQ (IONQ) Posted An Industry First Quantum Optimization Result On Real Hardware
- IonQ (NYSE:IONQ) and Classiq reported material quantum optimization results on real hardware for energy transmission planning with Israel Natural Gas Lines.
- The project applied a hybrid quantum classical approach to real world gas pipeline network optimization rather than purely simulated problems.
- This marks the first known use of IonQ hardware for complex operational planning tasks in critical gas infrastructure scenarios.
- These quantum optimization results on real gas pipeline hardware tests deserve to be weighed against the rest of our IonQ findings. We have also spotted 3 warning signs worth knowing about at IonQ.
For more context on where quantum and AI infrastructure intersect, explore other stocks in the same ecosystem via 88 AI infrastructure stocks.
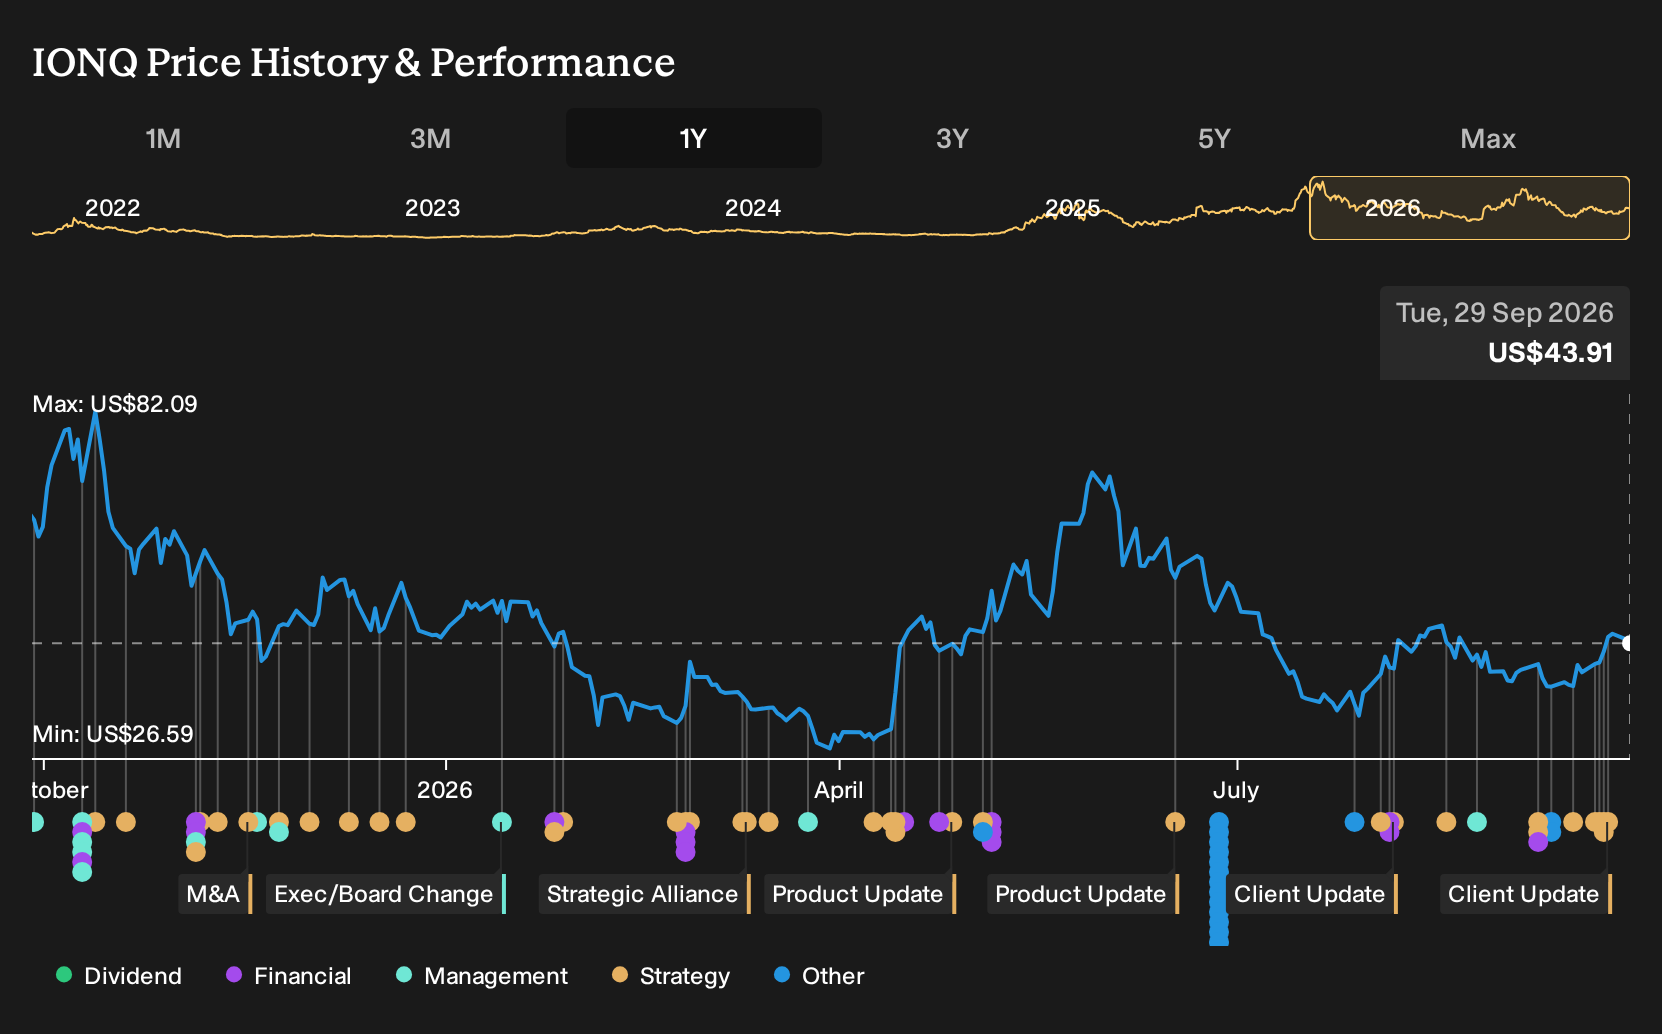
IonQ develops quantum computing systems across the US, Switzerland, and other regions, and this energy sector project shows how its hardware can be applied to complex optimization tasks that sit well beyond basic research experiments. For an investor, that places the company in the part of the semiconductor industry focused on building and testing practical quantum infrastructure rather than conventional chips.
See which insiders are buying and selling IonQ following this latest news.
How this quantum pipeline result stress tests the IonQ investment story
The central bet with IonQ is that real customers will run commercially relevant problems on its trapped ion hardware, turning today’s research projects into durable usage and contract pipelines. This Forte-1 gas network optimization work sits right on that Narrative, because it moves beyond toy problems into critical infrastructure planning.
"Acceleration of the technology road map with Electronic Qubit Control and the 256 qubit system scheduled for 2026 positions IonQ to move ahead of classical supercomputers on commercially relevant workloads, which should support sustained high revenue growth and operating leverage as systems scale..."
See how the full story points towards a $68.41 fair value for IonQ.
On the bullish side, the Classiq and Israel Natural Gas Lines result pushes IonQ closer to the Narrative promise of commercially relevant workloads in sectors that care about security and reliability. It lines up with other energy and power grid projects in the roadmap and shows investors that use cases like logistics and infrastructure are not just slideware.
The bearish lens is about scale and economics. This is still a reduced problem instance, running on current Forte-1 hardware, with no detail here on recurring spend, margins or contract size, which keeps concerns over profitability, dilution and long hardware roadmaps alive next to rivals such as IBM and Rigetti. The balance tilts slightly bullish for sentiment, but risk around execution and earnings remains prominent.
The same gas pipeline experiment can read as confirmation of IonQ’s real-world potential or as a reminder of how far the business model still has to travel, depending on which Narrative you hold.
The unanswered question for IonQ investors: who is actually steering this ship and what are they being rewarded to chase?
Hardware, contracts, and use cases only tell part of the IonQ story. The real missing piece is who sets the priorities, how their incentives work, and what that means for your risk. See who is actually steering IonQ, and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com