
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Realty Income (O) Stock Trades At A Premium Following Scotiabank Downgrade
Realty Income has pulled back to US$55.14 and is now well below its recent high after a downgrade, which puts a fresh spotlight on whether that valuation still lines up with what its earnings can support. For anyone eyeing this well known real estate vehicle today, the key issue is how much of its earnings power is already reflected in the stock price.
- Over the past 3 years the share price has gained 33.2%, which puts meaningful long term returns on the table if the earnings profile continues to justify that kind of move.
- Recent commentary around a downgrade and management's higher expectations for adjusted funds from operations suggests the market is wrestling with how much future earnings Realty Income can actually convert from its large investment pipeline and new capital partnerships.
- Your read on Realty Income is one view; the desks covering it have another. See what analysts think Realty Income's shares could be worth.
The issue now is whether the current US$55.14 share price is reasonable once you line it up against Realty Income's earnings and what those earnings imply for investors from here.
If you want a broader starting point while you weigh Realty Income after this downgrade and earnings debate, run the same questions across a focused list of 32 high quality undervalued stocks.
Does Realty Income Look Pricey on Earnings?
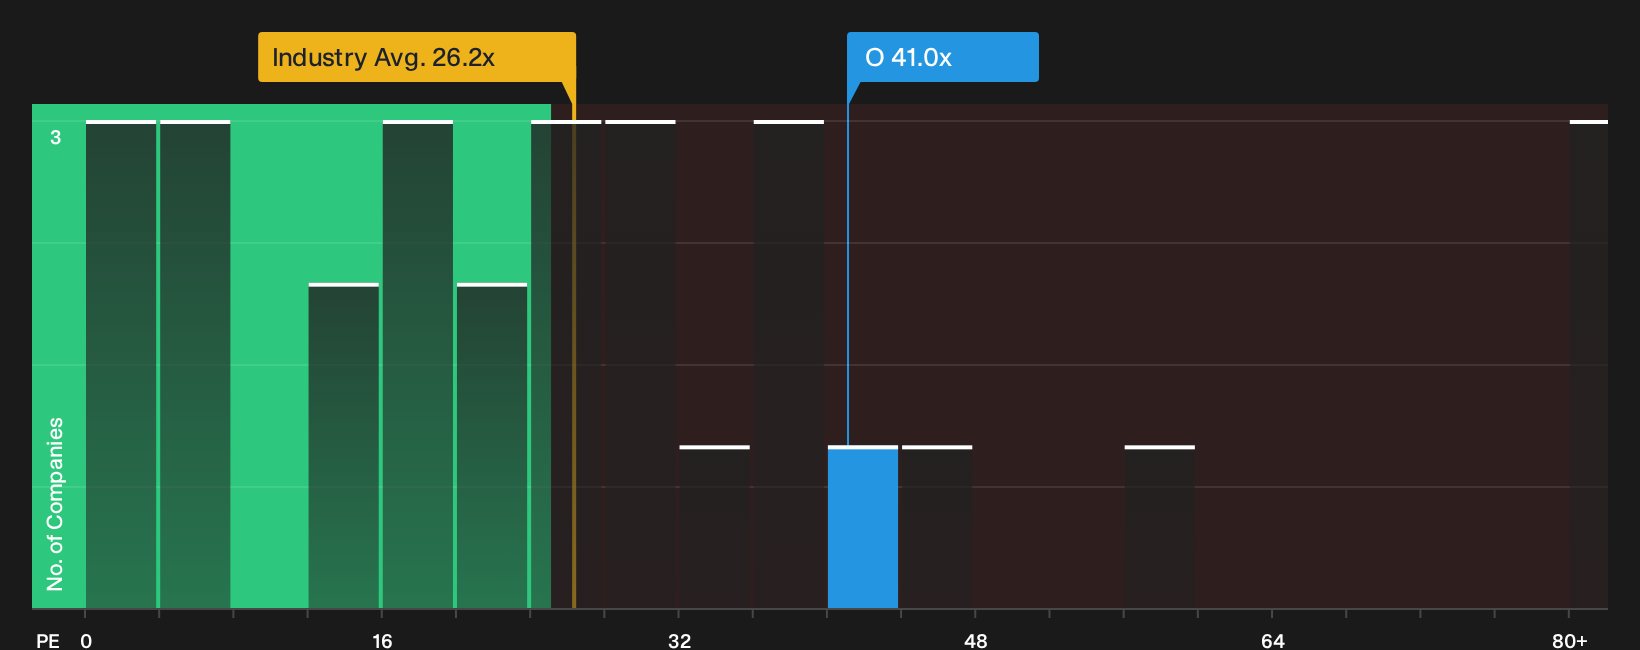
The P/E ratio tends to suit Realty Income because investors often anchor on its earnings stream relative to price. On this yardstick, the stock trades on about 41.0x earnings, which is well above both the Retail REITs sector on roughly 26.2x and the peer group average near 25.9x. That is a rich premium for a company in a fairly mature property segment.
Scotiabank’s downgrade, which pointed to rate pressure on funds from operations growth, lands awkwardly against a multiple that already sits above the level suggested by a tailored fair-value P/E. The fair multiple, which blends the company’s growth profile, margins, scale and risk mix, comes out lower than where the shares are currently priced. As a result, the model reads Realty Income as overvalued on earnings. For anyone weighing the stock at today’s price, the key question is whether its cash generation and capital partnerships can justify paying this kind of mark up over similar REITs. Explore the numbers behind Realty Income's P/E valuation.
The Realty Income Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Realty Income leaves off and explain what would need to happen to growth, margins and earnings for the stock to be worth materially more or less than today’s price. Each scenario links its figures to a specific view on how Realty Income's growth path, profitability and risk profile could change, giving you a concrete reference point to revisit as new information appears on the Community page.
One of the top community narratives on Realty Income: 11% undervalued
"Given the maturity of the business, its historical data and the fact that I project a higher interest rate environment over the next couple of years..."
Discover why this Narrative puts Realty Income at 11% undervalued.
What analyst expectations might still be missing from the Realty Income picture?
Valuation only tells you what the market is paying today, while professional estimates sketch out where this business could be a few years from now and give you a different yardstick to compare against the current share price. Explore where analysts expect Realty Income to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com