
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Global Penny Stocks To Watch In September 2026
As global markets navigate a landscape marked by inflation concerns and fluctuating interest rates, investors are increasingly exploring diverse opportunities. Penny stocks, despite the term's vintage connotation, continue to attract attention for their potential to offer value at lower price points. These smaller or newer companies can present underappreciated growth opportunities when backed by strong balance sheets and solid fundamentals.
Here's a peek at a few of the choices from the screener.
Inner Mongolia Junzheng Energy & Chemical GroupLtd (SHSE:601216)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Inner Mongolia Junzheng Energy & Chemical Group Co., Ltd. operates in the energy and chemical sectors, with a market capitalization of approximately CN¥37.46 billion.
Operations: Inner Mongolia Junzheng Energy & Chemical Group Co., Ltd. has not reported any specific revenue segments.
Market Cap: CN¥37.46B
Inner Mongolia Junzheng Energy & Chemical Group Ltd., with a market cap of CN¥37.46 billion, has demonstrated some financial resilience despite challenges. The company reported H1 2026 revenues of CN¥12.89 billion and net income of CN¥1.67 billion, showing slight declines from the previous year. Although its earnings have declined by 13.2% annually over five years, the debt is well-covered by operating cash flow (120.1%), and interest payments are not a concern due to sufficient earnings coverage. However, short-term liabilities slightly exceed short-term assets, indicating potential liquidity pressures in the near term.
- Get an in-depth perspective on Inner Mongolia Junzheng Energy & Chemical GroupLtd's performance by reading our balance sheet health report here.
- Assess Inner Mongolia Junzheng Energy & Chemical GroupLtd's previous results with our detailed historical performance reports.
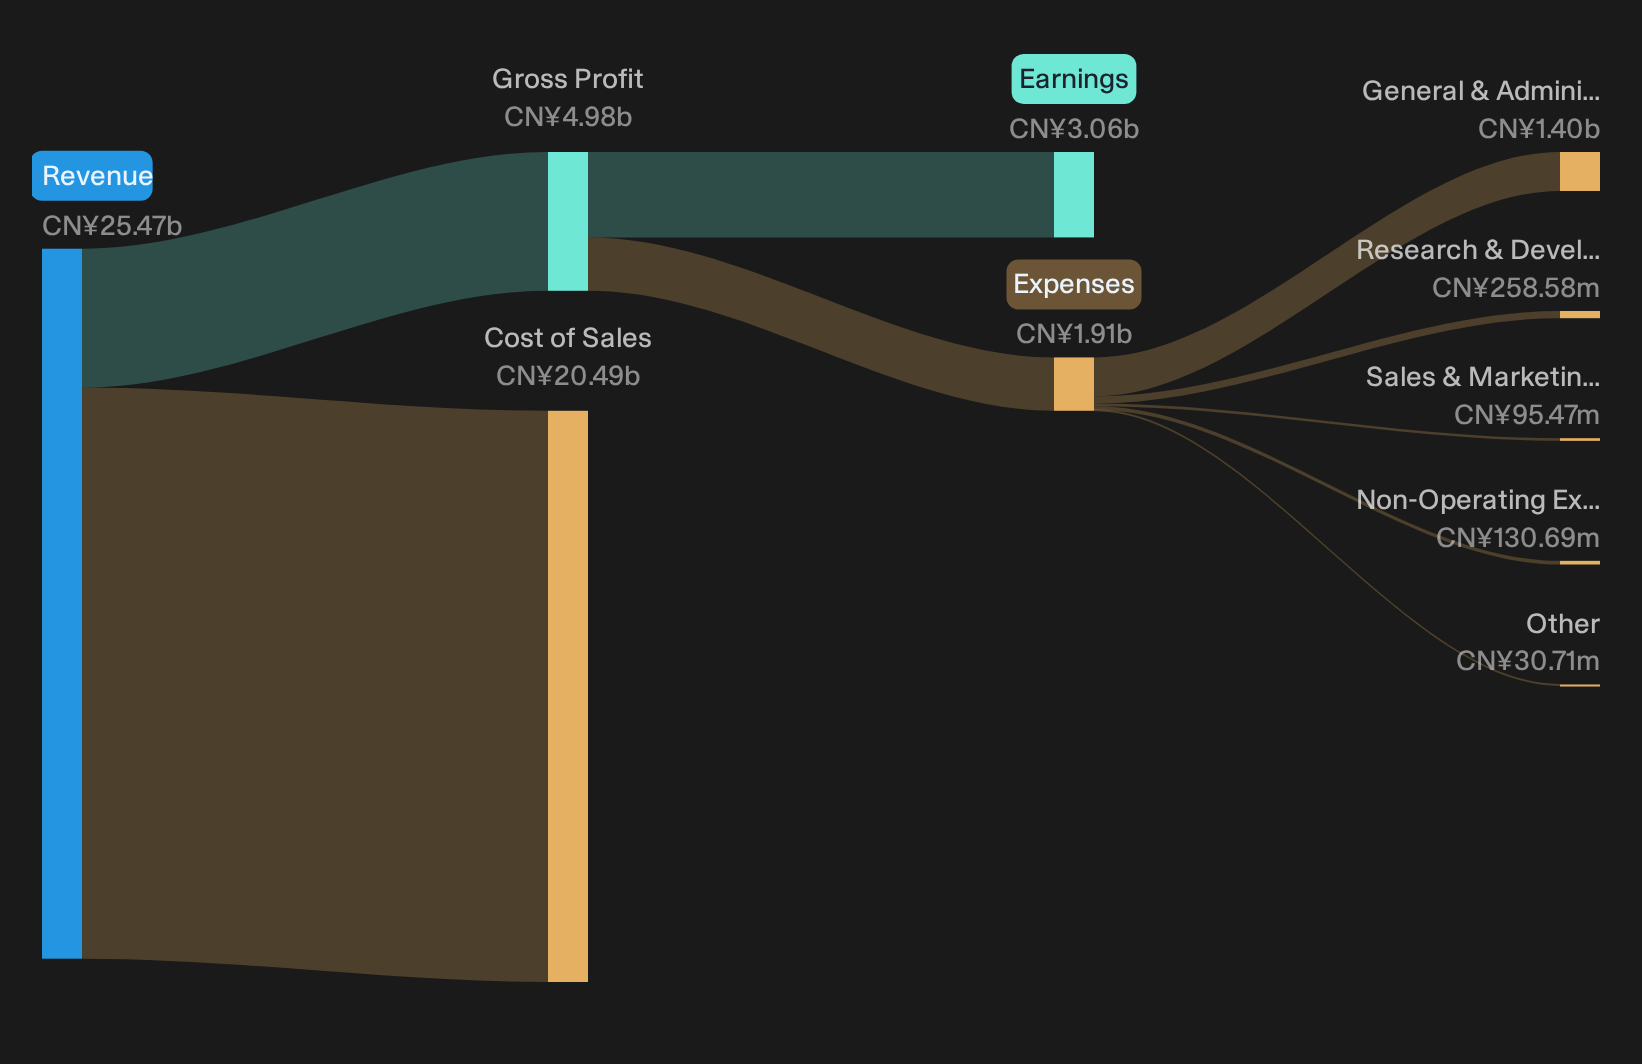
Meinian Onehealth Healthcare Holdings (SZSE:002044)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Meinian Onehealth Healthcare Holdings Co., Ltd. operates in the healthcare sector, focusing on providing health examination services, with a market cap of approximately CN¥17.39 billion.
Operations: The company generates revenue primarily from the medical industry, amounting to CN¥10.03 billion.
Market Cap: CN¥17.39B
Meinian Onehealth Healthcare Holdings, with a market cap of CN¥17.39 billion, is trading at 45% below its estimated fair value, suggesting potential undervaluation. The company has experienced stable weekly volatility and improved profit margins over the past year. Earnings grew by 17.2%, surpassing both its five-year average and industry performance. Despite a net loss for H1 2026, there is forecasted earnings growth of 22.65% annually. The management team and board are seasoned, while debt levels remain satisfactory with good coverage by operating cash flow; however, short-term liabilities exceed short-term assets, indicating possible liquidity concerns.
- Jump into the full analysis health report here for a deeper understanding of Meinian Onehealth Healthcare Holdings.
- Understand Meinian Onehealth Healthcare Holdings' earnings outlook by examining our growth report.

Jilin Asia Link Technology DevelopmentLtd (SZSE:002316)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Jilin Asia Link Technology Development Co., Ltd. (SZSE:002316) operates in the technology sector and has a market capitalization of CN¥1.77 billion.
Operations: The company generates revenue from various regions, with East China contributing CN¥191.80 million, Northeast CN¥108.59 million, Southwest CN¥75.98 million, Central China CN¥52.26 million, Northwest CN¥34.95 million, Northern China CN¥44.51 million, Southern China CN¥10.89 million, Overseas markets at CN¥3.69 million and Hong Kong, Macau and Taiwan adding another CN¥8.85 million to its financial performance.
Market Cap: CN¥1.77B
Jilin Asia Link Technology Development Ltd., with a market cap of CN¥1.77 billion, has demonstrated financial stability through strong interest coverage and a healthy cash position exceeding its total debt. Despite high-quality earnings historically, recent performance shows challenges with declining revenue and net income for the first half of 2026 compared to the previous year. The company's short-term assets slightly fall short of covering short-term liabilities, posing potential liquidity issues. While it has reduced its debt-to-equity ratio significantly over five years, negative earnings growth last year highlights ongoing profitability concerns amidst stable weekly volatility.
- Take a closer look at Jilin Asia Link Technology DevelopmentLtd's potential here in our financial health report.
- Gain insights into Jilin Asia Link Technology DevelopmentLtd's historical outcomes by reviewing our past performance report.

Taking Advantage
- Embark on your investment journey to our 3,650 Global Penny Stocks selection here.
- Seeking Other Investments? Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com