
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Jefferies Top Pick Might Change The Case For Investing In CAR Group (ASX:CAR)
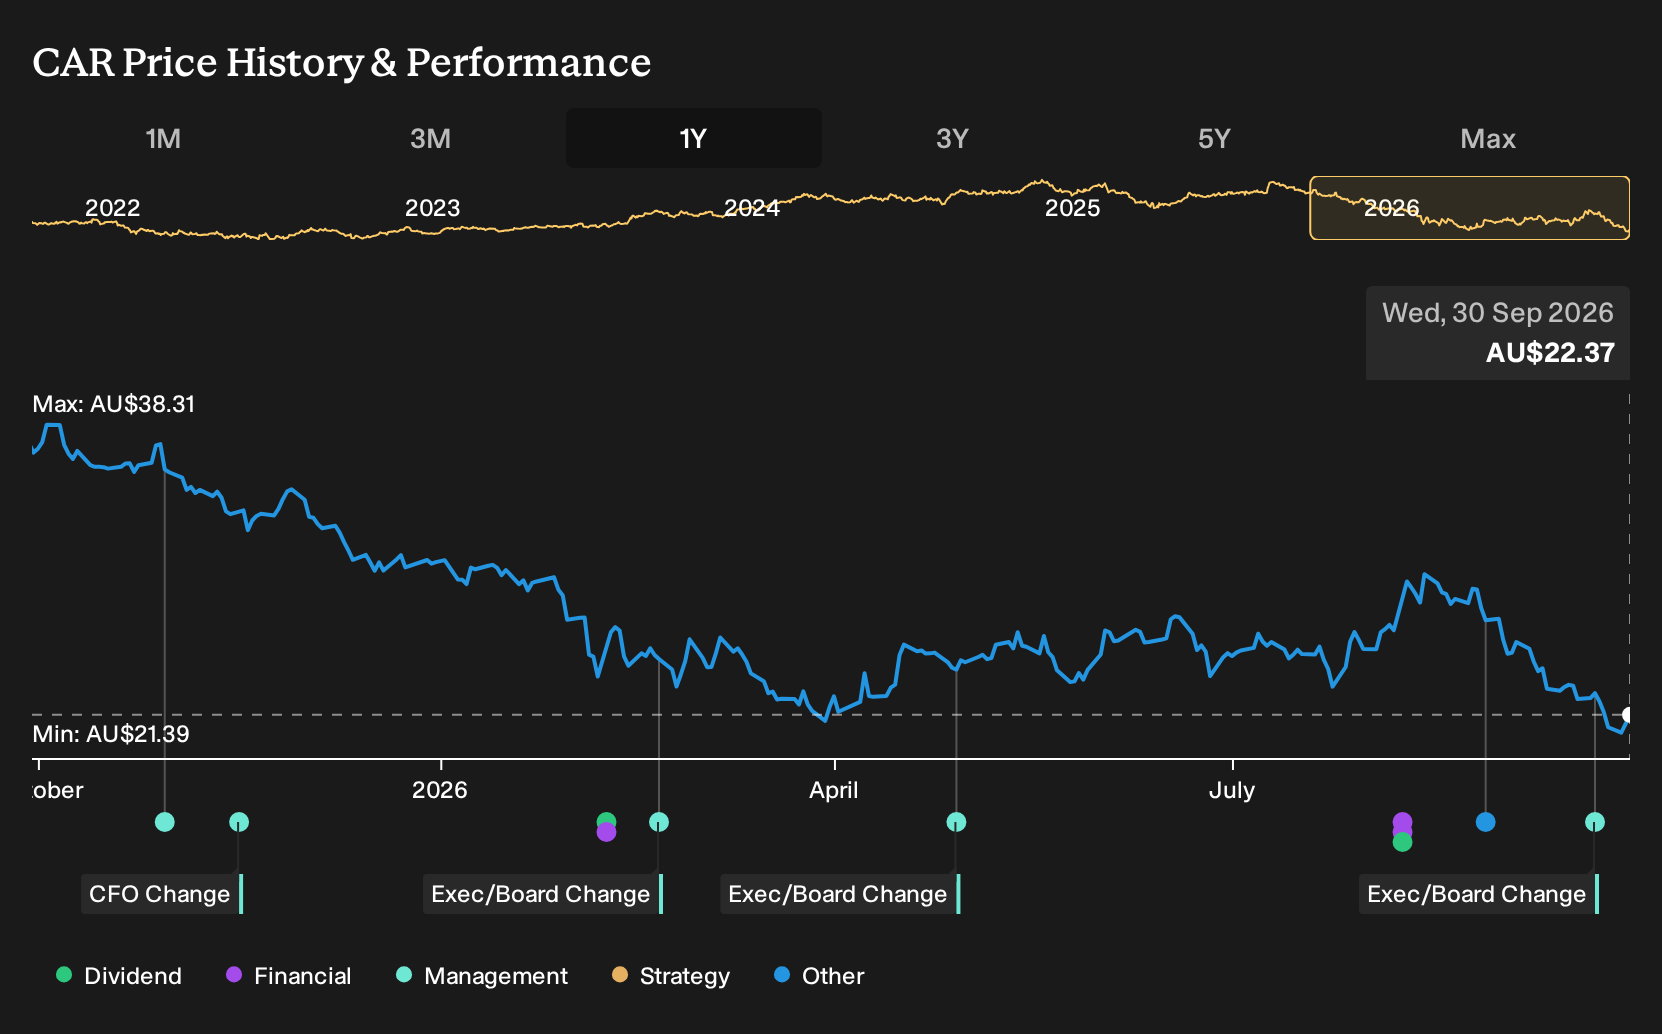
- CAR Group reported that longtime Non Executive Director Kee Wong retired from the board on 22 September 2026 after more than eight years of service, including as Chair of the Sustainability Committee.
- The departure of the board member overseeing sustainability arrives at a time when external analysts are examining CAR Group's ability to defend its online classifieds position against emerging AI driven rivals.
- We will now see how CAR Group's existing investment narrative could be influenced by views on its resilience to new AI powered competitors.
Compare CAR Group's position against AI focused classifieds rivals by scanning a curated set of 9 AI small caps that are also trying to turn machine learning into a durable moat.
CAR Group Investment Narrative Recap
To own CAR Group, you need to believe its online vehicle marketplaces can keep pulling in buyers and sellers as car transaction habits move further online, while the business keeps finding new ways to monetise that traffic through software, data and adjacent services. The near term swing factor is how effectively CAR Group can keep AI tools and dealer products feeling indispensable for customers as new AI driven classifieds rivals emerge.
Kee Wong stepping off the board looks contained for now, because CAR Group still has an experienced and largely independent board with a mix of tenures. The bigger operational risk remains execution in technology and product. Keeping up with AI, verification and security requires rising investment, and that could squeeze margins if new tools and services do not support future earnings and cash generation.
The recent Jefferies commentary on CAR Group matters here because it speaks directly to the AI threat that investors are weighing after Wong's retirement. Jefferies describes the business as resilient and flags limited immediate risk from META's Muse Agent and Facebook Marketplace to CAR Group's listings and online position. That offers one external datapoint on competitive pressure.
For catalysts, the key operational question is whether CAR Group can keep turning its AI, data and payments capabilities into must have tools for dealers and private sellers while defending its traffic. Jefferies' view that current AI entrants pose minimal risk does not remove the need for heavy tech spend. It instead frames the challenge as one of ongoing execution rather than an immediate shock to the classifieds model.
CAR Group's current analyst story points to revenues of A$1.6b and earnings of A$464.1 million by 2029. This profile is underpinned by assumed 9.8% yearly revenue growth and an earnings increase of about A$168.7 million from A$295.4 million today.
Uncover how CAR Group's fair value indicates a potential 50% upside to its current price before the market closes that discount.
Exploring Other Perspectives
Views inside the Simply Wall St Community cluster tightly, with four fair value estimates for CAR Group sitting in a narrow A$32 to A$33.32 band. That tight range can mask how differently you might weigh risks such as rising EV adoption or catalysts such as global online penetration. Use those contrasting angles to test your own thesis.
Explore 3 other CAR Group fair value estimates, including one that suggests as much as 52% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CAR Group research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CAR Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CAR Group's overall financial health at a glance.
Looking for more investment ideas beyond CAR Group?
If CAR Group has sharpened your thinking about classifieds and data rich platforms, it can be useful to test that framework against a wider watchlist. The Simply Wall St Screener lets you quickly sort through listed businesses by quality, valuation, risk profile and income potential so you can build a line up that actually fits your goals.
- For investors focused on resilient businesses with steadier profiles, consider reviewing a curated set of 7 resilient stocks with low risk scores that keep risk scores in tighter ranges while still offering listed market exposure.
- If capital preservation and financial strength matter most, scan a list of solid balance sheet and fundamentals (11 results) to see which companies pair cleaner balance sheets with more robust fundamentals.
- Those hunting for mispriced opportunities can comb through a 5 high quality undervalued stocks to find stocks where fundamental quality and current pricing appear out of sync.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com