
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Canadian Undervalued Stocks To Watch In September 2026
Australian inflation has returned to 4% and the Reserve Bank has pushed interest rates to a 15 year high of 4.6%. This puts extra pressure on highly priced growth stories. Cash rich businesses trading below estimated fair value suddenly look more interesting. This article walks through three Canadian stocks that the cash flow screener flags as potentially undervalued, helping you focus on companies where current pricing already bakes in a lot of caution.
The three Canadian ideas below are just a small sample, and the full cash flow screen on Simply Wall St surfaced 2 more businesses with equally compelling stories that are not covered here. To identify and analyze the value opportunities that best fit your own approach, head straight into the Undervalued Stocks Based On Cash Flows screener.
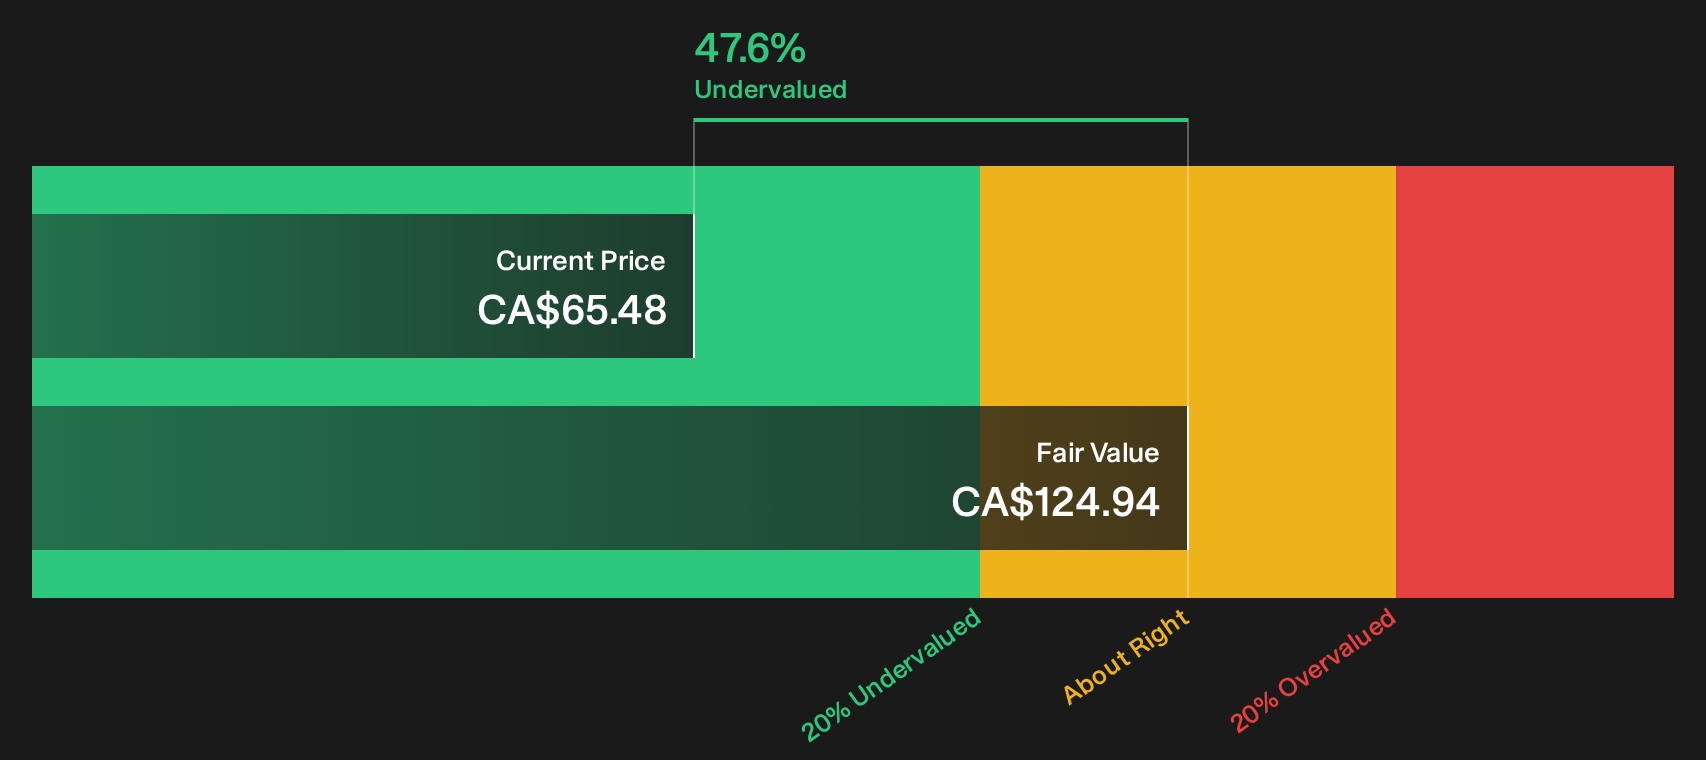
Pan American Silver (TSX:PAAS)
Overview: Pan American Silver is a precious metals producer running silver and gold mines across the Americas that generate operating cash flows.
Operations: The business earns about $5.3b annually from mines across Brazil, Chile, Peru, Mexico, Canada, Argentina and Bolivia, led by Jacobina, El Peñon and Shahuindo.
Market Cap: CA$27.1b
Pan American Silver fits this cash flow focused screen because its producing silver and gold assets convert metal output into operating cash. The DCF model then weighs that cash generation against a share price that still reflects a cautious view of that stream.
"Integration of Juanicipio, with its low cash costs and contribution to attributable silver production and income, refines the cost base and can support higher segment margins and free cash flow generation."
The key variable is how one still unresolved pressure on unit costs and project delivery shapes those future margins and cash returns.
Those cost and delivery swings are exactly what the full narrative for Pan American Silver unpacks, showing where cash generation could accelerate or stall as Pan American Silver executes its plan.
Savaria (TSX:SIS)
Overview: Savaria designs, installs, and services home and commercial accessibility equipment and adapted vehicles that support recurring, cash-generating aftermarket revenue.
Operations: Savaria generates about CA$739 million from Accessibility and adapted vehicles and CA$209 million from Patient Care across Canada, the US, Europe and beyond.
Market Cap: CA$2.2b
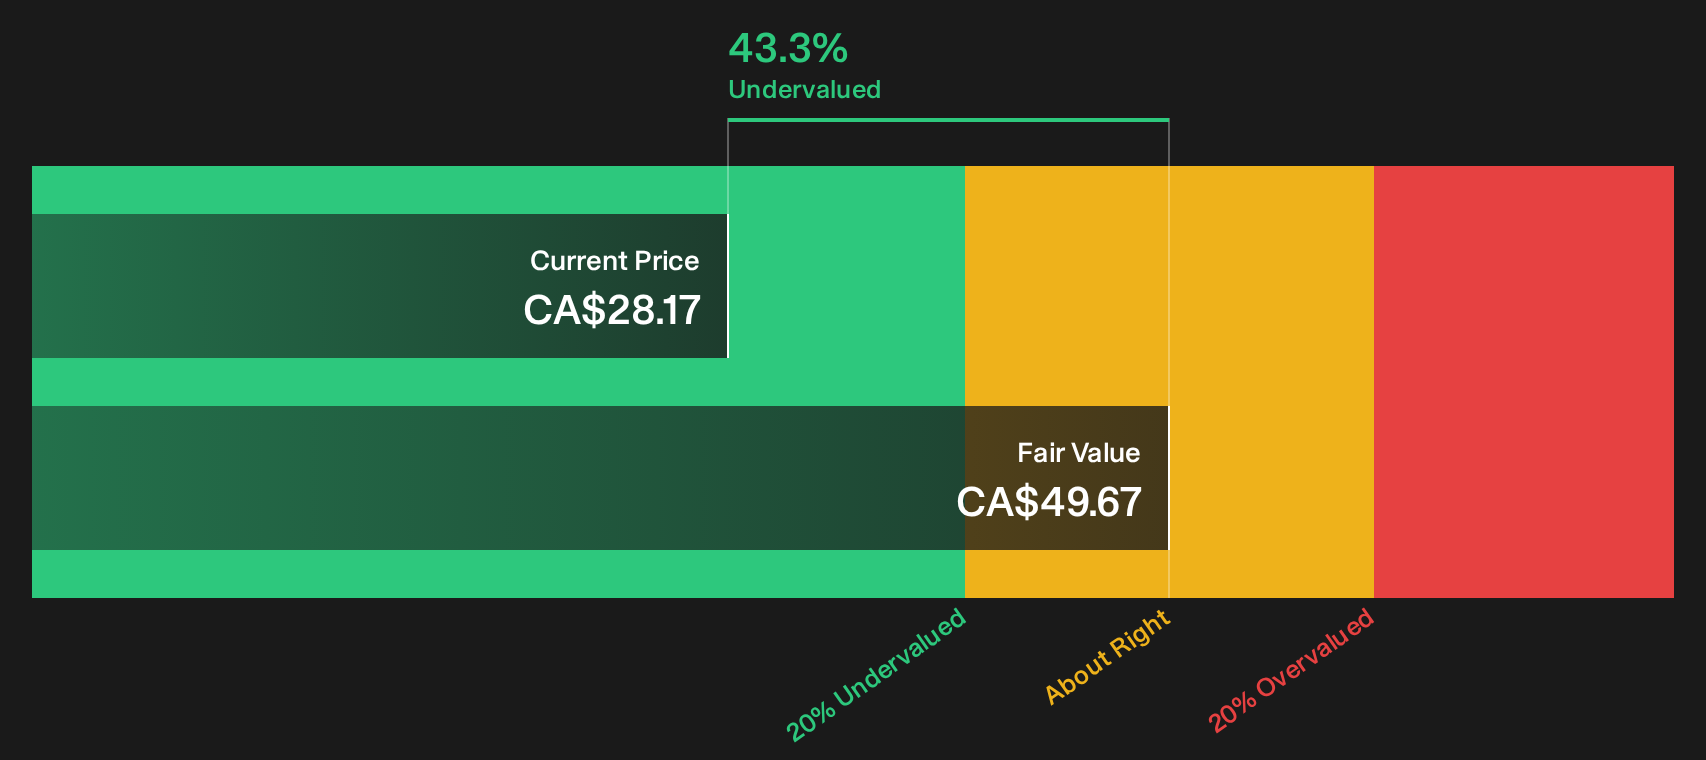
Savaria matters for this cash flow screen because its Accessibility products do not just sell once, they keep bringing in service and upgrade work that can support a steadier stream of cash than many one off equipment makers.
"Ongoing global demographic shifts, namely population aging and increased urban density, are expected to drive a sustained uptick in demand for home accessibility solutions (e.g., elevators, stairlifts), positioning Savaria for long-term revenue growth as these trends intensify."
The real swing factor is how one pressure on future profitability shapes the gap between a cautious price and that long-term cash potential.
That pressure point is exactly where the full narrative for Savaria shows whether aging demographics are quietly accelerating Savaria’s cash story or masking emerging risks.
Suncor Energy (TSX:SU)
Overview: Suncor Energy is an integrated energy business that produces oil sands bitumen and turns it into refined fuels and related products.
Operations: The business earns about CA$26.9b from Oil Sands, CA$36.8b from Refining and Marketing, and CA$2.5b from Exploration and Production.
Market Cap: CA$114.0b
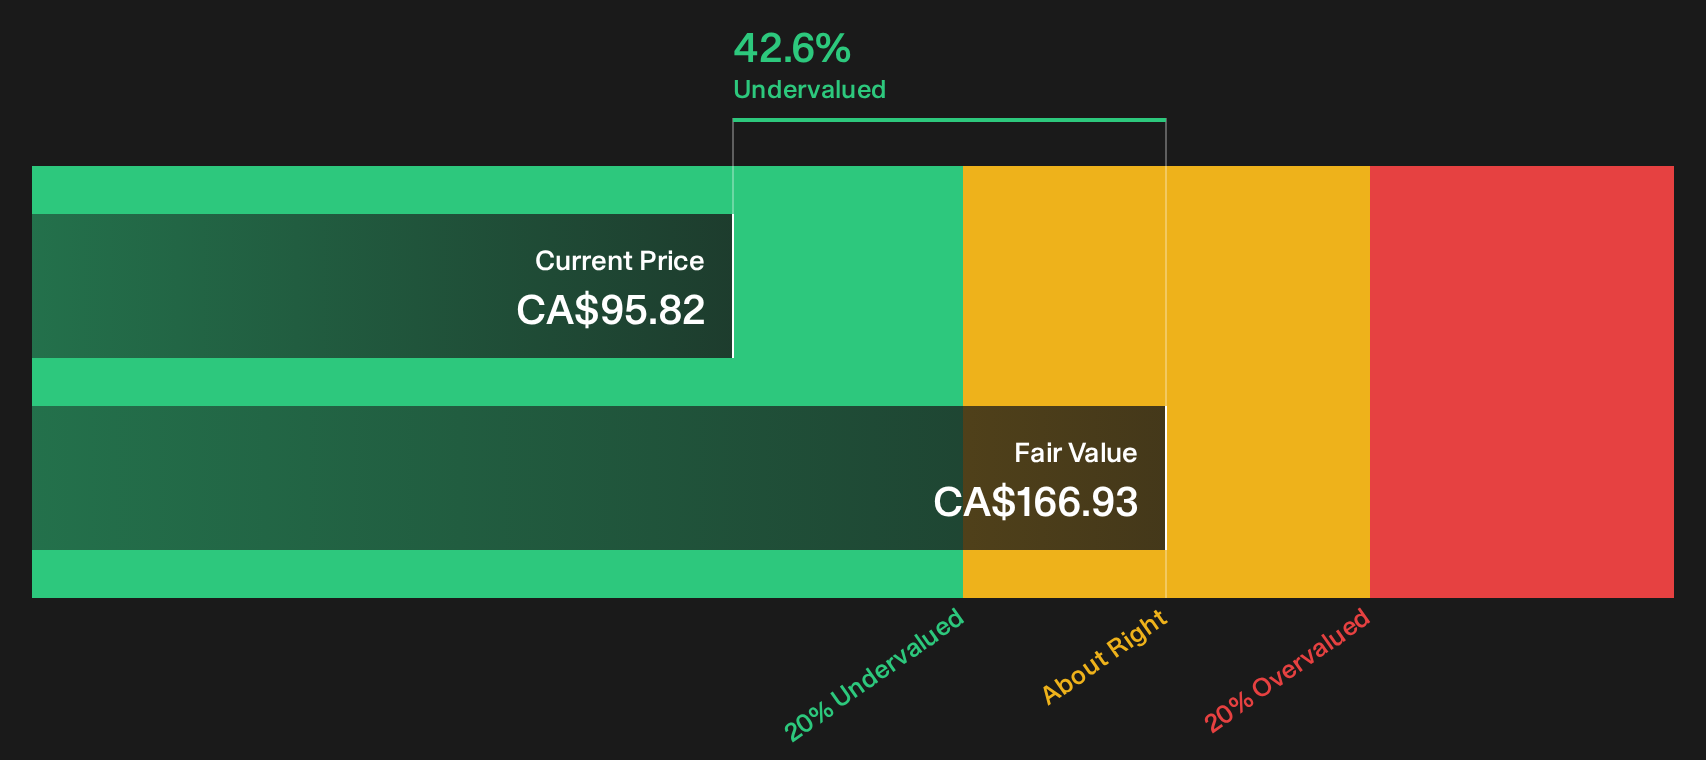
Suncor Energy catches the eye in this cash flow focused screen because its long life oil sands assets feed into refineries and retail outlets. This gives the business an integrated engine of bitumen production and fuel sales that can support repeatable cash generation when the system runs smoothly.
"Reliance on very high utilization of existing oil sands and refining assets, including refinery runs consistently at or above 100% and upgrader utilization above 100%, leaves little unused capacity to offset unplanned outages. This could pressure volumes and compress margins if reliability slips from current record levels."
What really matters for investors now is how one less visible constraint on that finely tuned system ultimately shapes cash returns over time.
That hidden constraint on Suncor Energy’s system is exactly what the full narrative for Suncor Energy unpacks, separating stalled throughput fears from areas where cash generation could actually be accelerating.
Seeking Fresh Alternatives Before They Fly
Fresh opportunities move quickly as momentum builds, sentiment shifts and prices start breaking away from today’s levels. Scan these under the radar ideas before the crowd catches on and consider how they might fit your approach.
- Target stronger cash engines by focusing on companies with resilient finances and cleaner balance sheets using the list of solid balance sheet and fundamentals (7 results).
- Follow the trend toward automation by tracking curated 93 robotics and automation stocks that may align with industries emphasizing efficiency and precision.
- Evaluate potential yield workhorses by reviewing 1 dividend fortresses that pair sizable payouts with balance sheets structured to handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com