
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
UK Growth Companies With High Insider Ownership In September 2026
The United Kingdom's stock market has recently faced challenges, with the FTSE 100 index experiencing declines due to weak trade data from China, highlighting global economic uncertainties. In such a volatile environment, growth companies with high insider ownership can be appealing as they often demonstrate strong alignment between management and shareholder interests, potentially offering resilience amid broader market fluctuations.
Top 10 Growth Companies With High Insider Ownership In The United Kingdom
| Name | Insider Ownership | Earnings Growth |
| TEAM (AIM:TEAM) | 32% | 85.3% |
| Quantum Base Holdings (AIM:QUBE) | 31.8% | 111.8% |
| Mortgage Advice Bureau (Holdings) (LSE:MAB1) | 18.4% | 22.4% |
| Metals Exploration (AIM:MTL) | 15.9% | 90.1% |
| Hardide (AIM:HDD) | 20.8% | 76.2% |
| FDM Group (Holdings) (LSE:FDM) | 17.7% | 44.6% |
| Energean (LSE:ENOG) | 19.3% | 32.9% |
| EARNZ (AIM:EARN) | 19.5% | 76.5% |
| Crimson Tide (AIM:TIDE) | 33.5% | 119.1% |
| ActiveOps (AIM:AOM) | 22.2% | 81% |
Underneath we present a selection of stocks filtered out by our screen.
Next 15 Group (AIM:NFG)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Next 15 Group plc operates in the data, technology, and activation sectors across various regions including the UK, US, Europe, the Middle East, Africa, and Asia Pacific with a market cap of £322.28 million.
Operations: The company's revenue is derived from several segments, including Retail Media (£87.68 million), Data & Research (£67.91 million), Creative Services (£70.63 million), Digital Transformation (£60.87 million), and Marketing & Communications (£330.19 million).
Insider Ownership: 10.1%
Earnings Growth Forecast: 78% p.a.
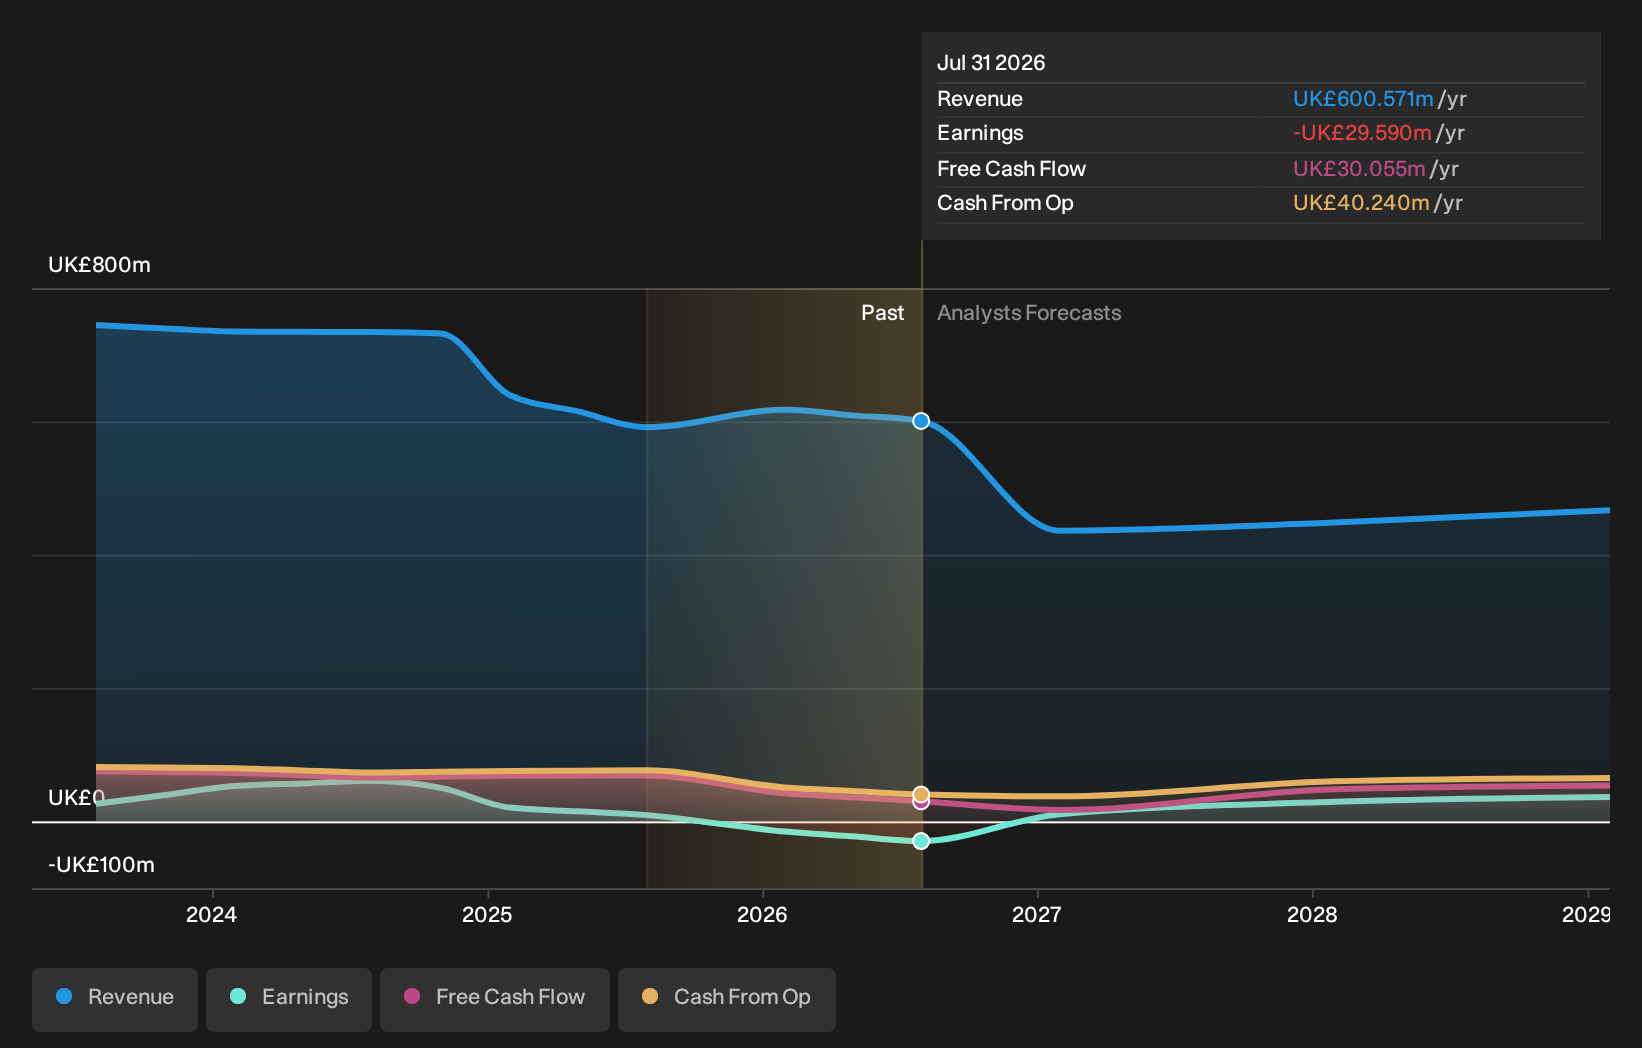
Next 15 Group is forecast to achieve profitability within three years, with earnings expected to grow significantly at 78.01% annually. Despite trading at 49.1% below its estimated fair value, the company faces challenges with anticipated revenue declines of 8% per year over the same period. Analysts predict a potential stock price increase of 51.6%, but the current dividend yield of 4.81% lacks coverage by earnings, indicating sustainability concerns in this area.
- Dive into the specifics of Next 15 Group here with our thorough growth forecast report.
- In light of our recent valuation report, it seems possible that Next 15 Group is trading behind its estimated value.
Foresight Group Holdings (LSE:FSG)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Foresight Group Holdings Limited is an infrastructure and private equity manager operating in the UK, Italy, Luxembourg, Ireland, Spain, and Australia with a market cap of £479.43 million.
Operations: The company's revenue is derived from its Real Assets segment, generating £114.81 million, and its Private Equity segment, contributing £50.11 million.
Insider Ownership: 35.6%
Earnings Growth Forecast: 16.2% p.a.
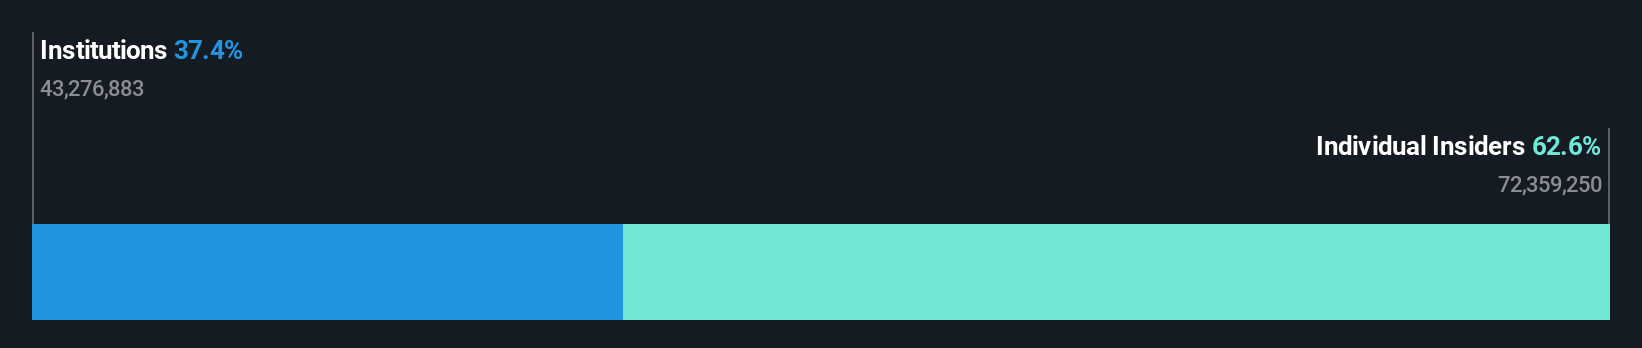
Foresight Group Holdings is trading at 36.9% below its estimated fair value, with earnings forecast to grow 16.2% annually, outpacing the UK market's growth rate of 11.2%. Analysts agree on a potential stock price rise of 56.6%. Recent board changes include John Le Poidevin becoming Chair of the Audit & Risk Committee following Geoff Gavey's departure. Despite no recent insider trading activity, the company demonstrates strong growth prospects and value relative to peers.
- Take a closer look at Foresight Group Holdings' potential here in our earnings growth report.
- Our valuation report unveils the possibility Foresight Group Holdings' shares may be trading at a discount.
Beauty Tech Group (LSE:TBTG)
Simply Wall St Growth Rating: ★★★★★☆
Overview: The Beauty Tech Group plc, along with its subsidiaries, offers at-home beauty devices across various regions including the United States, Canada, the United Kingdom, Ireland, Europe, and Asia; it has a market cap of £495.96 million.
Operations: The company's revenue is derived from its at-home beauty devices, with contributions of £3.01 million from Tria Laser, £14.58 million from Ziip Beauty, and £147.81 million from Currentbody skin.
Insider Ownership: 20.6%
Earnings Growth Forecast: 23.8% p.a.
Beauty Tech Group demonstrates strong growth potential, with earnings projected to grow significantly at 23.8% annually, outpacing the UK market's 11.1%. Recent H1 2026 results showed impressive performance, with net income rising from £2.81 million to £12.53 million year-over-year and revenue reaching £79.72 million. The company trades at 32.8% below its estimated fair value, with analysts predicting a stock price increase of 20.8%. Leadership changes include Dr Marnie Millard OBE joining as Non-Executive Director, enhancing strategic oversight.
- Delve into the full analysis future growth report here for a deeper understanding of Beauty Tech Group.
- The analysis detailed in our Beauty Tech Group valuation report hints at an deflated share price compared to its estimated value.

Make It Happen
- Discover the full array of 62 Fast Growing UK Companies With High Insider Ownership right here.
- Curious About Other Options? The end of cancer? These 35 emerging AI stocks are developing tech that will allow early idenification of life changing disesaes like cancer and Alzheimer's.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com