
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Jiangxi Copper (SEHK:358) The Latest Update Raises A Bigger Question
OCBC Group Research’s upgrade on Jiangxi Copper (SEHK:358) to a BUY rating after strong first half 2026 results, despite smelting challenges, has put fresh attention on how the stock’s recent performance lines up with that call.
The Jiangxi Copper share price closed at HK$32.44 after the upgrade, with the 1-day share price return of 1.88% partially offsetting a 30-day share price decline of 17.50%. The 3-year total shareholder return of 215.92% indicates that longer term momentum has been strong, even as the year-to-date share price return is down 25.73%.
Scan how Jiangxi Copper stacks up against other producers by reviewing a curated set of 17 top copper producer stocks that could see sentiment shift quickly on fresh research or results.
Jiangxi Copper has a broad, profitable-looking operation and a long runway of projects, yet the share price recently fell sharply. Does that recent slide leave the stock attractively priced, or is it still demanding for new capital?
Price-to-Earnings of 8.3x: Is it justified for Jiangxi Copper?
Jiangxi Copper is trading on a P/E of 8.3x, which looks restrained compared with both peers and its own earnings profile, given the last close at HK$32.44 and the wider sector context.
The P/E multiple reflects how much investors are currently paying for each unit of net profit. For a diversified metals producer like Jiangxi Copper, with exposure to copper and gold and a broad set of related activities, that number often captures how the market views the durability of earnings, the quality of cash flows, and the risk tied to commodity cycles.
Here, the current P/E of 8.3x sits well below the peer average of 32.8x and also under the estimated fair P/E of 10.1x. That gap suggests the market is assigning a significant discount relative to both similar businesses and the level that a fair ratio model indicates the multiple could move towards if sentiment and fundamentals aligned more closely.
Explore the SWS fair ratio for Jiangxi Copper.
Result: Price-to-Earnings of 8.3x (UNDERVALUED)
Still, Jiangxi Copper faces clear pressure points, including sensitivity to copper and gold price swings and the risk that smelting or project execution issues weigh on profitability.
Find out about the key risks to this Jiangxi Copper narrative.
Another View on Jiangxi Copper’s Value
There is a second lens investors often use for Jiangxi Copper. The SWS DCF model puts fair value at HK$43.74 per share versus the current HK$32.44. That implies the stock trades at about a 25.8% discount. The question is whether future cash flows will actually track those assumptions.
Look into how the SWS DCF model arrives at its fair value.
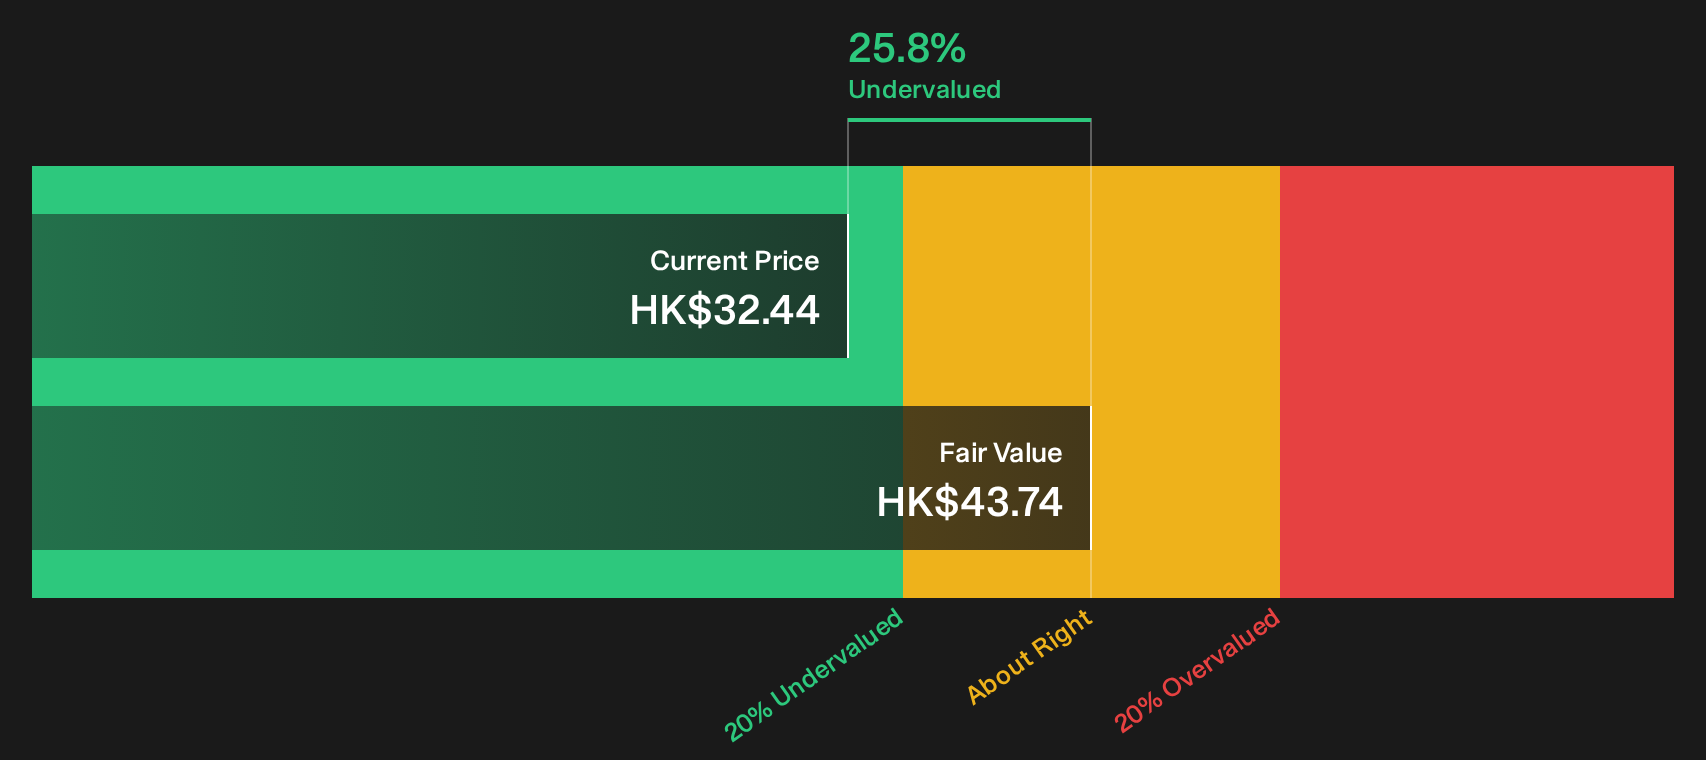
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Jiangxi Copper for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 197 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a clear story taking shape for Jiangxi Copper? If you want to move fast and form your own view using a balanced snapshot of both risk and upside, start with the 4 key rewards and 1 important warning sign.
Looking for more Jiangxi Copper style investment ideas?
Do not stop with Jiangxi Copper. Broaden your watchlist with other opportunities that tap different sources of return, risk profiles, and balance sheet strength.
- Target potential value and quality in one move by scanning a curated mix of 197 high quality undervalued stocks that share strong fundamentals and disciplined pricing.
- Identify portfolio income candidates early by reviewing a focused group of 162 dividend fortresses that combine yield with robust financial metrics.
- Tilt toward resilience by filtering for a list of solid balance sheet and fundamentals (204 results) to stay prepared when market conditions reward stronger finances.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com