
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Leadership Change Might Change The Case For Investing In Nutanix Stock (NTNX)
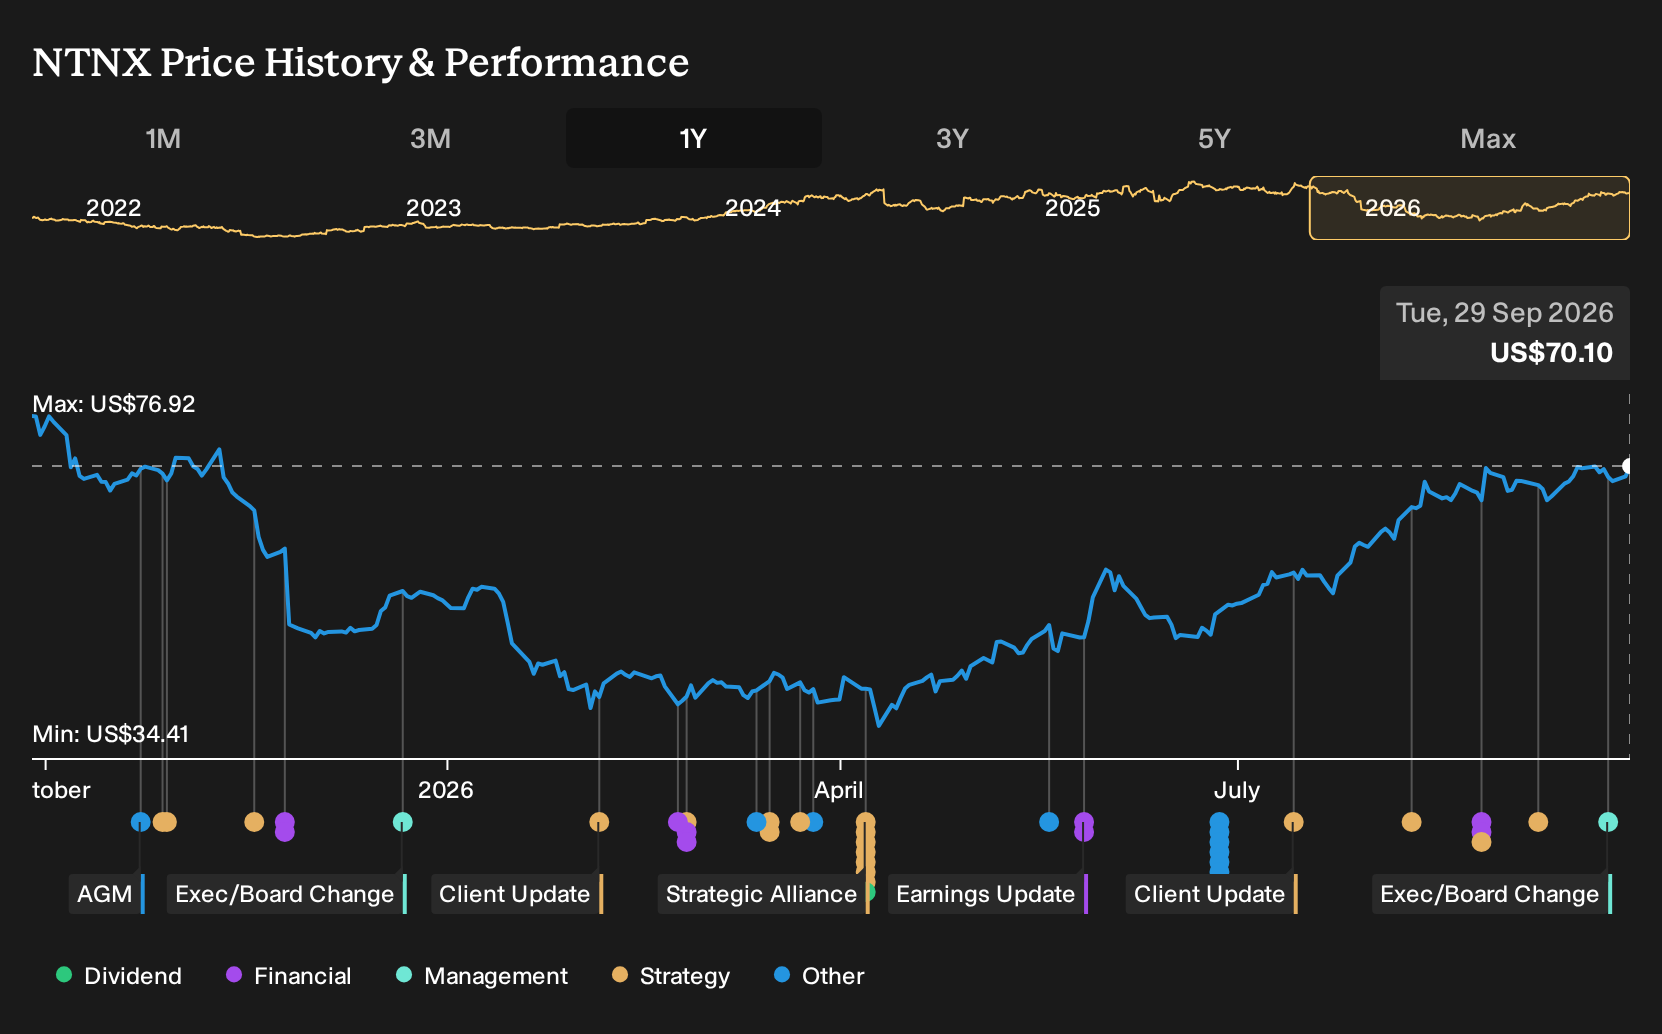
- Nutanix reported that President and Chief Commercial Officer Tarkan Maner stepped down in early October 2026. Oversight of sales, marketing, and customer experience is moving directly under CEO Rajiv Ramaswami, while Maner shifts focus to external board and advisory roles.
- The completed US$705.29 million repurchase of 13,574,000 shares reduces Nutanix's share count by 5.15%. This may slightly amplify per share metrics for remaining investors over time.
- We will now look at how Nutanix's investment narrative is affected by the CEO assuming direct control of commercial operations.
Compare how Nutanix's leadership shift and completed buyback stack up against other tech names actively reshaping their capital structure with our hand picked 32 high quality undervalued stocks.
Nutanix Investment Narrative Recap
Nutanix appeals to shareholders who think hybrid and multicloud infrastructure, AI workloads and subscription software can keep pulling more of the enterprise IT budget. The big question is how efficiently that opportunity turns into durable free cash flow. The recent leadership change concentrates commercial decisions with CEO Rajiv Ramaswami, which may influence execution speed more than the underlying demand picture.
For the near term, the key catalyst is whether Nutanix keeps converting its large enterprise relationships into longer, higher value contracts while controlling operating costs. The main risk remains competitive and pricing pressure, especially if slowing net retention or higher expenses start to weigh on earnings consistency.
The completed US$705.29 million buyback of 13,574,000 shares, or 5.15% of the float, is the update that ties closest to this story. A lower share count can magnify per share metrics, so investors will watch whether this financial move coincides with steady recurring revenue, given analysts currently forecast earnings declines over the next few years.
For anyone tracking catalysts, the repurchase also interacts with valuation and risk. Nutanix is described as trading about 15.3% below one fair value estimate and at a P/E of 12.3x compared with higher peer multiples. That support only matters if management, now with commercial operations under the CEO, keeps winning deals in hybrid cloud while guarding against cost creep and customer concentration.
Nutanix's current analyst narrative points to revenue of US$3.9b and earnings of US$584.9m by 2029, based on assumed yearly top line growth of 12.5% and an earnings increase of about US$309m from the US$275.9m reported today.
Uncover why Nutanix's fair value indicates a 14% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate view zooms in on recognition risk. The most bearish Nutanix analysts worry that slower conversion of VMware migration bookings into revenue keeps reported growth muted, even if demand holds up. They were pencilling in about US$4.0b of sales and US$546.5m of earnings by 2029, and may reassess after this leadership change and completed buyback.
Explore 2 other Nutanix fair value estimates, including one that suggests as much as 14% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Nutanix research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nutanix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nutanix's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nutanix?
Once you have a view on Nutanix, it can help to compare that thesis with other companies that share similar qualities around value, quality or risk. The Simply Wall St Screener lets you quickly filter the market so you can pressure test your Nutanix conclusions against a broader opportunity set.
- If capital preservation and steadier profiles matter most to you, start with a basket of 30 resilient stocks with low risk scores that score well on downside resilience.
- For investors hunting for mispriced quality, compare Nutanix with a 32 high quality undervalued stocks that combine fundamentals with attractive pricing.
- If balance sheet strength is your priority, work through a list of solid balance sheet and fundamentals (25 results) that pair financial flexibility with sound underlying businesses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com