
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Are Profitability Initiatives Altering The Investment Case For Cascades Stock (TSX:CAS)?
- Cascades has recently drawn attention for ongoing profitability initiatives that target a CA$100 million uplift by the end of 2026, with management focusing on lower unit operating costs in packaging and tissue tied to e-commerce and protective shipping demand.
- The effort to push the Bear Island mill toward Greenpac level efficiencies, combined with tighter control of chemical and material use, highlights how Cascades is trying to raise margins even if end demand stays flat.
- We will now examine how the investment narrative for Cascades could be reshaped by its push to cut unit operating costs and raise profitability.
Compare Cascades' cost-focused turnaround story with other companies targeting efficiency and earnings momentum by scanning our curated list of 9 high quality undiscovered gems.
Cascades Investment Narrative Recap
For Cascades, the core belief is that a cost focused, recycled based packaging and tissue business can compound value by steadily lifting efficiency rather than relying on booming demand. The short term swing factor is whether the profitability program, including Bear Island and tighter material use, keeps translating into higher earnings even if volumes stay muted.
The biggest near term risk is that the heavy lifting on costs does not fully offset weaker box shipments or tissue orders, especially around key retail periods, while interest expenses remain a drag. The recent update on cost savings does not fundamentally change that balance. It mainly reinforces that execution on efficiencies is still the main story to watch.
Among recent developments, the push to reach Greenpac type efficiencies at the Bear Island mill is the one that matters most for this cost story. It sits at the center of the CA$100 million profitability uplift Cascades is targeting by the end of 2026 and directly affects Packaging segment productivity and unit costs.
How quickly Bear Island hits its stride, alongside lower chemical and material usage, will shape whether earnings can grow in a flat demand backdrop and help reduce leverage toward management’s goals. If that ramp is slower or more expensive than planned, the firm remains more exposed to recovered fiber swings, one off charges and interest costs than investors might prefer.
Cascades' current analyst story points to CA$5.5b revenue and CA$322.8 million earnings by 2029, built on 4.8% yearly revenue growth and an earnings increase of about CA$196.8 million from CA$126.0 million today.
Uncover why Cascades' fair value suggests that the valuation gap aligns with its current price.
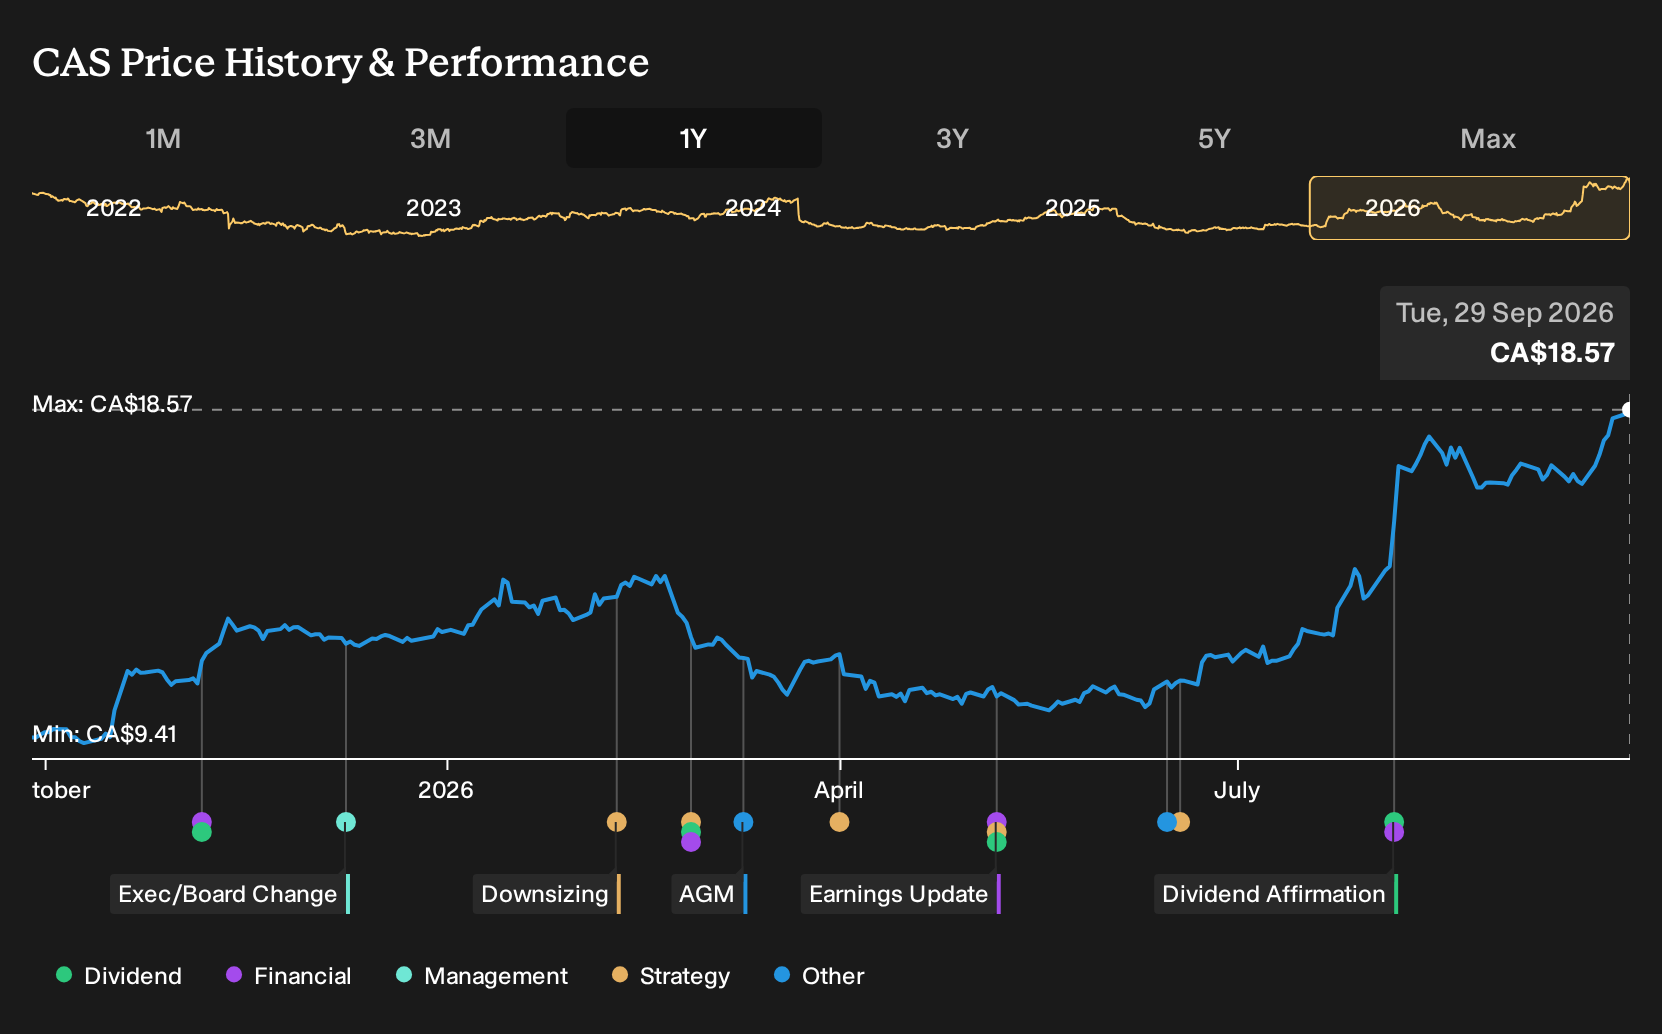
Exploring Other Perspectives
One alternate view on Cascades puts more weight on cost inflation risk than on efficiency gains. Those analysts were working with roughly CA$5.4b revenue and CA$337.4 million earnings by 2029, yet still used a lower CA$17.0 target. That more cautious stance could shift after this cost focused news, which is why exploring several viewpoints helps.
Explore 2 other Cascades fair value estimates, including one that suggests it could be worth just CA$18.50.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cascades research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cascades. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cascades' overall financial health at a glance.
Looking for more investment ideas beyond Cascades?
If Cascades' cost focused turnaround has you thinking about portfolio upgrades, use that same mindset when hunting for other opportunities. Screen for businesses that match your risk tolerance, income needs, and balance sheet comfort instead of relying on headlines.
- For investors who care most about quality at a sensible entry point, start with a focused set of opportunities by reviewing 7 high quality undervalued stocks.
- If capital preservation and steadier fundamentals matter more to you than chasing the highest upside, consider companies highlighted in the 8 resilient stocks with low risk scores.
- When income is a priority and you want yield backed by fundamentals, narrow your search using the 1 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com