
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Following MindRank AI Deal Is 3SBio (SEHK:1530) A Bargain Or Fully Priced?
Why MDR-001 Matters For 3SBio
3SBio (SEHK:1530) moved into focus after subsidiaries Zhejiang Sunshine Mandi and Zhejiang Wansheng signed a commercialization deal with MindRank AI for MDR-001, an oral GLP-1 obesity drug in Phase 3 trials.
The agreement covers mainland China, Hong Kong and Macau, with a potential transaction value up to RMB 1.75b, or about US$260m, tied to upfront funding and clinical, regulatory and commercial milestones.
Recent price action has been mixed for 3SBio, with the share price at HK$15.92 after a 1-day share price gain of 1.92% but a year-to-date share price decline of 35.23%. The 3-year total shareholder return of 161.27% points to strong longer term momentum.
Scan beyond 3SBio and this MDR-001 deal by reviewing a curated group of 133 healthcare AI stocks that connect AI-driven drug development directly to listed healthcare companies.
3SBio now trades well below where it started the year while attention shifts to MDR-001 and obesity. Does it make more sense to pay today’s price or wait and hope for an even cheaper entry?
Price-To-Earnings Of 4.1x: Is It Justified For 3SBio?
On valuation, 3SBio trades on a P/E of 4.1x while the last close was HK$15.92. This points to a materially cheaper earnings multiple than both peers and the wider Hong Kong Biotechs group.
The P/E ratio compares what investors are paying today for each unit of current earnings. For a profitable pharmaceutical group like 3SBio, which reported net income of CN¥8,270.6m on revenue of CN¥17,866.2m and net profit margins of 46.3%, this measure gives a direct read on how the market currently prices those profits.
Here, the gap is wide. Management has delivered very strong earnings growth over the past year, and profits have compounded at a high rate over five years. Yet the P/E of 4.1x sits well below the fair P/E estimate of 8.6x that the fair ratio model suggests the stock could move toward as sentiment and fundamentals realign.
Relative pricing tells the same story even more clearly. The Hong Kong Biotechs industry trades on an average P/E of 18.3x, and the peer group average is 36.5x, so 3SBio’s 4.1x earnings multiple is deeply below both the sector and direct comparables and signals that the market is pricing in substantial headwinds against those current profits.
Explore the SWS fair ratio for 3SBio.
Result: Price-to-earnings of 4.1x (UNDERVALUED)
Still, the sharp declines in annual revenue and net income growth, along with the wide 1 year total return fall, indicate that 3SBio’s low P/E may reflect real pressure.
Find out about the key risks to this 3SBio narrative.
Another View On 3SBio’s Valuation
The P/E story for 3SBio looks attractive, but the SWS DCF model also points to the shares trading below estimated value. At HK$15.92 versus a DCF value of HK$33.20, the stock screens as undervalued on cash flows too, which raises a tougher question for you: Is the market overly pessimistic, or is the model too generous?
Before leaning on any single approach, it helps to see how the cash flow work is built and what would need to change for 3SBio to close that gap. Look into how the SWS DCF model arrives at its fair value.
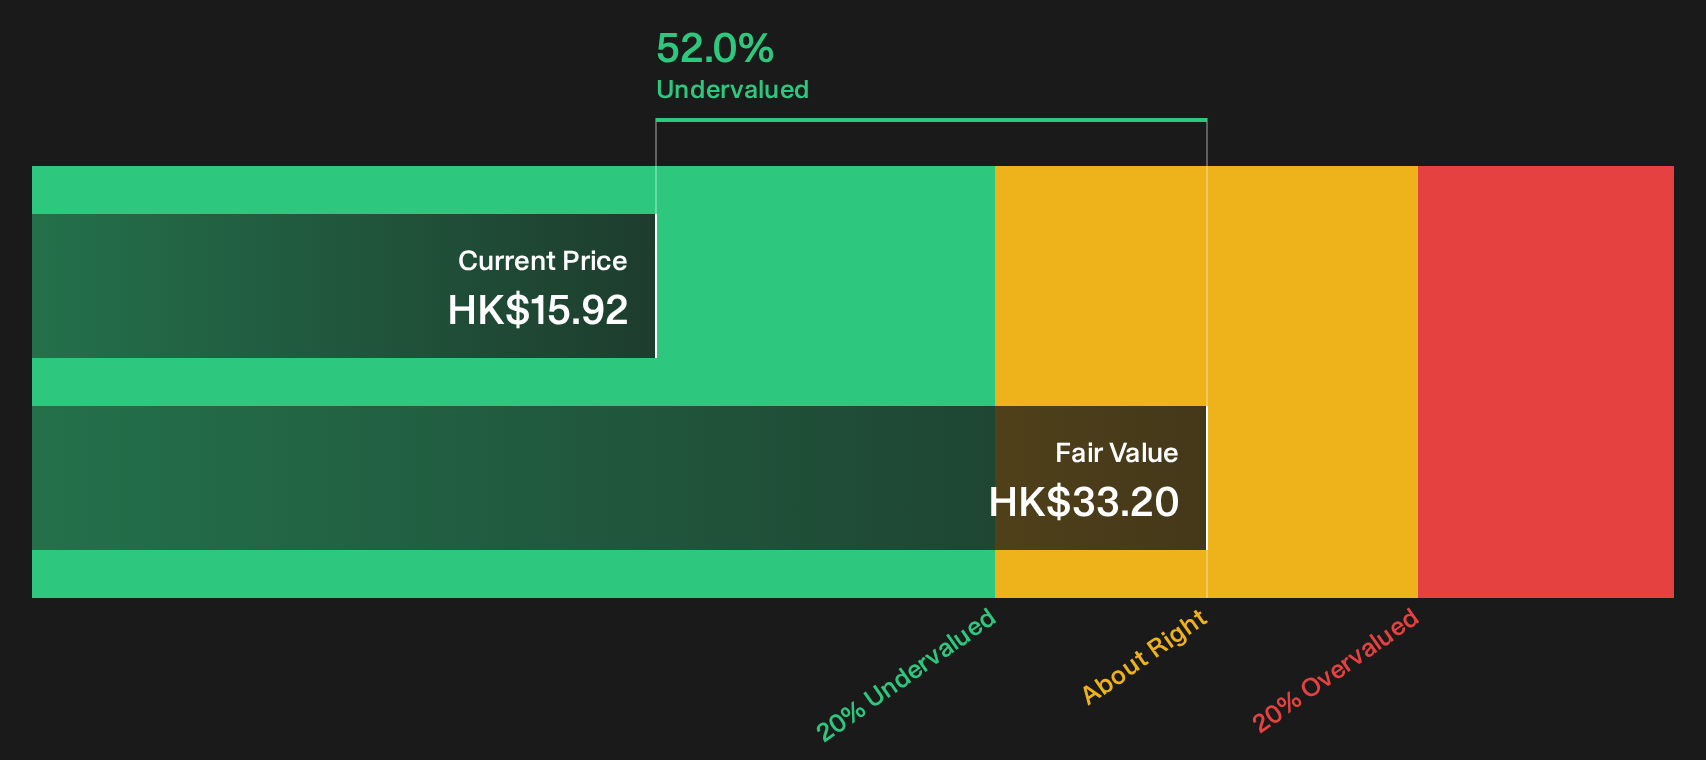
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out 3SBio for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 202 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around 3SBio can tempt you to wait on the sidelines, but the data is live and the story is developing now. Take a closer look at the 3 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond 3SBio?
If 3SBio has sharpened your focus on value and quality, do not wait around while other investors move first on the next set of opportunities.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (204 results) that filters for financial strength and staying power.
- Hunt for quality at a discount with a 202 high quality undervalued stocks that flags companies combining solid fundamentals with prices that lag their underlying metrics.
- Prioritise defensiveness and capital protection by reviewing a 225 resilient stocks with low risk scores that highlights businesses with lower risk scores and more measured profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com