
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Assurant (AIZ), Why Is Its Latest Update Drawing Attention?
Assurant (AIZ) has launched a new Financial Services Ecosystem Protection business in Chile, adding payment, purchase, fraud and vehicle financing protection solutions tailored to banks, digital wallets, marketplaces and other financial platforms.
Recent trading paints a mixed picture for Assurant. The share price is down 4.99% over the past week and 7.74% over the past month, yet the year to date share price return is 10.86% and the 3 year total shareholder return is 91.06%. This suggests long term momentum, while short term sentiment has cooled around the new Chile launch and other recent developments.
Scan beyond Assurant and spot other financial protection specialists that may be gearing up for their next move with our curated list of 30 resilient stocks with low risk scores.
Short term weakness has taken some heat out of Assurant after the Chile launch, while longer term returns remain strong. Does it make more sense to wait for a deeper pullback, or to focus on assessing the current entry point?
Most Popular Narrative: 20% Undervalued
Assurant last closed at $263.53, while the most followed narrative anchors fair value at $330. This points to a meaningful valuation gap that investors are actively trying to explain.
Continued build out of capital-light, fee-based businesses in Global Lifestyle and Housing, which together have supported high teens adjusted EPS growth excluding catastrophes over the first half of 2026 and an 11% adjusted EBITDA compound annual growth rate since 2020, can reinforce cash generation and support further upside to earnings if the mix shift continues.
See why 8 investors see Assurant as 20% undervalued.
Result: Fair Value of $330 (UNDERVALUED)
Still, the Assurant story can be knocked off course if regulatory pressure on lender placed products tightens, or if institutional selling accelerates and keeps valuation in check.
Find out about the key risks to this Assurant narrative.
Another Look At Assurant Using Market Ratios
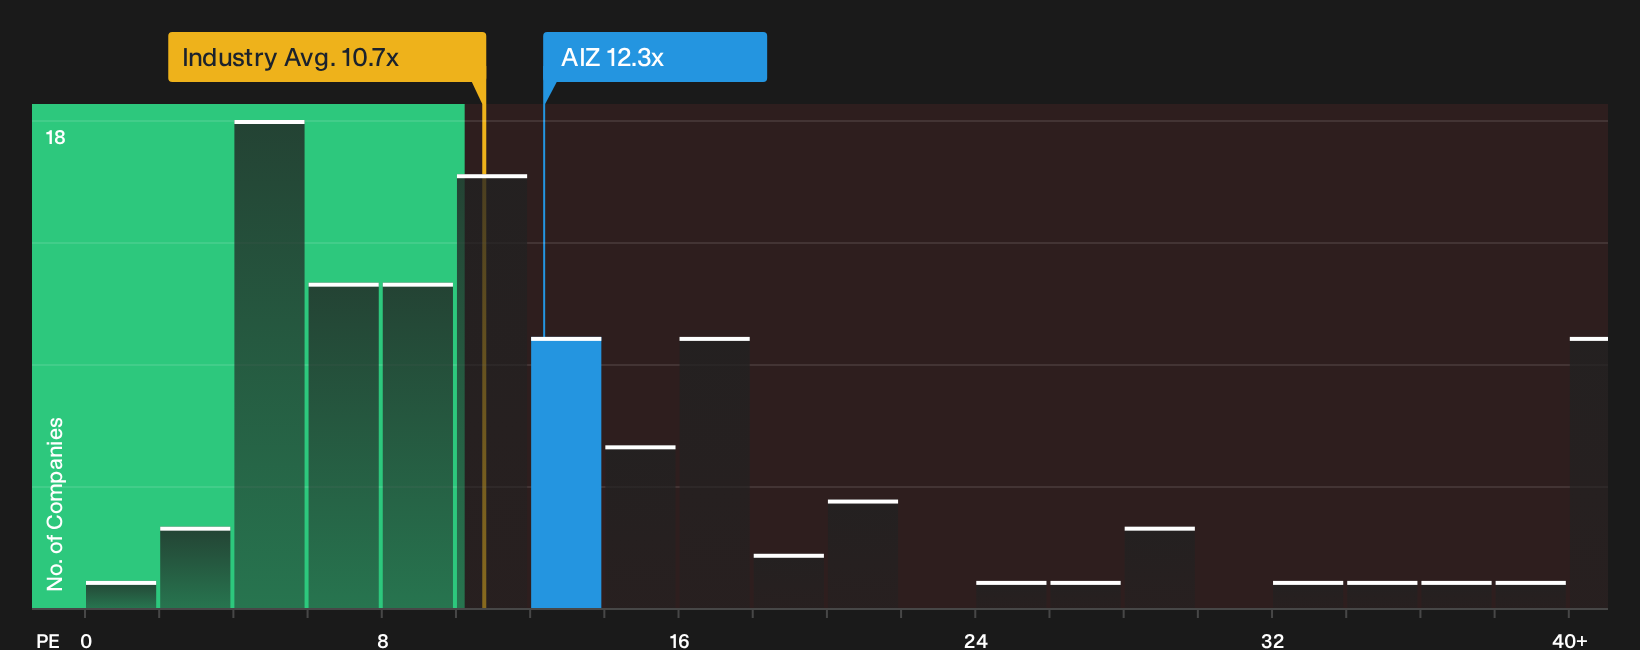
On price versus earnings, Assurant trades on a P/E of 12.3x. That is higher than the US Insurance group at 10.7x and also above a fair ratio of 11.7x that the market could move toward over time. If sentiment cools, could that premium leave little room for upside?
Numbers alone rarely tell the whole story, so it is worth checking how this valuation gap stacks up in a fuller comparison of Assurant against peers and the fair ratio in detail with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Assurant can pull you in either direction, so move quickly to review the full picture and weigh both sides using 4 key rewards and 1 important warning sign.
Looking for more Assurant-sized investment ideas?
You have seen how Assurant stacks up. Now widen your opportunity set and use the same structured thinking to hunt for your next potential winner.
- Target resilient opportunities by scanning a list of solid balance sheet and fundamentals (25 results) that can better handle shocks when conditions change.
- Hunt for potential bargains with a curated pool of 16 high quality undiscovered gems before attention and liquidity move the prices away from you.
- Prioritise capital preservation by zeroing in on a focused group of 30 resilient stocks with low risk scores that aim to keep downside pressures contained.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com