
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Applied Digital (APLD) Stock Looks Above Fair Value On Sales
Applied Digital has seen its share price swing sharply in recent years. This puts a spotlight on a simple question for investors: Is the current valuation of the stock properly anchored to its sales performance, especially after such a volatile run?
- Applied Digital has returned roughly 300% over the past 3 years. This makes it important to check whether that kind of share price change lines up with what its sales can reasonably support.
- The business now reports about US$36b in contracted long term lease value and a goal to reach a US$1b net operating income run rate sooner than originally planned. This can reshape how investors think about revenue visibility and the timing of cash flows against the current share price.
- Your read on Applied Digital is one view; the desks covering it have another. See what analysts think Applied Digital's shares could be worth.
The issue now is whether Applied Digital's current share price around US$24, given its recent performance and contract base, is justified by the sales it is generating and expects to earn from those leases.
If you want to test the same sales based valuation question that Applied Digital is raising here across a wider AI infrastructure set, take a look at 88 AI infrastructure stocks.
Does Applied Digital Look Pricey on Sales?
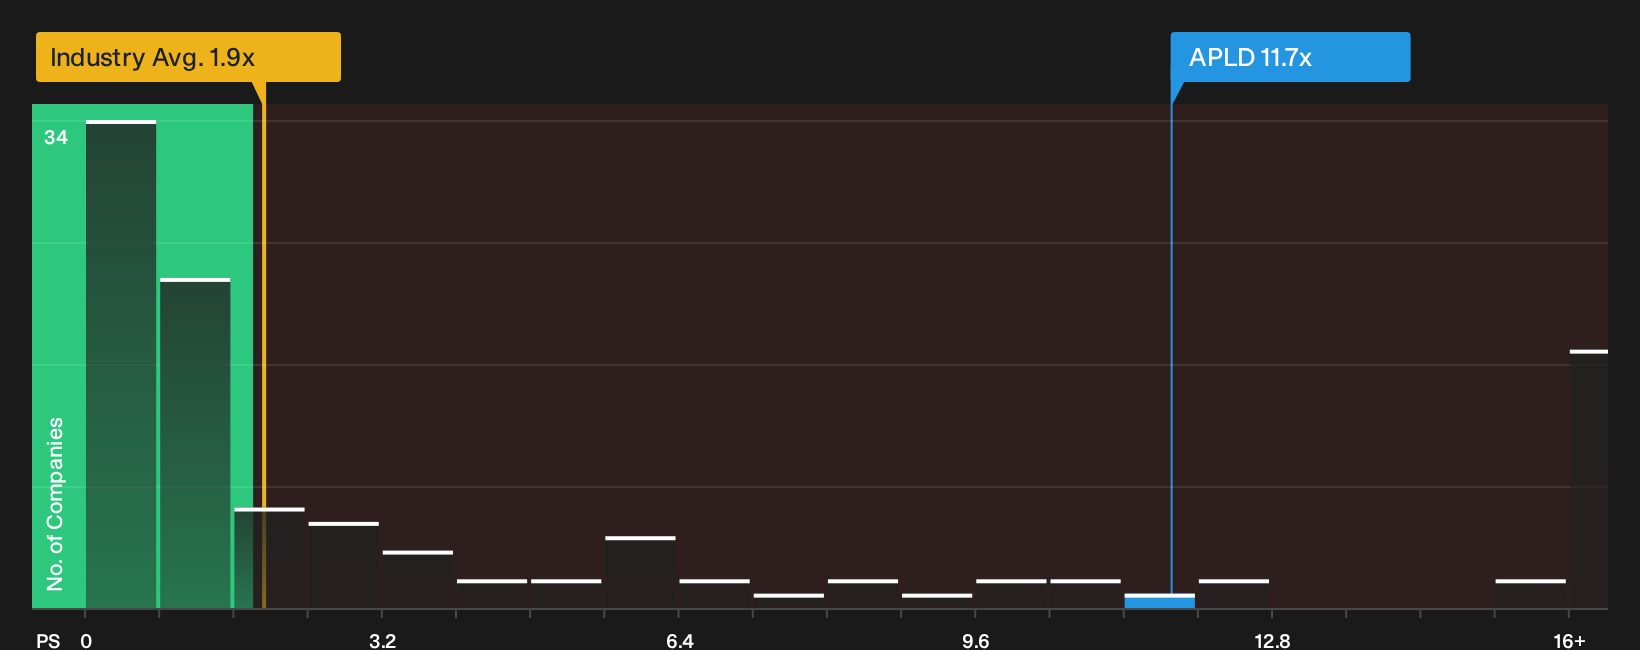
P/S suits Applied Digital because the business is heavily focused on large contracted leases and investors are mostly paying for revenue capacity rather than current earnings. On this yardstick, the stock trades on a P/S of about 11.7x, compared with an IT industry average of roughly 1.9x and a peer group around 6.9x. That is a sizeable premium to both broad sector levels and closer AI infrastructure comparables.
Because the company specific fair multiple that adjusts for growth potential, margin profile, size and risk sits below the current 11.7x, this framework flags Applied Digital as overvalued on sales. Despite the US$36b contracted lease base and management targeting a US$1b net operating income run rate sooner than first planned, the valuation already assigns a rich price tag to those ambitions and leaves less room for execution missteps or delays. Explore the numbers behind Applied Digital's P/S valuation.
The Applied Digital Narrative: What Would Justify Today's Price?
Narratives for Applied Digital pick up where the valuation question leaves off by spelling out what kind of growth, margin profile and earnings path would need to unfold for the current share price to look cheap or expensive on a sales lens. Each scenario links a fair value estimate to a specific mix of potential catalysts and risks so you can track over time which broad storyline seems to match how Applied Digital's business is actually evolving.
One of the top community narratives on Applied Digital: 64% undervalued
"Long-term AI hyperscaler contracts, efficient building processes, and strategic locations drive revenue growth, margin expansion, and sustainability advantages..."
Discover why this Narrative puts Applied Digital at 64% undervalued.
Before acting on Applied Digital's valuation, there is one more angle worth checking
Price today is only one side of the story, because professional coverage also sketches out where this business might be a few years from now and that outside view can sharpen how you judge the current tag. Explore where analysts expect Applied Digital to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com