
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Tyler Technologies (TYL) Could Be 40% Below Fair Value As Index Exit Stirs Debate
Tyler Technologies (TYL) has been dropped from the FTSE All-World Index (USD), a technical change that can matter for index funds and benchmark-aware investors. The removal sharpens the focus on how the stock trades without that index support.
Recent trading has been choppy for Tyler Technologies, with the share price down 14.27% over the past 30 days and 25.65% year to date, while the 1 year total shareholder return has declined 38.78%. This points to fading momentum despite a 10.79% 90 day share price gain.
Compare Tyler Technologies with a curated group of software peers that still have index support and steadier price action by scanning our 30 resilient stocks with low risk scores.
The sharp pullback in Tyler Technologies after its index exit now sits against analyst targets and intrinsic value estimates that indicate a wide gap. Where does a fair value anchor really land in that spread?
Most Popular Narrative: 124% Overvalued
On narrative fair value, Tyler Technologies screens as expensive, with Esteban's estimate of $144.97 sitting well below the last close at $324.02. That gap puts more weight on whether the underlying business story can justify paying more than double the narrative fair value.
Tyler Technologies is the dominant software platform for U.S. state and local government, a market defined by mission-critical workflows, 12 to 24 month implementation cycles, and a procurement environment that structurally protects incumbents. The investment thesis is built on three compounding forces: (1) a largely complete SaaS cloud transition that is converting a high-gross-margin subscription base from flat to accelerating, with ARR already at $2.06B and growing 11% annually; (2) a payments platform (NIC) that turns Tyler’s 40,000+ client relationships into a recurring transaction revenue stream now generating $808M per year and growing at double digits; and (3) a Tyler 2030 strategic roadmap that articulates a credible path to 30%+ non-GAAP operating margins by the end of the decade.
See why 7 investors see Tyler Technologies as 124% overvalued.
Result: Fair Value of $144.97 (OVERVALUED)
Still, Tyler Technologies faces pressure if on premises clients move to the cloud more slowly than expected or if stock based compensation continues to dilute holders.
Find out about the key risks to this Tyler Technologies narrative.
Another View On Tyler Technologies Valuation
That narrative fair value of $144.97 paints Tyler Technologies as expensive, yet the SWS DCF model points in the opposite direction. On that framework, the shares at $324.02 trade about 39.6% below an estimated future cash flow value of $536.81. This raises a simple question: which story deserves more weight in your process, the cash flows or the narrative anchor?
Before leaning on either view too heavily, it is worth seeing how the SWS DCF model is built for Tyler Technologies, including the cash flow assumptions and discount rate that drive such a different outcome, Look into how the SWS DCF model arrives at its fair value.
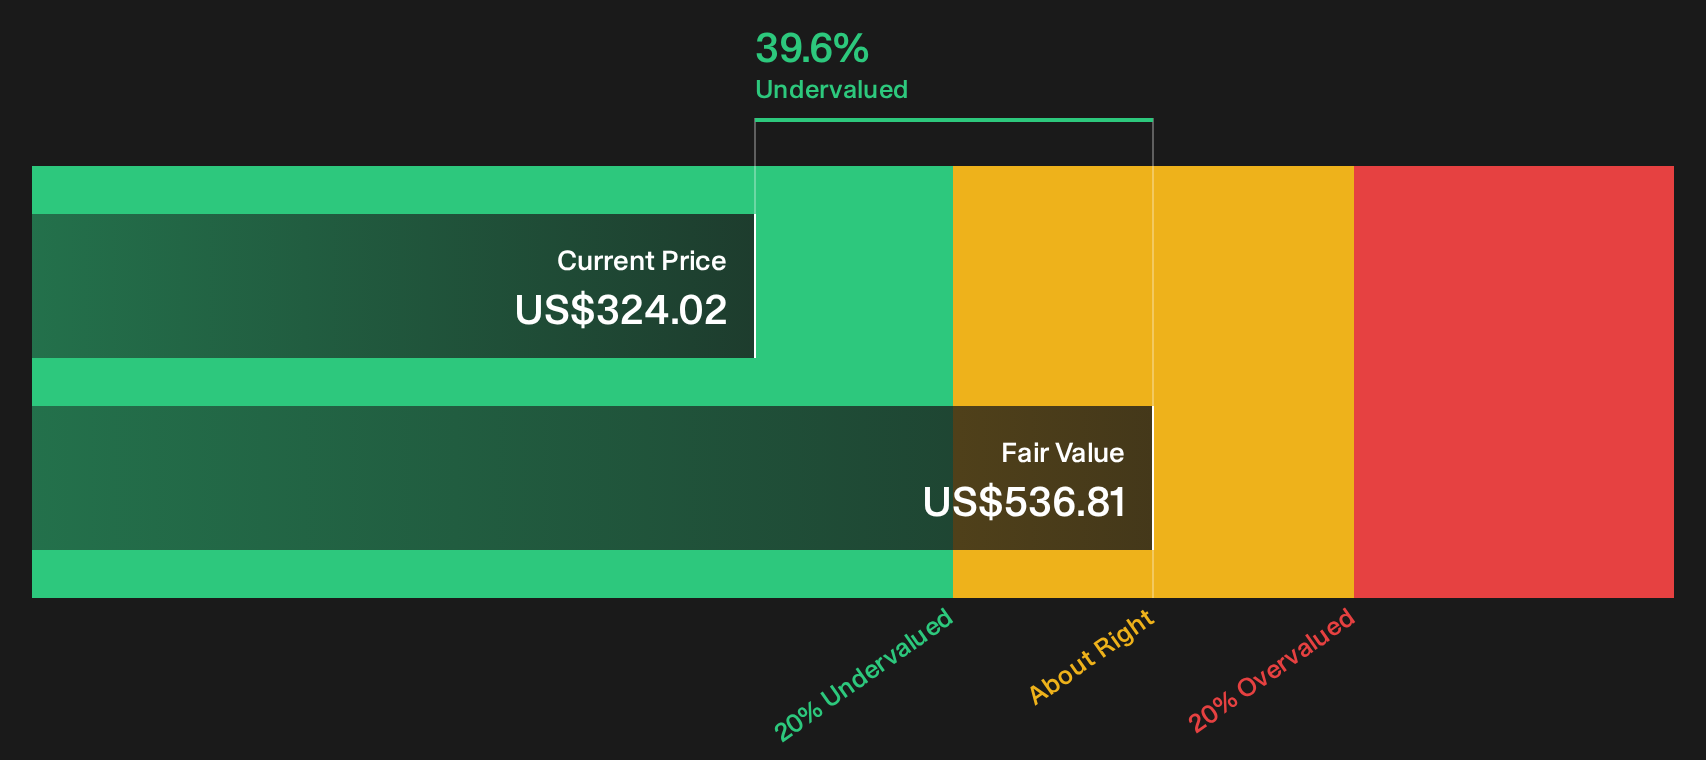
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tyler Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment across Tyler Technologies is clearly split, so it makes sense to move fast, review the underlying numbers yourself, and stress test every assumption before reacting to the headlines. For a quick snapshot of what optimists like about the business today, start with the 4 key rewards.
Looking For More Investment Ideas Beyond Tyler Technologies?
If Tyler Technologies has you rethinking your watchlist, now is the time to broaden your search and line up a few fresh candidates beside it.
- Target potential mispricings by scanning a curated pool of companies that combine quality fundamentals with appealing entry points using the 32 high quality undervalued stocks.
- Focus on stability and strong financial footing by reviewing a list of solid balance sheet and fundamentals (25 results) that can complement or contrast your Tyler Technologies position.
- Look for additional opportunities by sifting through 16 high quality undiscovered gems that could complement your current ideas before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com